
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
ABC Supply navigates a competitive landscape shaped by powerful buyer and supplier relationships, alongside the ever-present threat of new market entrants. Understanding these dynamics is crucial for any stakeholder looking to grasp the company's strategic positioning.
The complete report reveals the real forces shaping ABC Supply’s industry—from supplier influence to threat of new entrants. Gain actionable insights to drive smarter decision-making.
The building materials sector, particularly for essential items like roofing shingles and siding, sees a significant concentration of major manufacturers. This means a handful of large companies control a substantial portion of the supply for these core products.
This concentration grants these key suppliers considerable bargaining power, especially when dealing with distributors such as ABC Supply. Their leverage is amplified when it comes to products that are in high demand or are proprietary, allowing them to dictate terms more effectively.
However, ABC Supply's immense purchasing volume acts as a significant counterbalance. By being a critical customer for these manufacturers, ABC Supply can mitigate some of the suppliers' power, securing more favorable terms due to its substantial order sizes.
While many building materials appear similar, strong brand recognition and unique performance features significantly influence contractor choices. For instance, leading brands in roofing or insulation often invest millions in research and development, creating products with demonstrable advantages that are hard for competitors to replicate. This differentiation limits a distributor's flexibility to switch suppliers without potentially impacting their customer base and sales volume.
For ABC Supply, the bargaining power of suppliers is amplified by the significant switching costs involved in changing primary suppliers for a major product line. These costs can encompass substantial investments in retraining sales teams, reconfiguring inventory management systems, and potentially incurring penalties or losing favorable terms with current partners. In 2024, for instance, a company in a similar distribution sector reported that the average cost to switch to a new primary logistics provider exceeded $500,000, factoring in system integration and initial operational disruptions.
As the largest wholesale distributor of roofing and other exterior building products in North America, ABC Supply is a significant sales outlet for numerous manufacturers. In 2024, ABC Supply's extensive network and high purchasing volume mean that many suppliers rely heavily on the company for a substantial portion of their revenue. This reliance gives ABC Supply considerable leverage in negotiations.
Suppliers are motivated to offer competitive pricing and favorable terms to ensure their products remain accessible through ABC Supply's vast distribution channels. This dynamic can reduce the bargaining power of suppliers, as they may feel compelled to meet ABC Supply's demands to maintain their market presence and sales volume. For instance, a supplier whose sales are heavily concentrated with ABC Supply might find it difficult to push back on price reductions or other demands.
The threat of suppliers integrating forward and distributing directly to contractors exists, but it's generally constrained for a company like ABC Supply, which handles a wide array of products. This integration is more likely for niche or high-volume specialized items where a manufacturer might see a clear benefit.
For instance, while a roofing shingle manufacturer might consider direct sales for a massive commercial development, the sheer scale and logistical demands of replicating ABC Supply's extensive national distribution network are substantial deterrents. The investment in warehouses, transportation fleets, and local sales teams required to match ABC Supply's reach is significant, making it economically unfeasible for most manufacturers.
Suppliers' bargaining power is moderated by ABC Supply's significant purchasing volume and its status as a vital sales channel for manufacturers. While some suppliers are concentrated, ABC Supply's scale often allows it to negotiate favorable terms, especially given the high costs and complexity for manufacturers to establish their own competing distribution networks. This situation generally limits the suppliers' ability to dictate terms to ABC Supply.
| Factor | Impact on ABC Supply | 2024 Data/Observation |
|---|---|---|
| Supplier Concentration | Increases supplier power | Concentration in roofing materials exists, but ABC's scale mitigates this. |
| Switching Costs for ABC Supply | Lowers supplier power | High costs for ABC to switch suppliers limit their flexibility. |
| ABC Supply's Purchasing Volume | Decreases supplier power | ABC's large orders make them a key customer, giving them leverage. |
| Supplier Dependence on ABC Supply | Decreases supplier power | Many suppliers rely on ABC for substantial revenue, making them amenable to ABC's terms. |
| Manufacturer Forward Integration Threat | Low threat | The cost and complexity of replicating ABC's distribution network deter most manufacturers. |
 Detailed Word Document
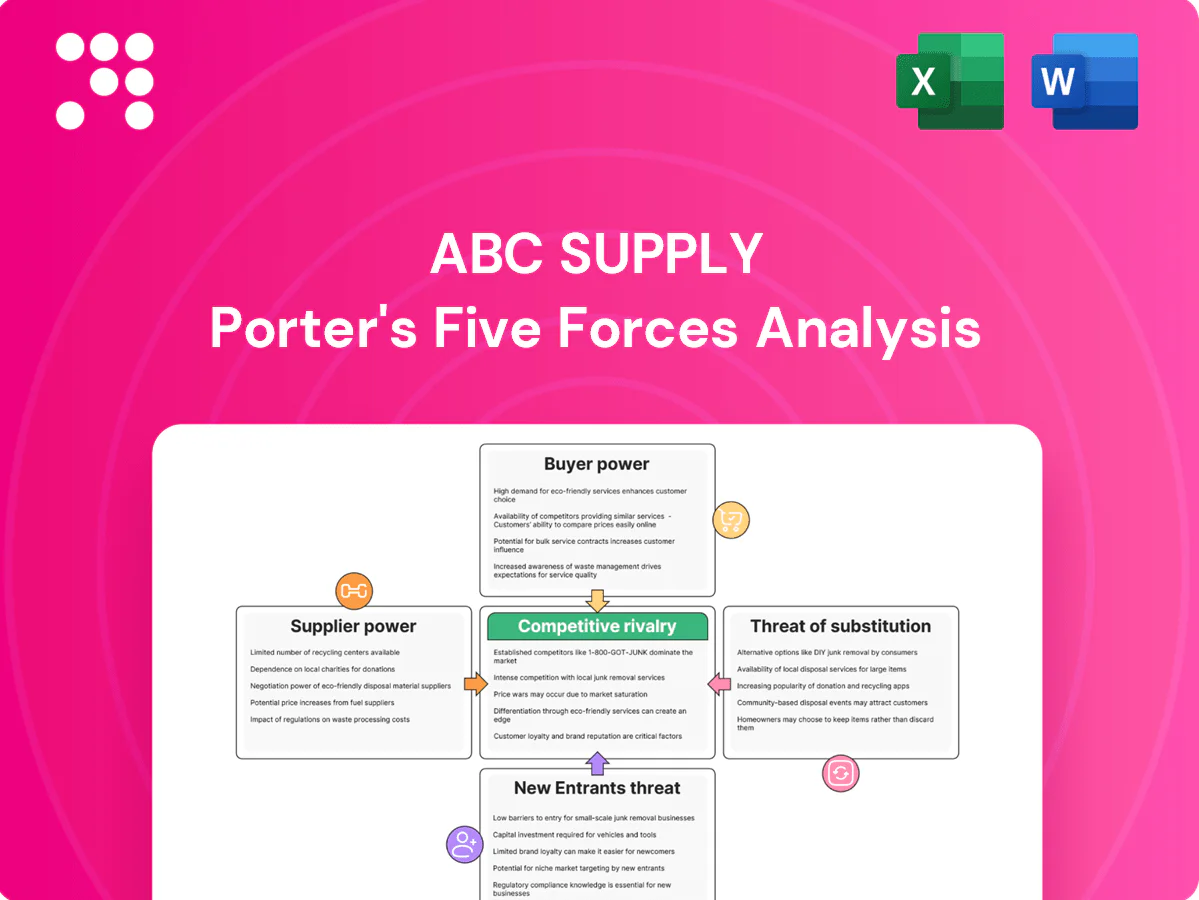
This analysis dissects the competitive landscape for ABC Supply by examining the bargaining power of buyers and suppliers, the threat of new entrants and substitutes, and the intensity of rivalry within the building materials distribution industry.

 Customizable Excel Spreadsheet
Quickly identify and address competitive threats with a visual breakdown of buyer power, supplier power, new entrants, substitutes, and industry rivalry.
ABC Supply's customer base is largely fragmented, primarily composed of numerous small to medium-sized professional contractors. This widespread distribution of customers means that no single contractor typically represents a substantial portion of ABC Supply's revenue. For instance, in 2024, the vast majority of ABC Supply's clients are independent businesses, with the top 10 customers likely accounting for less than 15% of total sales, a common characteristic in the building materials distribution sector.
Contractors in the construction sector are acutely price-sensitive, as material costs significantly impact their project profitability. This sensitivity means they actively seek competitive pricing, which can indeed exert pressure on suppliers like ABC Supply to maintain favorable margins. For instance, in 2024, the average profit margin for general contractors in the US hovered around 1.5% to 3%, underscoring the importance of cost control.
While price is a major consideration, it's not the sole determinant for contractors. Product availability and consistent, reliable delivery are paramount to keeping projects on schedule and avoiding costly delays. In 2024, supply chain disruptions continued to be a concern, making dependable suppliers a valuable asset, even if their prices are slightly higher.
Furthermore, favorable credit terms offered by suppliers can significantly influence a contractor's purchasing decisions. Access to working capital is crucial for managing cash flow, especially for smaller firms. Therefore, ABC Supply's ability to offer flexible payment options can be a powerful differentiator, balancing out pure price competition.
The building materials distribution market is highly competitive, featuring national players like Beacon Building Products and SRS Distribution alongside a multitude of regional and local independent suppliers. This abundance of choices significantly empowers contractors, as they can readily switch suppliers if ABC Supply fails to meet their specific requirements, thereby increasing customer bargaining power.
For many standard building materials, contractors face minimal costs when switching distributors. This ease of transition means a new supplier can often secure business simply by opening an account, highlighting a key aspect of customer bargaining power.
While existing relationships and credit terms offer some customer loyalty, these factors can be overcome. A significant price advantage or a more attractive service package from a competitor can readily shift contractor business, underscoring the low switching costs.
The bargaining power of customers in the building materials supply sector, specifically concerning ABC Supply, is influenced by the limited backward integration capabilities of most professional contractors.
Most contractors, even those who are quite established, simply don't have the financial muscle or the sheer volume of business to start buying directly from the original manufacturers for all the materials they need. Think about it – they need lumber, roofing, windows, doors, and a whole lot more. Setting up direct relationships for everything is a massive undertaking.
While a few of the absolute largest contractors might manage to strike direct deals for very specific, high-volume products, it's not the norm. The costs and headaches associated with managing logistics, warehousing, and inventory for such a diverse range of materials usually make it a non-starter for the vast majority of businesses in this industry.
The bargaining power of ABC Supply's customers is moderate to high, primarily driven by the fragmented nature of the contractor base and the competitive landscape. While contractors value reliable supply and credit terms, their price sensitivity and low switching costs mean they can readily shift business to competitors offering better deals. This dynamic forces ABC Supply to remain competitive on pricing and service to retain its customer base.
| Factor | Impact on ABC Supply | 2024 Data/Observation |
| Customer Fragmentation | Lowers individual customer power, but collective power is significant. | ABC Supply serves thousands of contractors, with no single customer dominating revenue. |
| Price Sensitivity | High, as material costs are a major driver of contractor profitability. | Contractor profit margins in 2024 averaged 1.5-3%, making price a key decision factor. |
| Switching Costs | Low, facilitating easy movement between suppliers. | Contractors often switch distributors based on pricing or service incentives. |
| Product Availability & Delivery | Mitigates price sensitivity; reliability is crucial. | Ongoing supply chain concerns in 2024 highlighted the value of dependable delivery. |
| Credit Terms | Can foster loyalty, but often secondary to price. | Flexible payment options are a competitive advantage for ABC Supply. |
This preview showcases the complete ABC Supply Porter's Five Forces Analysis, offering a detailed examination of competitive intensity and industry attractiveness. The document you see here is precisely what you will receive immediately after purchase, fully formatted and ready for your strategic planning needs.
ABC Supply faces significant competitive rivalry from large national distributors such as Beacon Building Products and SRS Distribution. These major players, along with numerous robust regional and local distributors, actively compete for market share in the building materials sector. This intense rivalry is often fueled by aggressive strategies, including strategic acquisitions and the expansion of physical branch networks.
The wholesale distribution of building materials is a mature industry, with growth largely mirroring the ups and downs of construction and renovation projects. For instance, in 2024, the U.S. construction spending was projected to reach approximately $1.9 trillion, indicating a steady but not explosive growth rate.
This maturity means companies like ABC Supply often face intense rivalry. Competitors frequently vie for market share through aggressive pricing strategies and by offering superior customer service or specialized product lines to stand out.
Many of ABC Supply's core products, like standard roofing shingles and vinyl siding, are considered commodities. This means there's not much to set one brand apart from another in terms of basic function.
When products are similar, competition often shifts to price. Distributors like ABC Supply find themselves competing on who can offer the best deal, alongside factors like how quickly they can get products to customers and the reliability of their service. For instance, in the building materials sector, price fluctuations can be significant, impacting distributor margins. In 2023, the average price of asphalt shingles saw a notable increase, driven by raw material costs, forcing distributors to manage inventory and pricing very carefully.
Competitive rivalry in the building materials distribution sector is intense, with major players like ABC Supply heavily investing in their physical presence and supply chain efficiency. These extensive branch networks are crucial for reaching a broad customer base, particularly contractors who rely on prompt access to materials. As of early 2024, ABC Supply operates over 900 locations across the United States, a testament to this strategic focus.
This infrastructure investment creates a significant barrier to entry and a key differentiator among competitors. The ability to deliver the right products, to the right job site, at the right time is a critical factor in customer loyalty. For instance, the logistical capabilities allow for efficient inventory management and rapid response to market demands, directly impacting service levels and competitive advantage.
ABC Supply's competitive landscape is intensified by high fixed costs inherent in the building materials distribution business. These costs, encompassing extensive warehouse networks, significant inventory levels, and dedicated transportation fleets, create substantial barriers to exiting the market.
These considerable upfront investments mean that companies with high fixed costs are less likely to cease operations easily, even during downturns. This situation traps capital and discourages new entrants who would need to make similar large investments, thereby prolonging the competitive struggle among existing players.
Competitive rivalry within the building materials distribution sector is fierce, driven by a consolidated market with substantial players like Beacon Building Products and SRS Distribution. These large companies, alongside a multitude of regional and local distributors, constantly vie for market share.
The industry's maturity, with U.S. construction spending projected around $1.9 trillion in 2024, means growth is steady but intense competition often centers on price and service due to the commodity nature of many products like asphalt shingles, which saw price increases in 2023.
ABC Supply, operating over 900 locations by early 2024, emphasizes extensive branch networks and logistical efficiency as key competitive differentiators. The high fixed costs associated with warehousing, inventory, and transportation create significant barriers to entry, further intensifying rivalry among established firms.
| Competitor | Approximate Number of Locations (Early 2024) | Key Competitive Strategy |
|---|---|---|
| ABC Supply | 900+ | Extensive branch networks, logistical efficiency, service |
| Beacon Building Products | 1,900+ | Scale, broad product offering, acquisitions |
| SRS Distribution | 400+ | Specialized product lines (e.g., roofing), regional focus |
The threat of substitutes for ABC Supply's core products, like asphalt shingles and traditional siding, is a significant factor. For instance, metal roofing has gained substantial market share, with its demand projected to grow steadily. In 2023, the global metal roofing market was valued at approximately $10.5 billion and is expected to reach over $14 billion by 2028, demonstrating a clear shift towards alternatives.
Furthermore, advancements in construction techniques, such as the increasing adoption of modular and prefabricated building components, present another substitute threat. These methods can streamline construction processes and potentially reduce the reliance on traditional, on-site material distribution services that ABC Supply specializes in. The prefabricated construction market, valued at over $150 billion globally in 2023, is experiencing robust growth, indicating a potential disruption to conventional building material supply chains.
While typically uncommon for most contractors, very large construction firms or those undertaking highly specialized projects might explore bypassing distributors like ABC Supply to purchase materials directly from manufacturers. This can sometimes lead to cost savings for these larger entities.
The increasing prevalence of e-commerce platforms presents another avenue where manufacturers could potentially foster more direct relationships with end-users. However, the logistical complexities associated with bulk construction materials often present significant hurdles for such direct-to-consumer models, making it a less common substitute for the services provided by established distributors.
For certain product segments, especially smaller projects or fill-in needs, professional contractors may view large home improvement stores as a viable substitute. While these big-box retailers primarily cater to do-it-yourself consumers, their dedicated contractor services and professional desks are increasingly offering solutions that could compete for specific business. For instance, Home Depot reported over $10 billion in sales to professional customers in 2023, highlighting their growing presence in this market.
The construction supply chain is rapidly digitizing, giving rise to specialized online distributors and e-commerce platforms. These digital channels offer contractors enhanced convenience, greater price transparency, and a broader product selection, appealing to those who value streamlined digital procurement processes.
These emerging online players can exert significant pressure on traditional distributors like ABC Supply. For instance, a report from McKinsey in early 2024 highlighted that digital sales channels in the building materials sector could capture a substantial portion of the market, potentially impacting established players' market share if they don't adapt.
A significant threat to ABC Supply's traditional wholesale model arises from the growing trend of contractors opting for rental or service-based solutions instead of purchasing raw materials. This shift represents a move away from owning and managing inventory towards accessing specialized equipment or integrated components as needed.
For instance, the construction industry is increasingly seeing demand for pre-fabricated wall panels that come complete with installed windows. This bypasses the need for contractors to source and assemble these components separately, potentially reducing their reliance on traditional distributors for individual items like lumber and windows.
This evolving market dynamic could indirectly impact ABC Supply's revenue streams. While not a direct product substitute in the traditional sense, the adoption of these service-oriented approaches by contractors can dampen the demand for the discrete building materials that form the core of ABC Supply's business. For example, a contractor using pre-fab units might no longer need to order large quantities of windows and lumber from a wholesale supplier.
The threat of substitutes for ABC Supply's offerings is multifaceted, encompassing alternative materials and evolving construction methods. For instance, metal roofing, a significant substitute for asphalt shingles, saw its global market value reach approximately $10.5 billion in 2023, with projections indicating continued growth. Similarly, the burgeoning prefabricated construction market, valued at over $150 billion globally in 2023, presents a substitute by streamlining processes and potentially reducing reliance on traditional material distribution.
Contractors are also increasingly turning to rental or service-based solutions instead of purchasing raw materials outright. This includes the adoption of pre-fabricated components, such as wall panels with installed windows, which bypass the need for sourcing individual items from distributors like ABC Supply. This shift can indirectly decrease demand for traditional building materials, impacting wholesale revenue streams.
| Substitute Type | Market Data (2023/2024) | Implication for ABC Supply |
| Metal Roofing | Global market valued at ~$10.5 billion (2023) | Direct competition for roofing material sales |
| Prefabricated Construction | Global market valued at >$150 billion (2023) | Reduced demand for individual components |
| Online Distributors/E-commerce | McKinsey report (early 2024) suggests significant market capture potential | Increased price pressure and altered customer expectations |
| Home Improvement Retailers (Contractor Services) | Home Depot reported >$10 billion in sales to professional customers (2023) | Competition for smaller projects and fill-in needs |
The wholesale building materials distribution sector demands significant upfront capital. Companies need to invest heavily in large inventories, extensive warehouse networks, and a robust fleet of delivery trucks to serve customers efficiently. For example, a new entrant might need tens of millions of dollars just to stock basic product lines and establish a regional distribution hub.
This high capital requirement acts as a substantial barrier to entry. Potential competitors are often dissuaded by the sheer financial commitment needed to compete effectively. Achieving the necessary economies of scale to be profitable is nearly impossible without this initial, large-scale investment, effectively limiting the threat of new entrants.
The need for an extensive national branch network presents a significant threat of new entrants for ABC Supply. ABC Supply boasts over 1,000 locations across North America, a vast physical footprint that facilitates localized service and quick delivery. Establishing a comparable network requires immense capital investment and considerable time, making it a substantial hurdle for newcomers aiming to compete effectively.
New companies entering the building materials distribution market would struggle to forge strong relationships with key suppliers. Established players like ABC Supply have cultivated decades-long partnerships, often securing preferential pricing and credit terms that are hard for newcomers to match. For instance, in 2024, major lumber producers continued to prioritize existing high-volume distributors, making it challenging for new entrants to gain access to consistent supply and favorable payment schedules.
Professional contractors often prioritize established relationships with distributors for consistent supply, dependable service, and vital credit lines. Building this level of trust and offering competitive credit facilities, crucial for attracting and retaining professional clientele, requires significant time and investment for any new market entrant.
The threat of new entrants in the wholesale building materials distribution sector, particularly for a company like ABC Supply, is somewhat mitigated by the significant barriers to developing customer trust and establishing robust credit lines. For instance, in 2024, the average credit term offered by established distributors to qualified contractors can range from 30 to 90 days, a critical factor for cash flow management in the construction industry. New entrants would need to demonstrate a strong financial footing and a proven track record to match these offerings, a process that typically takes years.
The threat of new entrants for ABC Supply is significantly influenced by the substantial economies of scale enjoyed by established players in purchasing and logistics. Large distributors can leverage their volume to secure preferential pricing from manufacturers, a crucial advantage. For instance, in the building materials sector, bulk purchasing can lead to discounts of 5-10% or more, directly impacting cost of goods sold.
New entrants would find it challenging to replicate these purchasing power advantages. Their smaller order volumes would likely result in higher per-unit costs, making it difficult to compete on price with incumbents like ABC Supply. This cost disadvantage is a major barrier to entry, as new companies would struggle to achieve comparable margins or offer competitive pricing to customers.
Furthermore, the logistics aspect presents another hurdle. Efficient supply chain management, including optimized warehousing and transportation, is vital for cost control. By 2024, the average cost of freight as a percentage of total sales for distributors can range from 3-7%, and scale allows for significant reduction in this figure. New entrants with less developed logistics networks would face higher operational costs, further diminishing their ability to compete effectively.
The threat of new entrants for ABC Supply is considerably low due to the immense capital required to establish a comparable operational scale and distribution network. Newcomers face significant hurdles in matching ABC Supply's extensive branch presence, which exceeds 1,000 locations, demanding substantial upfront investment and time to replicate.
| Barrier | Description | Impact on New Entrants |
|---|---|---|
| Capital Investment | Establishing a national branch network and maintaining large inventories requires tens of millions of dollars. | Deters potential competitors due to the sheer financial commitment. |
| Supplier Relationships | Decades-long partnerships secure preferential pricing and credit terms. | New entrants struggle to gain access to consistent supply and favorable payment schedules. |
| Customer Loyalty & Credit | Contractors prioritize established relationships and competitive credit lines. | New entrants need years and significant investment to build trust and match credit offerings (e.g., 30-90 day terms). |
| Economies of Scale | High purchasing volumes lead to 5-10% or more discounts and logistics cost efficiencies (3-7% of sales for freight). | New entrants face higher per-unit costs, making price competition difficult. |


