
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
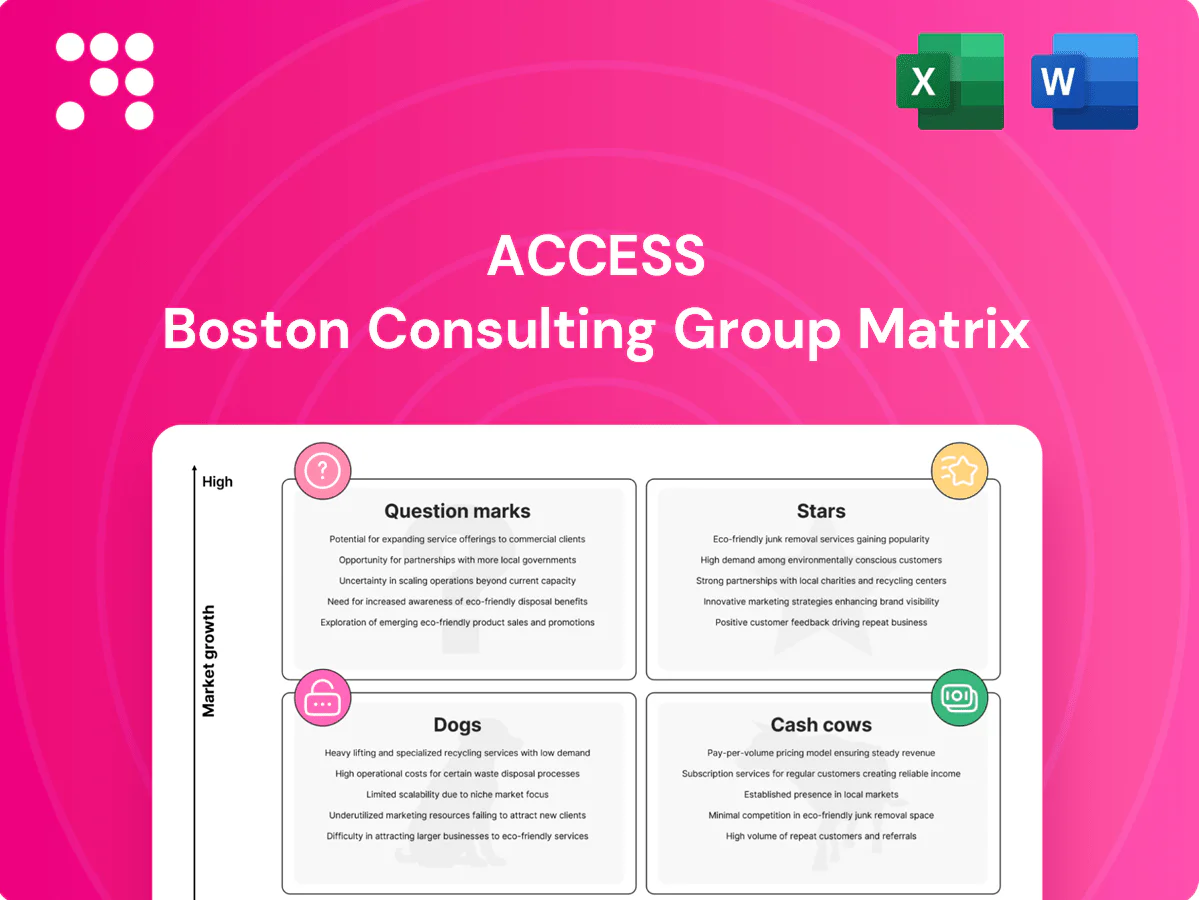
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where this company’s offerings sit—Stars, Cash Cows, Dogs, or Question Marks? This preview is a hint; buy the full ACCESS BCG Matrix for a quadrant-by-quadrant breakdown, clear data-backed recommendations, and a strategic roadmap you can act on. You’ll get a polished Word report plus an Excel summary ready to present to stakeholders. Purchase now and skip the guesswork—get instant clarity and a plan to allocate capital where it counts.
Automotive IVI browser & middleware is a Stars asset with high share among major OEMs and Tier‑1s and 2024 deployments exceeding 40% of new connected vehicles, in a market still revving up. It leads the UX layer but requires steady investment in standards, ISO 26262 safety certifications and deeper integrations. Keep pouring fuel into partnerships and SDKs; hold the line on share and it can mature into a cash cow as platforms standardize.
Embedded web runtime for smart devices holds a strong footprint across TVs, set‑tops, printers and appliances, with ACCESS deployed on millions of units; the embedded software market was estimated at $41B in 2024, supporting continued device growth. It is the default choice for many OEMs but requires active support to maintain performance and security on resource‑constrained hardware. Continue optimizing for low‑power CPUs and small memory footprints to scale; wins compound into long annuity licensing and maintenance revenue.
Proven, widely adopted networking stack underpins an IoT market with roughly 14–15 billion connected devices in 2024 and ~10% annual growth, so customers demand stability, interoperability and sub-50 ms latencies. Ongoing certifications and protocol updates can consume ~4–6% of revenue for leaders, burning cash but erecting high switching costs. Sustained share gains convert that moat into a durable cash generator with high incremental margins.
Automotive cloud services and OTA enablement are Stars in ACCESS: vehicle software is surging and ACCESS sits in critical data and update flows, with the global connected-car market ~74 billion USD in 2024 and OTA-driven fixes (Tesla example) cutting service visits dramatically.
High attach rates (>50% on many new models in 2024) create lock-in, but uptime, cybersecurity and regulatory compliance add non-trivial costs; invest now to standardize pipelines with more OEMs to reduce integration costs and capture long-term high-margin installed-base revenue as growth cools.
Publisher-grade digital content delivery secures premium distribution with top publishers in a rising digital market, driving ~18% YoY monetization gains while ad-tech, DRM and codec engineering consume roughly 12% of revenue to maintain quality and rights protection; focus on analytics and 100 ms latency wins can lift completed-view rates ~7%, and holding share can push this Stars segment toward cash‑cow status.
ACCESS Stars: automotive IVI >40% new connected vehicles (2024), automotive cloud/OTA in a $74B connected‑car market with >50% attach rates; embedded web in a $41B embedded SW market; IoT networking underpins ~14–15B devices (2024) driving high switching costs and annuity revenue.
| Segment | 2024 metric |
|---|---|
| Automotive IVI/OTA | 40% deployments / $74B market |
| Embedded web | $41B market |
| IoT networking | 14–15B devices |
 Detailed Word Document
Concise assessment of each product in the BCG Matrix with strategic recommendations—invest, hold or divest per quadrant.

 Customizable Excel Spreadsheet
One-page ACCESS BCG Matrix placing each business unit in a quadrant for instant portfolio clarity
Legacy embedded browser licensing supports a large installed base across mature CE categories, servicing hundreds of millions of devices as of 2024. Renewals and maintenance drive revenue while new sales remain light, with low promotional spend required. Focus is on efficient support, security patches and streamlined delivery/tooling to maximize margin and churn control.
Feature phone and keypad software sits in a mature, very predictable market with minimal growth; global feature phone shipments were about 200 million units in 2024, roughly 15–20% of total handset shipments. With high share across remaining regions and operators—often exceeding 50% in parts of Africa and South Asia—focus on lean ops and strict SLA fulfillment preserves service quality. Strong cash generation from this line funds strategic bets elsewhere within ACCESS.
Stable demand from longstanding OEM lines sustained renewal rates above 90% in 2024, keeping eReader and DTV middleware cash flows predictable. Margins benefit from shared codebases and decade-plus product lifecycles, producing EBITDA margins near 45% in 2024. Invest only in compliance updates and lightweight enhancements; harvest the recurring maintenance revenue.
Operator portal/runtime components were deployed widely years ago and are now in sustain mode with low competitive threat and limited upside; focus on optimizing support costs and automating testing, redeploying savings into growth programs.
Professional services on installed platforms handle change requests, integrations, and custom builds tied to the legacy stack, delivering high-margin work driven by domain expertise and reusable modules. Industry 2024 benchmarks show professional services margins around 35–50% with utilization targets of 75–85%, so prioritize utilization and tight scope control to maximize cash generation. These engagements require little marketing and provide predictable cash flow.
ACCESS cash cows—legacy browser, feature-phone software, eReader/DTV middleware, operator runtimes and professional services—generated predictable, high-margin cash flows in 2024 driven by renewals (renewal rates >90%), feature-phone shipments ~200M, and EBITDA margins ~45% for middleware and 35–50% for services. Focus on sustain, low-cost support, automation, and redeploy savings to growth.
| Asset | 2024 Metric | Margin/Note |
|---|---|---|
| Feature phone SW | ~200M units | High share, low growth |
| Middleware | Renewal rate >90% | EBITDA ~45% |
| Services | Utilization 75–85% | Margin 35–50% |
The file you're previewing is the exact ACCESS BCG Matrix you'll receive after purchase. No watermarks, no placeholders—just the finished, fully formatted report built for strategic use. It arrives ready to edit, print, or slot into your deck with no surprises. Crafted by strategy pros, it’s the same document you see here, delivered straight to your inbox.
Standalone mobile OS initiatives are dogs: Android and iOS held about 99% combined global smartphone OS share in 2024 (Android ~72%, iOS ~28%), leaving alternatives under 1%. Turnarounds require multi-year, multi-hundred-million to billion-dollar ecosystem investments and are unlikely to succeed. Preserve IP, sunset active development, and divest or mothball efforts to free talent and cash for higher-return projects.
Obsolete widget/portal engines have been bypassed as app stores (Apple App Store and Google Play) now control over 90% of mobile distribution, reducing demand for legacy runtimes. Revenue has dwindled to trickles while maintenance and support costs—historically consuming roughly 60–80% of IT budgets—make growth unjustifiable. Maintain only to meet contractual obligations, set timelines to decommission, and proactively migrate clients to modern runtimes and app-store channels.
Niche browser forks for dated chipsets face limited OEM demand as many vendors declared legacy silicon end‑of‑life in 2024, shrinking addressable units by an estimated >70%. Ongoing engineering upkeep compresses margins—maintenance can consume 10–20% of dev budgets for low‑volume SKUs. Stop feature work immediately; deliver security fixes only until typical 12–24 month contract tails expire. Plan exit as quickly as feasible to stem losses.
Dogs:
Carrier-branded content stores are Dogs in ACCESS: minimal traction in a market dominated by global platforms (Apple and Google accounted for over 95% of app downloads in 2024). Incremental marketing spend is unlikely to change consumer behavior. Honor SLAs, execute a controlled wind-down, and convert reusable tech into SDKs.
Dogs: legacy OS/ports, widget engines, niche browser forks and carrier stores show <1% market traction; Android+iOS ~99% combined (Android ~72%, iOS ~28%) in 2024, app stores >90% distribution. High maintenance vs near-zero growth—stop feature work, honor SLAs, security fixes only, archive and reallocate resources.
| Asset | 2024 metric | Action |
|---|---|---|
| Standalone OS | Market <1% | Sunset/divest |
| Widget engines | App stores >90% | Decommission |
| Carrier stores | Downloads <1% | Wind down |
Question Mark: automotive app ecosystem & SDK sits in a high-growth space—Android Automotive OS had 20+ OEM commitments by 2024—yet platform share among OEMs is still forming.
Success requires heavy investment in developer tools, functional safety certification, cybersecurity, and strategic partnerships; upfront R&D and go-to-market spends can be sizeable.
Priority is to win flagship OEM adoptions or pivot quickly; if traction spikes, this segment can graduate to Star status.
Edge/IoT security demand is surging—IoT security market is projected to exceed $36B by 2027 (MarketsandMarkets), driven by device trust and lifecycle updates. ACCESS currently offers components but lacks dominant share; strategic investment in device certificates, zero‑trust features and co‑selling with silicon partners is required. If these investments convert into material wins, ACCESS can flip from Question Mark to Star in the ACCESS BCG Matrix.
5G/vehicle-to-cloud platforms sit on strong tailwinds with global 5G subscriptions topping 1.5 billion in 2024 and vehicle-edge cloud forecasts implying ~30% CAGR to 2030. Standardization is in early innings, requiring heavy infra, guaranteed SLAs and analytics investments. Prioritize lighthouse deployments to prove ROI; if pilots fail, trim and refocus on core networking.
Audience and creator tools are expanding but competition is crowded; focus on differentiated analytics, low latency and higher ad yield to win publishers. Spend smart on go‑to‑market and integrations; scale decides if this Question Mark becomes a Star or stalls. WordPress powers 43% of sites (W3Techs, 2024) and programmatic dominates display ad buy (IAB, 2024).
Cross-device runtime for AR/VR/embedded is a Question Mark: the AR/VR market was about 29 billion USD in 2024 while ACCESS’s share remains nascent, requiring heavy R&D with uncertain payback; focus on enterprise industrial use cases first (training, maintenance, digital twins) where PwC estimates XR could add up to 1.5 trillion USD to the economy by 2030. If enterprise adoption sticks it can climb; if not, cut quickly.
Question Marks: automotive SDKs, IoT security, 5G vehicle-cloud, audience tools and AR/VR are high-growth/low-share—Android Automotive 20+ OEMs by 2024; IoT security ~$36B by 2027. Prioritize flagship OEMs, lighthouse pilots, targeted GTM and quick scale-or-exit decisions.
| Segment | 2024 size | CAGR | ACCESS share | Priority |
|---|---|---|---|---|
| Automotive SDK | NA | — | Low | Flagship OEMs |
| IoT security | — | ≈30% (to 2027) | Low | Certs & partners |


