
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
ACCO Brands SWOT Analysis highlights the company’s global distribution strength, recognizable brands, and product diversification alongside risks from commodity costs, retail concentration, and digital disruption. Discover actionable strategic recommendations and financial context in the full report. Purchase the complete SWOT for editable Word and Excel deliverables to plan, pitch, or invest with confidence.
ACCO Brands leverages a portfolio including Mead, Five Star, AT-A-GLANCE and Kensington, four recognizable names that drive shelf space, pricing power and cross-channel loyalty. That brand equity lowers customer acquisition costs versus lesser-known rivals, enables cross-selling across categories and strengthens category defense in retail and B2B channels.
ACCO Brands spans school, office, and tech accessories across retail, e-commerce and B2B, giving it a wide product and route-to-market footprint. That diversification smooths cyclical back-to-school seasonality and uneven office spend, while enabling rapid reallocation of inventory and marketing to faster-growing tech and e-commerce channels. Channel breadth also increases resilience when any single route softens.
ACCO Brands leverages global manufacturing and distribution across more than 100 countries, enabling scale efficiencies and local-market access that supported approximately $2.1 billion in net sales in fiscal 2024. Regional sourcing and logistics shorten lead times and lower landed costs, helping sustain gross-margin resilience. The global footprint supports retailer programs and private-label partnerships and helps balance currency and demand fluctuations.
Continuous product refreshes keep legacy categories relevant and defend share, with Kensington driving expansion in ergonomic, security and connectivity lines and supporting higher-average selling prices through premium tiers and improved margin mix.
Established ties with mass retailers, office superstores and back-to-school merchants drive consistent volume and seasonal lift; ACCO operates in over 100 countries, supporting broad distribution. Vendor programs and real-time data sharing strengthen in-store execution and shelf visibility. Scale and reliability make ACCO a preferred partner for peak seasons, while joint planning with key retailers improves forecasting and inventory turns.
ACCO Brands' heritage labels (Mead, Five Star, AT-A-GLANCE, Kensington) drive shelf presence and lower acquisition costs. Diversified retail, e-commerce and B2B channels smooth back-to-school and office cyclicality. Global manufacturing/distribution in 100+ countries supported approximately $2.1 billion in net sales in fiscal 2024. Kensington expands premium ergonomic/security lines, improving margin mix.
| Metric | Value |
|---|---|
| FY2024 net sales | $2.1 billion |
| Countries | 100+ |
| Core brands | 4 |
| Channels | Retail, e-commerce, B2B |
 Detailed Word Document
Delivers a strategic overview of ACCO Brands’s internal and external business factors, outlining strengths, weaknesses, opportunities and threats to assess its competitive position and growth prospects.

 Customizable Excel Spreadsheet
Provides a concise SWOT matrix for fast strategy alignment, helping stakeholders quickly identify ACCO Brands' strategic blind spots and prioritize fixes for immediate impact.
A meaningful portion of ACCO Brands revenue—roughly 25% of 2024 net sales—still depends on traditional paper and analog supplies. Structural digitization is eroding long-term demand for planners, binders and notebooks, with segment volumes down year‑over‑year. The company increasingly relies on price promotions to maintain volumes, weighing on sustained organic growth and compressing margins by about 150 basis points.
Back-to-school creates a heavy Q3 concentration for ACCO Brands, intensifying demand in a narrow selling window and raising forecasting stakes.
Forecast errors can produce inventory risk and markdowns, pressuring gross margins and channel relationships.
Cash flow timing becomes lumpy, complicating working capital management, while operational leverage can amplify quarter-to-quarter swings in earnings.
Customer concentration is a material weakness for ACCO Brands: fiscal 2024 net sales were about $1.66 billion and large retailers/distributors accounted for a disproportionate share of revenue. Aggressive terms, chargebacks and private‑label pushes by these accounts compress margins and amplify working capital strain. Losing a major account or further margin pressure from the top five (≈28% of sales) would materially reduce volumes and give buyers outsized negotiating power.
International revenue and global sourcing expose ACCO Brands to FX translation and transaction risk, while volatile pulp, resin, freight and labor costs drive input-price uncertainty. Hedging programs partially offset swings but leave timing gaps and basis risk, and pricing lags during inflationary spikes can compress gross margins. These dynamics reduce margin predictability and pressure operating income.
Legacy complexity: ACCO Brands operates a broad SKU base and multiple acquired brands, which raises overhead and supply-chain friction; the company reported approximately $2.05 billion in net sales in fiscal 2024, amplifying scale-related integration needs. Portfolio pruning risks short-term disruption, while IT/ERP harmonization requires continued capital and multi-year rollout.
Paper sales ~25%, promo -150bps, top-5 ≈28%
ACC0 Brands depends on legacy paper/analog products (~25% of 2024 net sales) as digitization trims volumes and forces promotional pricing, cutting margins ~150 bps. Heavy Q3 back-to-school concentration raises forecasting and inventory risk. Top-five customers account for ≈28% of sales, increasing buyer leverage. Global sourcing exposes margins to volatile commodities, freight and FX.
| Metric | 2024 |
|---|---|
| Net sales | $2.05B |
| Paper/analog share | ~25% |
| Top-5 customer share | ≈28% |
| Margin promo impact | ~150 bps |
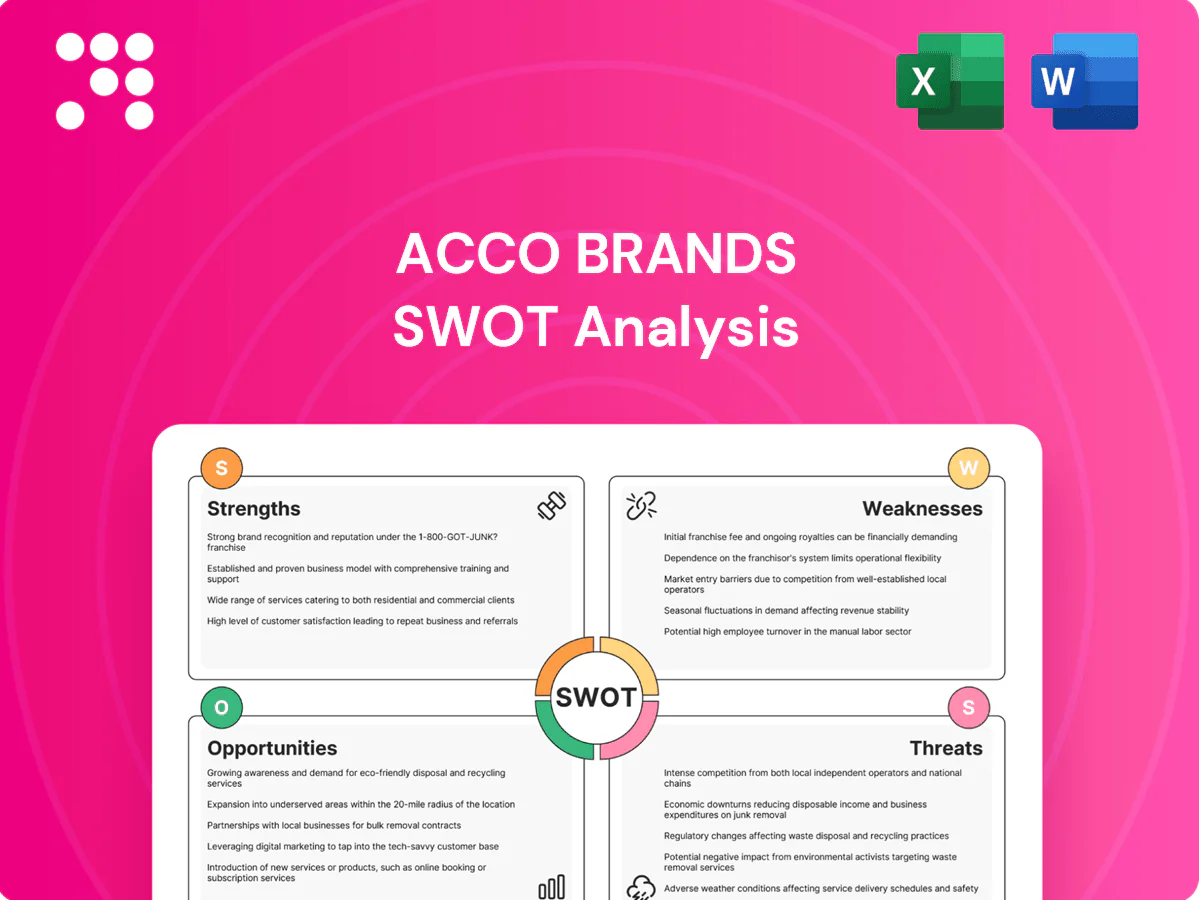
This is the actual ACCO Brands SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report you’ll get; buying unlocks the complete, editable version. You’re viewing a live excerpt of the real file, ready for immediate download after checkout.
Kensington, an ACCO Brands business unit, can leverage ergonomic, security, and connectivity accessories to meet continuing hybrid work demand; the global docking station market was projected at about $1.2–2.1 billion by 2030 (industry estimates, 2024). Expanding into docks, webcams, and wellness products plus SMB/education bundles can raise average order value and margin. Content-led e-commerce can accelerate category penetration and repeat purchase rates.
Recycled, refillable and durable materials let ACCO Brands target premium pricing—sustainability premiums often range 5–15%—while FSC/ISO certifications open institutional and government procurement opportunities. The global sustainable packaging market, valued at about $262.5B in 2020 and projected to ~ $375B by 2026, underscores demand. Sustainable redesigns can cut material use and freight intensity, lowering COGS and emissions. Clear ESG claims differentiate versus private labels.
Optimizing marketplaces and owned sites can lift mix and data visibility for ACCO Brands, which reported roughly $1.6 billion in net sales in fiscal 2024, making digital mix gains meaningful to margins. Enhanced content, subscriptions and personalization historically boost conversion rates by double digits, improving lifetime value. Expanding DTC reduces reliance on a few large retailers while richer customer data accelerates product innovation cycles.
ACCO can expand into EdTech adjacencies by supplying Chromebook/tablet accessories and rugged device protection while bundling classroom management and charging solutions for district contracts; U.S. K‑12 ESSER funding totaling about 190 billion USD supports multi‑year device refresh cycles through 2024–25.
Pruning low-velocity SKUs can simplify ACCO Brands operations and lift margins, targeting cost structure improvements after FY2024 net sales of roughly $2.3 billion; bolt-on M&A in high-growth niches could offset core declines and accelerate category expansion. Licensing deals enable asset-light brand monetization, while targeted divestitures can de-lever (net leverage ~2.3x in 2024) and refocus on profitable categories.
ACCO can grow margins and AOV via Kensington docks/webcams, DTC and SMB/education bundles; FY2024 net sales ~$2.3B make digital mix gains material. Sustainability redesigns target 5–15% price premiums and access institutional procurements; sustainable packaging market ≈$375B by 2026. ESSER ~$190B supports K‑12 device accessory rollouts.
| Opportunity | Metric | Figure |
|---|---|---|
| Docking/AV | Market proj. (2030) | $1.2–2.1B (2024 est.) |
| Company scale | FY2024 net sales | $2.3B |
| Education funding | ESSER | $190B |
| Sustainability | Packaging market (2026) | $375B |
Rivals and retailer private-labels erode price and shelf share; private-label penetration rose to about 18% in many categories in 2024, intensifying space battles. Digital-native brands with lean cost structures undercut prices and scale rapidly online. Low switching costs for office and school buyers make retention harder, and promotional-heavy markets heighten margin compression risk for ACCO Brands.
Cloud collaboration platforms and remote learning are cutting demand for analog supplies, with many U.S. districts moving toward 1:1 device provisioning (over 50% adoption in several states by 2023) and enterprises increasing device fleets. Paperless workflows have compressed legacy TAM—office paper demand is down noticeably versus a decade ago—pressuring ACCO Brands’ core categories. Long-term digital adoption risks eroding demand faster than reinvention can offset, risking margin and revenue decline.
Geopolitics, tariffs and logistics bottlenecks cited in ACCO Brands 2024 Form 10-K have delayed shipments and raised lead times. Component and raw-material shortages produced production gaps for office-products suppliers. Container freight rates surged up to tenfold in 2021–22 and remained volatile into 2024, raising costs unpredictably. Service failures risk retail scorecard penalties and lost shelf space.
Macroeconomic downturns can sharply reduce consumer and SMB discretionary accessory spend, pressuring ACCO Brands' sell-in even if sell-through holds; retailers' destocking can cut orders quickly and margin pressure forces deeper promotions to clear inventory, while currency volatility amplifies weakness across Europe and Asia.
Connected accessories and growing DTC operations expand ACCO Brands’ attack surface, increasing likelihood of cyber intrusions; the average global cost of a data breach was $4.45 million in 2024 (IBM). Data breaches can trigger regulatory fines and reputational damage that depress sales, while product safety or compliance failures may force recalls; legal and remediation expenses can run into multi‑million dollars.
Rising private-labels (~18% share in many categories, 2024) and lean digital rivals erode price and shelf share. Paperless workflows and 1:1 device adoption (50%+ in several US states by 2023) shrink legacy TAM. Logistics volatility (container rates up to 10x in 2021–22) and macro weakness force promotions; cyber breaches cost ~$4.45M (IBM, 2024).
| Threat | Metric |
|---|---|
| Private-label | ~18% (2024) |
| Device adoption | 50%+ states (2023) |
| Freight spike | Up to 10x (2021–22) |
| Data breach cost | $4.45M (2024) |


