
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
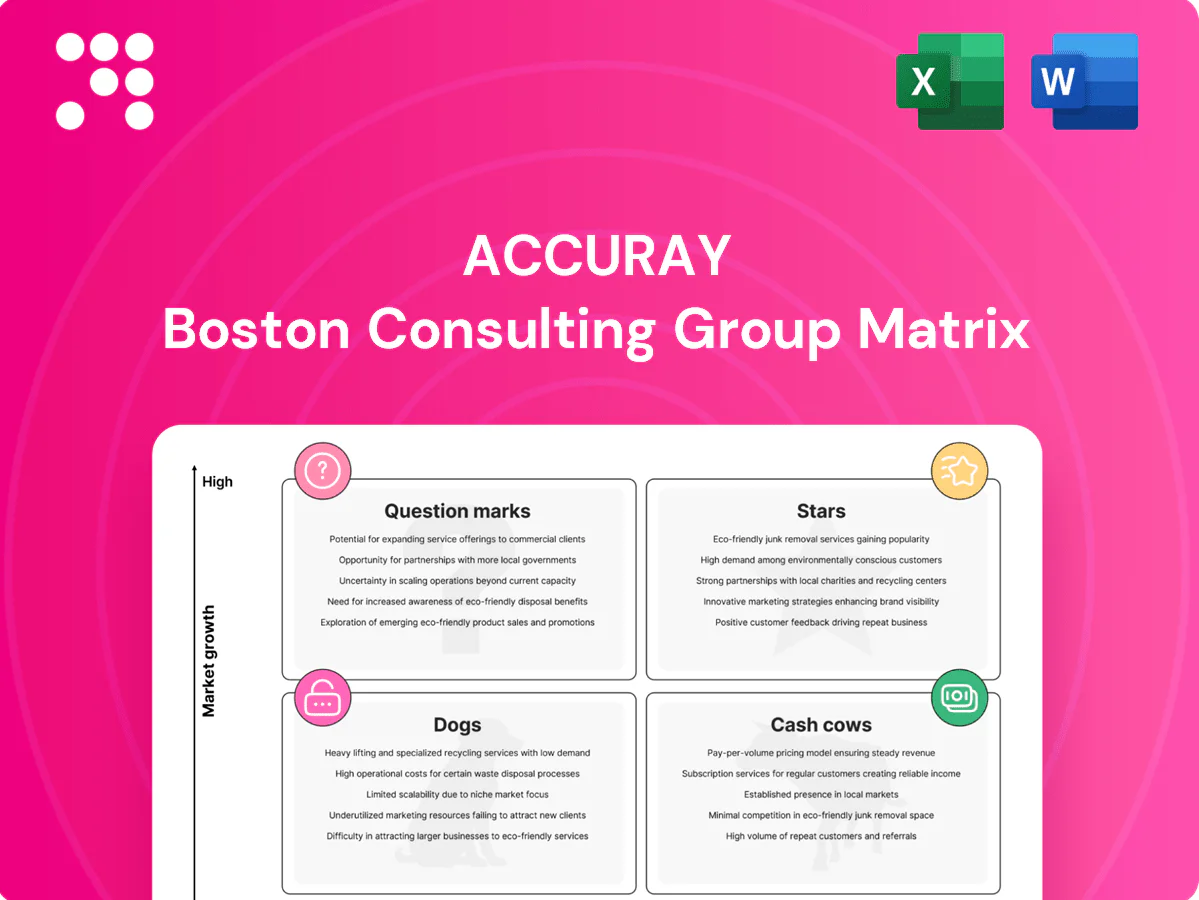
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Accuray’s products land—Stars, Cash Cows, Question Marks or Dogs? Our BCG Matrix preview teases the story; the full report maps every product to its quadrant with data-backed insights you can act on. Purchase the complete BCG Matrix for quadrant-by-quadrant strategy, visual maps, and downloadable Word + Excel files to present and execute with confidence.
CyberKnife holds a leading share in stereotactic radiosurgery with an installed base exceeding 1,000 systems worldwide as of 2024 and a rapidly expanding extracranial use case mix. Its sub-millimeter precision and real-time tracking deliver clear clinical differentiation, driving strong mindshare among radiation oncologists. Continued investment in KOL studies, physician training, and country-specific access is required. Holding leadership can convert CyberKnife into a larger cash-generating platform.
Radixact/TomoTherapy sits in Stars: as of 2024 Accuray supports an installed base exceeding 1,000 systems worldwide, with rising demand for precision radiotherapy in high-volume oncology centers; the Radixact upgrade cycle keeps clinical capability current though sales still require a heavy commercial lift; procedural volumes are increasing as providers standardize workflows around the platform; stay aggressive on placements to lock in lifetime service and consumable revenue.
Real-time motion management and adaptive planning are high-growth clinical priorities, with adaptive radiotherapy adoption rising over 25% year-over-year in advanced centers in 2024. Accuray’s precision positioning and tracking map directly to that demand, but scaling requires meaningful R&D spend and prospective evidence generation. As adoption scales, these capabilities shift from differentiators to baseline expectations. Invest now to cement category leadership.
Global SRS/SBRT expansion is driving shorter, targeted treatments that cut costs and time-to-care, shifting regimens from roughly 20–30 fractions to 1–5 fractions; Accuray is well positioned with platforms engineered for hypofractionation. The market is rapidly expanding and competitively noisy—sustain market-access funding and clinician education to win protocols and volume.
Published outcomes and marquee centers underpin Accuray’s premium positioning; in 2024 a sustained evidence cadence from trials, registries and intensive KOL training creates a growth flywheel but costs tens of millions annually.
CyberKnife and Radixact/TomoTherapy are Stars: combined installed base >2,000 systems worldwide in 2024 with ~25% YoY procedural growth in advanced centers; precision motion management and hypofractionation drive premium pricing and consumable pull-through. Continued R&D and evidence spend (~$20–40M/yr) required to sustain leadership and convert to durable cash cows.
| Metric | 2024 |
|---|---|
| Installed base | >2,000 systems |
| YoY growth (advanced centers) | ~25% |
| Annual evidence/R&D spend | $20–40M |
 Detailed Word Document
Concise BCG review of Accuray products: Stars, Cash Cows, Question Marks, Dogs with invest, hold or divest guidance plus trend context.

 Customizable Excel Spreadsheet
One-page BCG view to spot cash cows, stars and fix resource drain — quick clarity for smarter decisions
Large installed base of over 2,000 systems worldwide in 2024 drives reliable, high-margin recurring revenue from service and maintenance contracts. Growth is modest and churn remains low when uptime is strong, with service stabilizing cash flows even as device sales fluctuate. Optimizing field operations and parts logistics can widen margins, so milk this cash cow while maintaining high customer satisfaction to preserve renewal rates.
Software upgrades and options at Accuray (NASDAQ: ARAY) generate steady, low-friction recurring cash: attach motions are mature with reported service- and software-driven margins typically higher than hardware, supporting ARPU expansion. 2024 focus on feature unlocks and periodic upgrades sustained predictable revenue cadence in enterprise accounts. Bundle thoughtfully to raise ARPU without discounting core systems, keeping upgrade attach rates high. Maintain cadence and resist overselling complexity to preserve renewal rates and margin profile.
Consumables and accessories are small-ticket, repeat purchases directly tied to machine utilization and patient throughput, delivering steady per-case revenue for Accuray. Market growth in 2024 remained mild, at low single-digit rates, but usage is highly predictable based on installed base and throughput. Tightening supply chain and disciplined pricing protect contribution margins on these high-frequency items, making them simple, boring, and reliably profitable.
In 2024, replacement activity remained concentrated in North America and Western Europe, delivering steady demand despite low market growth. Win rates are high with existing Accuray customers, so focus on ROI-driven fleet refresh proposals to convert installed-base opportunities. Maintain tight cost control to preserve margins while defending share in mature markets.
Training, certification, and support at Accuray act as sticky add-ons that reinforce platform preference; scalable digital delivery pushes incremental margins substantially in 2024, turning these services into steady cash flow that defends the installed base and covers operating costs rather than driving hypergrowth.
Installed base >2,000 systems (2024) drives majority recurring revenue; service/software margins exceed hardware; market growth ~3% (2024); replace demand concentrated in NA/WE with high win rates.
| Metric | 2024 |
|---|---|
| Installed base | >2,000 |
| Market growth | ~3% |
| Recurring rev | Majority |
| Regions | NA, WE |
The file you’re previewing here is the exact BCG Matrix document you’ll receive after purchase—no watermarks, no placeholders, just the finished, fully formatted report. It’s built for strategic clarity and crafted by experts, so you can drop it straight into planning sessions or investor decks. After buying, the full file is instantly downloadable and editable. No surprises—just a ready-to-use analysis report.
Legacy TomoTherapy variants carry higher support costs and limited upgrade paths, tying up cash in maintenance rather than revenue-generating upgrades. With customers modernizing, these systems show low growth and a shrinking share as vendors and hospitals shift spend to MR-Linac and VMAT solutions. Industry data places the 2024 global radiotherapy market near $6.2B, underscoring where future investment flows. Prioritize trade-ins or formal sunset plans to stop the bleed.
Price-driven tenders with thin margins have pushed certain Accuray deals into a race-to-the-bottom, eroding service economics and brand positioning; historically these opportunities show low share and low growth (market growth ~3% in 2024) with limited lifetime value. What looks like revenue often acts like a trap—margins compress, aftermarket upsell fades, and churn rises. Walk away unless the bid secures a clear strategic beachhead.
Great clinical stories for niche indications often represent under 5% of total addressable radiotherapy cases in 2024. Sales cycles run long, typically 12–24 months, and reported utilization for these niches stays low, around 5–15%. Resources and capital become tied up with minimal return, reducing ROI versus core indications. Deprioritize and fold into broader protocols to reallocate spend.
Challenged geographies suffer low access, slow approvals (often >24 months) and limited public healthcare budgets, keeping Accuray market share small and stagnant in these regions. Turnarounds require heavy CAPEX and commercial spend with uncertain payoff versus mature markets. Trim exposure or pursue partner-light pilots to test demand before larger commitments.
Retire legacy radiotherapy platforms, stop cash drain, trade in for growth
Legacy TomoTherapy and low-use software/modules are low-share, low-growth Dogs: 2024 radiotherapy market ~$6.2B with ~3% growth, niche cases <5% TAM and 5–15% utilization, and slow approvals >24 months in challenged geographies. High service costs and thin-margin tenders compress ROI and tie capital. Prioritize retirements, trade-ins, partner-light pilots to stop cash bleed.
| Metric | 2024 Value | Action |
|---|---|---|
| Market size | $6.2B | Reallocate to growth segments |
| Growth rate | ~3% | Halt investment |
| Niche share | <5% | Deprioritize |
| Utilization | 5–15% | Retire/bundle |
Emerging markets show strong oncology demand yet remain early-stage for radiotherapy adoption; WHO reports about 70% of cancer deaths occur in low- and middle-income countries and IARC projects about 28.4 million new cancer cases by 2040, underscoring growth potential. Success requires distributor depth, local financing and real-world evidence; near-term investments are cash-hungry but unlocking access can convert this quadrant into a Star.
AI-driven planning and workflow is a Question Mark for Accuray: rapid interest but low current penetration in clinical sites, requiring investment in validation, system integrations and regulatory clearances. Early studies show AI can slash planning time by up to 70% and lift throughput 30–50%, with several radiotherapy AI tools receiving FDA clearances in 2023–24. Back it decisively to capture upside or skip to partnerships to limit burn.
Outpatient/ambulatory oncology centers sit in Question Marks as the shift to lower-cost sites is real, with 2024 industry reports showing outpatient radiotherapy adoption rising and capital-plus-operating costs often 25–35% below hospital-based care, but the market playbook isn’t finished. Financing and compact deployment models (modular vaults, moveable units) are critical to de-risk rollouts. Early wins at reference clinics can set network standards; push targeted service bundles and rigorously test whether unit economics—break-even volumes, yield per treatment—hold before scaling.
New indications and protocols show promising clinical pilots beyond traditional tumor sites (e.g., pancreas, liver, oligometastatic disease), but adoption hinges on robust evidence, reimbursement coding, and guideline inclusion; this is a spend-now, returns-later Question Mark—invest selectively and scale if outcomes and billing align; kill fast if reimbursement or guideline endorsement lags.
Open ecosystems can accelerate Accuray adoption but current share remains limited; FY2024 revenue was $345.4M with ~1,900 installed systems, underscoring runway but small clinical-share penetration. Strategic partnerships require engineering bandwidth and tight go-to-market alignment; if partners embed Accuray into standard workflows upside could be material, but careful bet selection is needed to avoid dilution of core tech and margin.
Question Marks: emerging markets, AI planning, outpatient shift and new indications show high upside but require heavy validation, financing and reimbursement wins to become Stars.
FY2024 revenue $345.4M; ~1,900 installs; 70% cancer deaths in LMICs; 28.4M cases by 2040.
AI pilots report up to 70% planning time cut and 30–50% throughput lift; partner bets reduce burn.
| Metric | Value |
|---|---|
| FY2024 Revenue | $345.4M |
| Installs | ~1,900 |
| AI impact | -70% time, +30–50% throughput |


