
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Adastria combines a strong multi-brand retail portfolio and efficient supply chain with deep Japan-market penetration, but faces domestic concentration and margin pressure from fast-fashion competitors. Opportunities in omnichannel expansion, sustainability and selective overseas growth could drive upside, while macro slowdown and rising costs pose real risks. Purchase the full SWOT for a research-backed, editable Word and Excel package to strategize and invest confidently.
Diversified multi-brand portfolio—operating over 25 brands across apparel, accessories and home goods—cuts reliance on any single label, enabling targeting of multiple demographics and price tiers; with roughly 1,900 stores and consolidated revenue of ¥236.8 billion in FY2024, this mix buffers demand volatility and seasonality and lets Adastria exit underperforming concepts quickly without jeopardizing the whole business.
Adastria leverages an omnichannel footprint with over 1,300 physical stores plus a growing e-commerce platform, boosting customer access and convenience. Click-and-collect, ship-from-store and unified inventory have raised sell-through rates and shortened fulfillment times. Omnichannel data feeds drive sharper merchandising decisions and personalized offers. Scale enhances bargaining power with suppliers and landlords, supporting margin resilience.
Adastria's design-to-retail SPA model keeps design, sourcing and retail in-house, enabling trend response in weeks rather than months and shortening lead times to limit markdown risk. Vertical integration reduces intermediaries and supports healthier gross margins across its portfolio. Shorter cycles and direct feedback from over its store and online channels accelerate product iteration and assortment adjustments.
Adastria's broad price architecture, spanning value to premium, widens the addressable market and attracts value-conscious shoppers while retaining fashion-forward consumers. This mix supports traffic resilience in down cycles and enabled the group to maintain stable traffic during recent retail softening. It also facilitates trade-up and cross-selling across its multi-brand network of over 1,000 stores in Japan and Asia.
Adastria's strong domestic presence in Japan, with over 1,000 stores nationwide, reinforces trust and repeat purchases by offering locally tailored assortments and optimal site selection based on deep market knowledge. Its loyalty programs, with millions of enrollees, boost retention and basket size. Strong word-of-mouth and social proof lower customer acquisition costs and improve marketing ROI.
Diversified 25+ brand portfolio with ~1,900 stores and FY2024 revenue ¥236.8 billion reduces single-label risk and enables rapid portfolio optimization. Omnichannel reach (1,300+ stores integrated with e-commerce) improves fulfillment, sell-through and supplier bargaining. SPA vertical model and millions-strong loyalty base shorten lead times, cut markdowns and raise retention.
| Metric | Value |
|---|---|
| Brands | 25+ |
| Stores (total) | ~1,900 |
| FY2024 Revenue | ¥236.8bn |
| Loyalty members | millions |
 Detailed Word Document
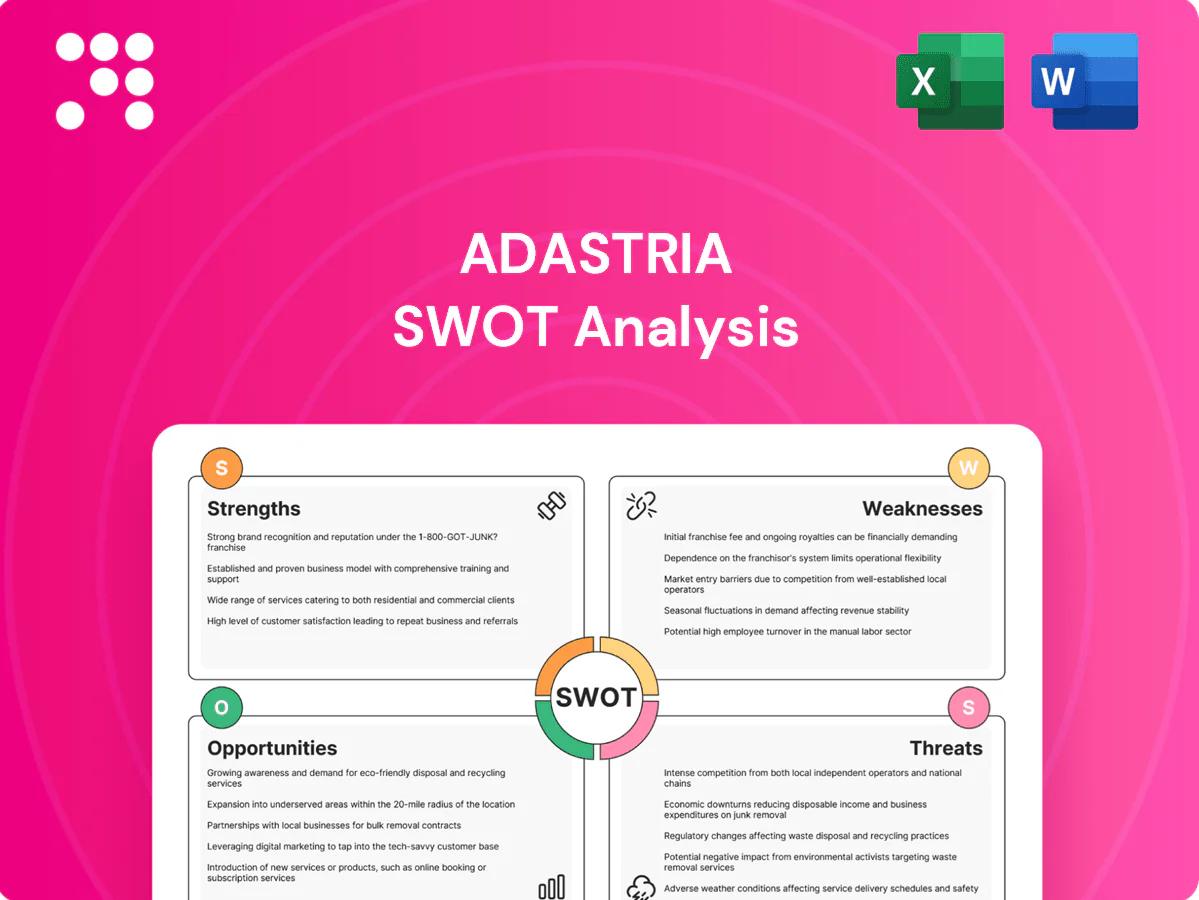
Provides a concise SWOT assessment of Adastria, highlighting internal strengths and weaknesses alongside external opportunities and threats that shape its competitive position and growth prospects.

 Customizable Excel Spreadsheet
Provides a focused SWOT summary of Adastria for rapid strategic alignment and stakeholder briefs, streamlining communication of risks and opportunities; editable format enables quick updates to reflect market shifts and changing priorities.
High domestic market concentration leaves Adastria heavily exposed to Japanese macro and demographic headwinds, with over 80% of revenue generated in Japan (FY2024), amplifying sensitivity to local GDP and population decline. Limited international diversification raises volatility and limits upside versus global peers. Tourist flows (≈32 million inbound in 2023) and domestic consumption cycles can swing sales. Geographic concentration caps growth optionality.
Style misses can force Adastria into rapid markdowns and margin compression, as short product lifecycles raise execution risk and shorten time to sell through. Fast-moving micro-trends make demand forecasting more complex, increasing inventory volatility and stockouts or excesses. If assortments lag consumer tastes, brand equity can erode quickly, weakening customer loyalty and price power.
Seasonal SKUs require tight inventory control to avoid obsolescence, and Adastria's broad brand portfolio increases SKU complexity. Excess stock often forces markdowns and promotions that dilute brand value. High holding costs and periodic write-downs strain cash flow. Accurate allocation across stores and online channels is operationally demanding and raises logistics and forecasting costs.
Competing between value and premium segments squeezes Adastria’s pricing power, with shoppers rapidly comparing offers between fast fashion, DTC brands and in-store assortments; Adastria reported approximately ¥260bn in net sales in FY2023, exposing scale but limited margin tailwinds. Rising input and labor costs in 2024–25 have been hard to fully pass through, while promotional norms train customers to wait for discounts.
Complex brand portfolio—Adastria runs over 30 labels across 1,000+ retail points, raising overlap and cannibalization risks, while fragmented marketing budgets dilute ROI and consistent positioning; governance across many brands slows decisions and undermines loyalty.
High Japan concentration (≈80% revenue FY2024) and limited international sales amplify exposure to GDP and demographic decline; net sales ≈¥260bn (FY2023). Fast-fashion volatility forces markdowns, raising inventory costs and margin pressure amid rising input/labor costs in 2024–25. Complex portfolio (30+ labels, 1,000+ stores) increases cannibalization and governance friction.
| Metric | Value |
|---|---|
| Japan revenue share FY2024 | ≈80% |
| Net sales FY2023 | ¥260bn |
| Inbound tourists 2023 | ≈32m |
| Brands / stores | 30+ / 1,000+ |
This is the actual Adastria SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report you'll get, and the complete, editable version becomes available after checkout.
Expanding DTC and third-party marketplaces can unlock incremental reach for Adastria as global e-commerce exceeded $5.7 trillion in 2022 and Japan’s online retail penetration near 10% indicates runway for apparel growth. Improving UX, mobile and fulfillment raises conversion and NPS. Unified commerce and endless-aisle increase basket size. Cross-border e-commerce enables low‑cost market testing.
Neighboring markets such as Greater China, South Korea and Taiwan share similar fashion sensibilities and tap into an Asia-Pacific apparel market that exceeded 50% of global apparel value in 2024, offering clear growth potential. Partner models and franchising lower capital intensity and speed market entry while preserving margins. Flagship stores in key cities create brand heat and localized assortments plus designer collaborations accelerate adoption.
Advanced demand forecasting using ML can cut stock-outs and markdowns by up to 25–30%, lowering inventory costs and protecting gross margin. Personalization programs commonly raise repeat purchase rates ~20% and AOV 10–15%, boosting customer LTV. Dynamic pricing and allocation driven by real-time data typically lift margins 1–5% in retail pilots. Data-driven product development shortens time-to-fit and raises SKU success rates, improving sell-through.
Adastria can differentiate through responsible sourcing and traceability, turning supply-chain transparency into a competitive edge in a crowded retail market; repair, resale, and recycling programs will attract growing eco-conscious cohorts and extend customer lifetime value. Lower-impact materials help hedge emerging regulatory and compliance costs, while clear ESG storytelling enhances brand equity and investor appeal.
Expanding into home goods and lifestyle accessories diversifies Adastria beyond apparel, smoothing seasonality and improving store productivity through broader basket mix. Bundling and gifting lift attach rates and average transaction value, while scaling private-label home items supports margin accretion and supply-chain control. This shift leverages existing store footprint and omnichannel capabilities to raise per-store revenue.
Expand DTC/marketplaces as global e-commerce topped 6.4T USD in 2023 and Japan online penetration ~10%, unlocking apparel growth. Scale ML forecasting to cut markdowns 25–30% and personalization to raise repeat ~20% and AOV 10–15%. Enter Greater China/Korea/Taiwan via franchising to capture Asia-Pacific >50% of global apparel value (2024). Launch home/private‑label to smooth seasonality and boost margins.
| Opportunity | Impact | Metric |
|---|---|---|
| DTC & Marketplaces | Reach & revenue | e‑commerce 6.4T (2023) |
| ML & Personalization | Margins & LTV | Markdowns −25–30%, AOV +10–15% |
Global fast-fashion players and domestic giants such as Fast Retailing (¥3.1 trillion revenue FY2024) and Shimamura crowd the field alongside agile digital-native brands, intensifying price wars and raising markdown risk. Rapid trend cycles and social commerce — where platforms like TikTok now drive a growing share of discovery — shorten product windows and amplify inventory write-downs. Sustained differentiation demands continuous investment in design, supply chain and digital capabilities.
Macroeconomic slowdown and elevated inflation hit Adastria as weak consumer sentiment curbs discretionary apparel spend, with Japan household spending down intermittently through 2024. Consumer price inflation ran near 3% in 2024, squeezing margins if input-cost inflation cannot be passed to shoppers. Rising rent and labor costs—up mid-single digits in many urban markets—raise fixed costs. Yen weakness (USD/JPY ~140–155 in 2024) drives volatile imported input prices.
Factory shutdowns, logistics bottlenecks and port delays have extended lead times for apparel firms—often adding 6–12 weeks—harming Adastria’s inventory turns and seasonal timing. Quality and compliance lapses raise recall and reputational risks that can cost retailers millions per incident. Geopolitical tensions since 2022 have rerouted sourcing and increased landed costs, while concentration of suppliers in East Asia (over 60% industry sourcing) magnifies shock exposure.
Evolving labor, environmental and product-safety regulations raise compliance costs for Adastria, risking margin pressure and higher CAPEX to meet standards.
Heightened greenwashing scrutiny and stronger disclosure expectations increase investor and regulator oversight, while stricter data-privacy laws constrain digital marketing and CRM capabilities.
Non-compliance can lead to regulatory fines and reputational harm that reduce sales and shareholder value.
Growth of resale platforms diverts value-conscious consumers; the global resale market is projected to exceed $200 billion by 2026 (ThredUp/GlobalData 2024). Younger shoppers increasingly prioritize sustainability and uniqueness—65% of Gen Z cite sustainability as important to purchase decisions (IBM 2024). Rental and swapping models cut purchase frequency, so brands that fail to adapt risk losing relevance and market share.
Intense competition from Fast Retailing (¥3.1 trillion rev FY2024) and digital-native brands compresses prices and margins. Macroeconomic pressure—CPI ~3% in 2024, USD/JPY ~140–155—raises input and rent costs. Supply-chain shocks and East Asia sourcing concentration (>60%) increase volatility and inventory write-down risk. Resale growth (>$200B by 2026) and 65% Gen Z sustainability preference threaten repeat purchases.
| Metric | Value |
|---|---|
| Fast Retailing rev FY2024 | ¥3.1T |
| CPI Japan 2024 | ~3% |
| USD/JPY 2024 range | 140–155 |
| Sourcing concentration | >60% East Asia |
| Resale market | >$200B by 2026 |
| Gen Z sustainability | 65% |


