
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Aegon’s SWOT analysis highlights its diversified global footprint and strong pension expertise, balanced against regulatory pressures and market sensitivity to low yields. The report pinpoints growth levers like digital distribution and emerging markets while exposing capital and legacy-book risks. Want the full strategic view and ready-to-use tools? Purchase the complete SWOT analysis for a professional Word report and editable Excel model to plan, pitch, or invest with confidence.
Aegon operates across the Americas, Europe and Asia, with a presence in over 20 countries and serving roughly 30 million customers, providing diversified revenue streams and risk dispersion. Its established brand in life insurance, pensions and asset management boosts customer trust and distribution leverage. Scale grants negotiating power with partners and suppliers and supports growth in both mature and emerging markets.
Aegons diverse product portfolio—life insurance, retirement solutions and investment products—supports cross-selling and lifecycle retention, serving over 40 million customers and managing roughly EUR 300 billion in assets. Breadth helps balance cyclical demand shifts and margin pressure across business lines. It enables tailored solutions for individuals, families and businesses, reducing reliance on any single product line and smoothing revenue volatility.
Life and pension businesses require deep underwriting, longevity and asset-liability management; Aegon leverages decades of experience managing roughly €350–360 billion in assets to support prudent pricing and capital allocation. Its actuarial teams drive product design and reserving that reduce tail risks and capital strain. Robust risk frameworks and capital metrics (Solvency II ratio around 180% at YE2024) help stabilize earnings over the long term. This technical expertise forms a durable competitive moat in tightly regulated markets.
Aegon leverages agents, brokers, bancassurance and digital channels to reach varied customer segments across more than 20 markets, serving over 40 million customers. Multi-channel access improves acquisition efficiency and provides resilience when one channel underperforms. Partnerships with banks and brokers support scalable growth and deeper market penetration.
Holding asset management alongside insurance and pensions enhances ALM and helped Aegon leverage approximately €200bn AUM in 2024 to improve investment returns and lower third‑party fees.
Integrated investment capabilities enable product innovation and stronger annuity/retirement competitiveness, supporting better long‑term policyholder outcomes and margins.
Aegon’s diversified presence in 20+ markets serving 40m+ customers, integrated AUM ~€200bn (2024) and group assets ~€350–360bn underpin scale, cross‑sell and ALM advantages; strong technical capabilities and a Solvency II ratio ~180% (YE2024) support resilient earnings and competitive annuity pricing.
| Metric | Value |
|---|---|
| Markets | 20+ |
| Customers | 40m+ |
| Integrated AUM (2024) | ~€200bn |
| Group assets | ~€350–360bn |
| Solvency II (YE2024) | ~180% |
 Detailed Word Document
Provides a strategic SWOT overview of Aegon, highlighting internal strengths and weaknesses and external opportunities and threats shaping its insurance, pensions, and asset management businesses.

 Customizable Excel Spreadsheet
Provides a concise Aegon SWOT matrix for fast strategic alignment across insurance and asset-management lines, easing cross-functional decision-making and stakeholder communication.
Life insurance and pension liabilities are highly sensitive to rate movements, and Aegon reported a Solvency II ratio around 206% in 2024, highlighting balance‑sheet exposure. Prolonged low or volatile rates compress investment income and require higher technical provisions, pressuring reserve adequacy. Hedging programs reduce but do not eliminate earnings volatility, and capital requirements can spike in stressed rate scenarios.
Closed blocks and older policies tie up capital and add administrative complexity, with Aegon managing roughly €315 billion in assets (2024) where legacy books concentrate risk and cashflow drag.
Guaranteed benefits in older contracts have produced unfavorable economics, increasing hedging and capital costs and compressing margins relative to newer business.
Modernizing IT and migrating decades of policy data is slow and costly, and these legacy portfolios dilute group returns and ROE compared with growth segments.
Operating across four reporting segments—Americas, Netherlands, UK & Ireland, and Other Countries—increases regulatory, tax and operational burdens and creates heterogeneous compliance frameworks. Coordination across these business units can slow decision-making and rollout of products. Integration of platforms and processes remains resource-intensive, and this organizational complexity can push Aegon’s expense ratios higher versus leaner competitors.
Insurance brands often have strong localized recognition, and Aegon — operating in 20+ markets — faces limited global marketing synergies; in several regions it trails domestic incumbents in awareness, reducing cross-sell lift. Ensuring a consistent customer experience across diverse markets is operationally challenging and increases costs, which can impede rapid cross-border product leverage.
Asset management and unit-linked fees at Aegon are tied to market levels, so equity drawdowns and credit-spread widening directly depress fee income, earnings and AUM. Policyholder lapses and switches often increase in downturns, amplifying outflows and reserve volatility. This exposure adds marked cyclicality to quarterly and annual results.
Aegon’s balance sheet is rate‑sensitive (Solvency II ~206% in 2024) and €315bn AUM concentrates legacy cash‑flow drag. Guaranteed benefits and closed books raise hedging and capital costs, squeezing margins and ROE. Fragmented brands across 20+ markets and fee income cyclicality amplify operational and earnings volatility.
| Metric | 2024 |
|---|---|
| Solvency II | ~206% |
| AUM/assets | €315bn |
| Markets | 20+ |
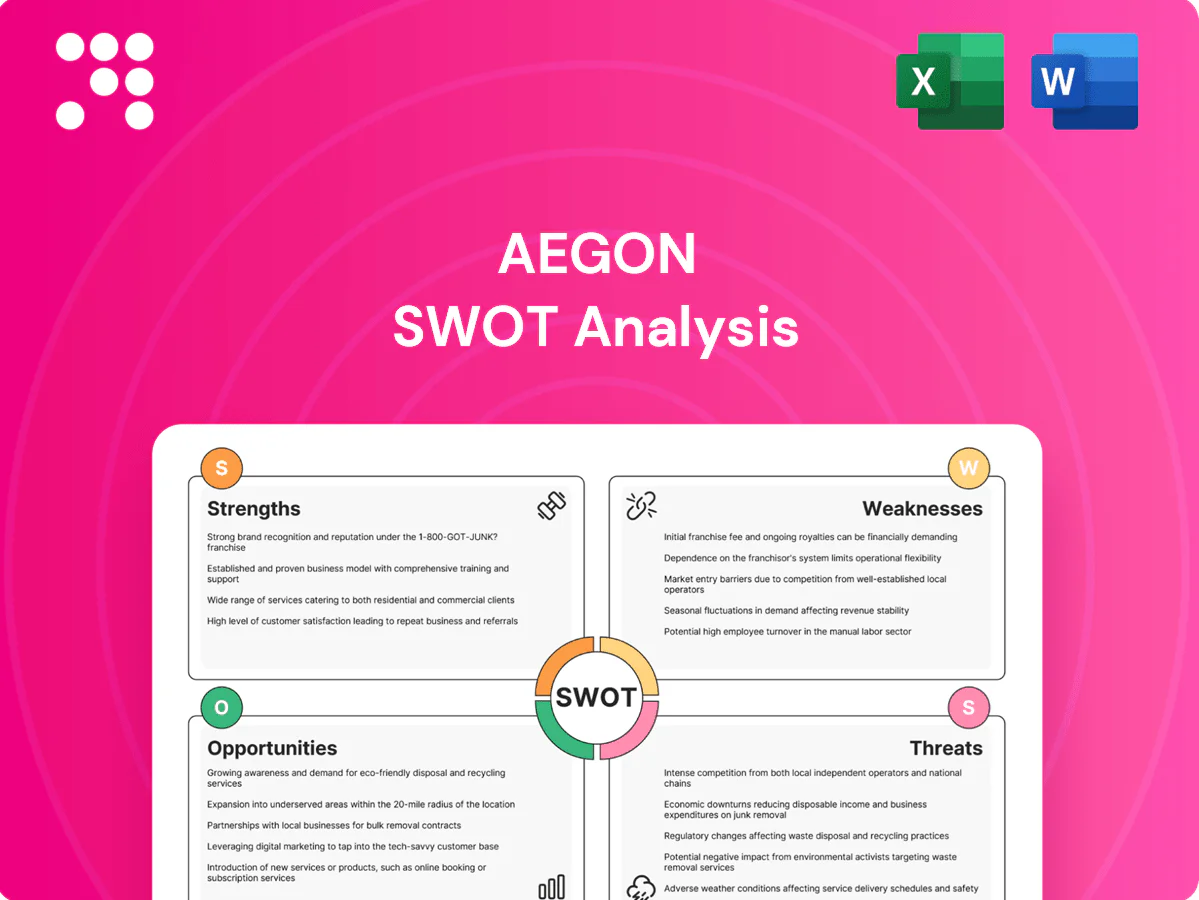
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. It outlines Aegon's strengths, weaknesses, opportunities and threats with concise insights and actionable implications for investors and strategists. The preview below is taken directly from the full report you'll get; purchase unlocks the editable, complete file.
Demographic tailwinds—UN projects 65+ population to reach ~1.5 billion by 2050—boost demand for pensions, annuities and decumulation solutions; many OECD markets are shifting risks to private providers via DC reforms and reduced public pillars; Aegon can scale advisory-led retirement planning and guaranteed-income products and use education and digital tools to deepen engagement and retention.
Modernizing underwriting, claims and servicing cuts costs and speeds delivery, supporting Aegon’s targets to boost efficiency; Aegon reported digital sales of 28% in 2024, underlining progress. Data analytics refine pricing and lapse management, lowering lapse rates and improving margins. Digital distribution expands reach to younger, self-directed customers while straight-through processing (STP) raises satisfaction and retention by automating end-to-end flows.
Rising ESG interest, with Bloomberg Intelligence projecting sustainable assets to reach about 53 trillion USD by 2025, allows Aegon to differentiate asset management offerings and expand fee pools.
Green and impact-linked insurance and pension solutions can attract new client segments seeking net-zero-aligned products, boosting retention and sales.
Deep ESG integration strengthens risk management and brand value, while partnerships with fintechs and asset managers can accelerate product innovation and time-to-market.
Alliances with banks, fintechs and employers accelerate Aegon’s customer acquisition, leveraging its network of over 40 million customers and existing distribution; bancassurance can account for up to 40% of life premiums in some European markets, boosting scale quickly. Embedded insurance in retirement and payroll ecosystems enables rapid uptake; co-branded solutions raise trust and conversion, while consented data-sharing refines targeting and pricing.
Selling or reinsuring legacy blocks can free capital to fund growth in pensions, protection and asset management; repricing and product redesign improve risk-return and margins; focused deployment into higher-ROE markets boosts profitability while simplification reduces operating expenses and earnings volatility.
Demographic shift to ~1.5bn 65+ by 2050 boosts demand for pensions/annuities; DC reforms shift risk to private providers. Digital sales 28% in 2024 enable scale of advisory-led, STP and analytics-driven retention. Sustainable assets ~USD53trn by 2025 and 40m+ Aegon customers support ESG product growth and bancassurance-led distribution.
| Opportunity | Impact metric | 2024/25 datapoint |
|---|---|---|
| Demographics | Demand | 65+ ~1.5bn by 2050 |
| Digital scale | Sales share | Digital sales 28% (2024) |
| ESG | Asset pool | USD53trn sustainable (2025) |
| Distribution | Customers | 40m+ Aegon; bancassurance up to 40% |
Adjustments to solvency rules and accounting standards can materially change Aegons capital requirements and reported earnings, forcing capital reallocations. Compliance costs across jurisdictions have risen, pressuring margins and operating budgets. Product features and guarantees may need redesign under new rules, increasing IT and actuarial spend. Regulatory uncertainty can delay strategic investments and M&A timing.
Recession, inflation spikes or rapid rate shifts—with US policy rates near 5.25–5.50% and IMF 2024 world growth ~3.1%—can strain Aegon’s liabilities and assets, triggering credit losses and market drawdowns that erode capital buffers and fee income; policyholder lapses often rise under stress, and hedges can fail in extreme scenarios, exposing balance-sheet volatility and solvency pressure.
Aegon faces intensifying competition from global insurers, nimble insurtechs and asset managers — insurtech funding was $8.5bn in 2023, keeping digital entrants active. Price-driven markets and lower investment returns compressed margins, with industry ROE near 8% in 2024. Sustained differentiation requires continuous product and service innovation while distribution partners increasingly seek higher commissions.
Financial institutions are prime targets for cyberattacks; the 2024 IBM Cost of a Data Breach Report shows the industry average breach cost at about $5.97 million versus a $4.45 million global average, exposing Aegon to significant financial loss, operational disruption and reputational damage. Tightening global data privacy rules increase compliance risk and potential fines, making continuous, costly security investments mandatory.
Unexpected shifts in life expectancy can invalidate pricing assumptions; WHO estimated 14.9 million excess deaths globally in 2020–21, highlighting pandemic risk, while noncommunicable diseases account for about 74% of global deaths, raising morbidity uncertainty. Reinsurance costs have trended up post‑pandemic and IFRS 17 reserve strengthening since 2023 can materially pressure earnings and capital.
Regulatory/accounting shifts (IFRS 17 since 2023) raise capital needs and compliance spend, delaying M&A. Macro shocks—IMF 2024 world growth 3.1%, US rates ~5.25–5.50%—threaten asset values, lapses and hedges. Competition from insurtechs (2023 funding $8.5bn) and cyber risk (avg breach cost $5.97M, IBM 2024) compress margins.
| Threat | Key metric |
|---|---|
| Regulation | IFRS 17 reserve builds |
| Macro | World GDP 3.1% (IMF 2024) |
| Cyber/Insurtech | $5.97M breach; $8.5bn funding |


