
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
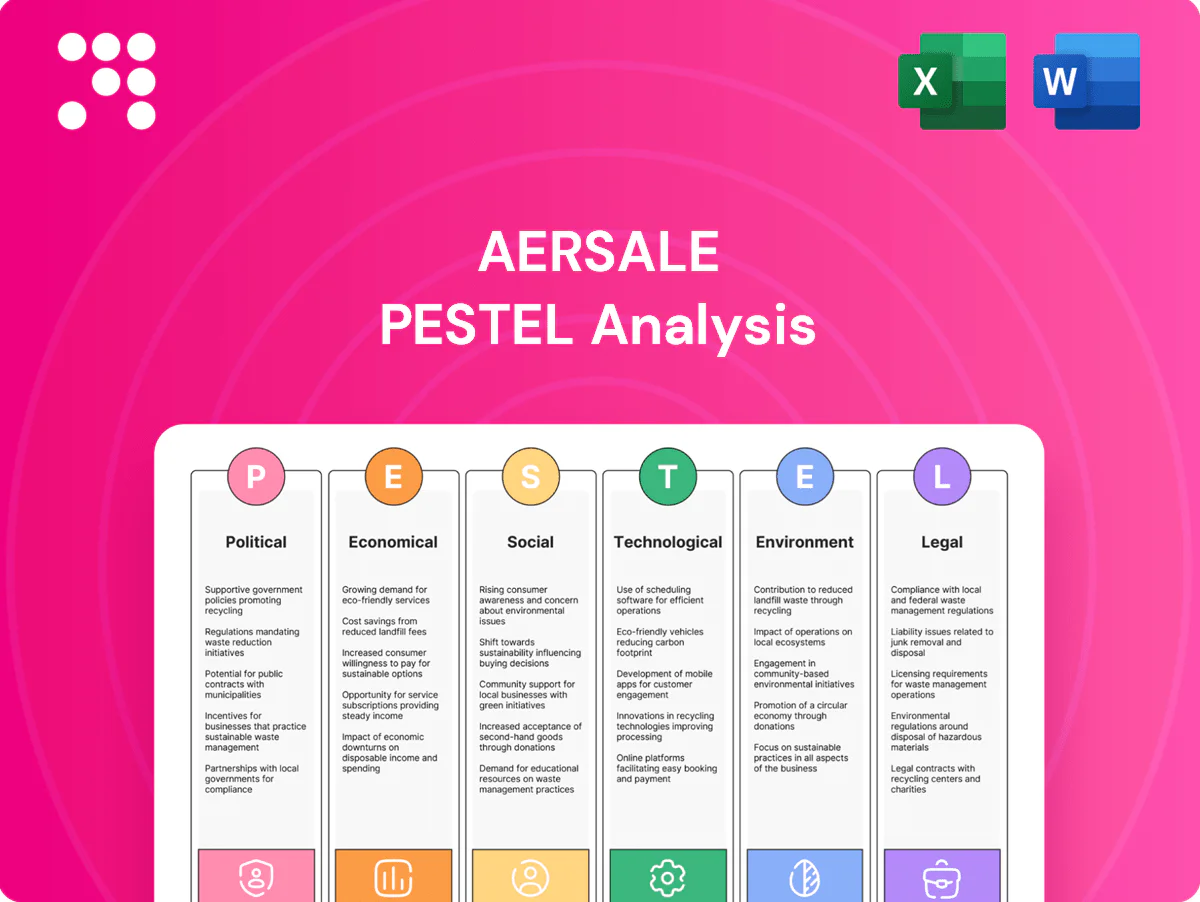
Gain a strategic edge with our PESTLE Analysis of AerSale—spot political, economic, and regulatory drivers shaping its growth and risk. Ideal for investors, consultants, and executives, it translates global trends into actionable strategy. Buy the full, ready-to-use report now for an instant, editable deep-dive you can deploy in decisions and presentations.
Transacting used aircraft and engines crosses multiple jurisdictions subject to ITAR/EAR and OFAC regimes, complicating cross-border sales. Sanctions can instantly restrict customers, routes and spare-part flows, impacting access to parts in the global MRO market (roughly $95B in 2024). OFAC/BIS enforcement has produced multi-million-dollar penalties and shipment detentions, so AerSale must maintain robust screening and documentation. Diversifying suppliers and end-markets reduces geopolitical chokepoint risk.
Geopolitical conflicts reroute corridors and shift utilization, cutting flying and raising teardown/parts demand while rebounds push AerSale’s MRO throughput; IATA reported 2024 global passenger traffic roughly returned to pre‑pandemic levels, intensifying cyclical swings. AerSale’s teardown/parts network and global facilities enable capacity reallocation but abrupt airspace closures strain logistics; scenario planning reduces volatility.
Tariffs on aerospace inputs — notably U.S. steel at 25% and aluminum at 10% under Section 232 — raise AerSale’s component costs and can distort sourcing and teardown economics. Rapid shifts in trade deals and regional tariffs can advantange or penalize MRO hubs across North America, Europe and Asia. Mitigations like bonded warehouses and U.S. foreign-trade zones allow duty deferral/avoidance, while flexible pricing and contract clauses are needed to pass through tariff shocks.
Government aviation policy and infrastructure—airport privatizations, slot reforms and airspace modernization—directly shape AerSale’s fleet deployment and maintenance timing; global MRO demand was roughly 95 billion USD in 2024, underpinning storage and shop utilization. Public investment in regional airports increases local storage and MRO needs, while cargo-hub support has driven higher freighter conversions and parts demand. AerSale should align capacity to policy-driven traffic shifts and hub growth.
Government-backed airlines and defense fleets shape secondary-market asset availability; US FY2024 defense spending was about 858 billion USD, driving select retirements and parts releases that benefit teardown specialists like AerSale.
Retirements driven by public budgets often release frames and parts for teardown; state procurement cycles in 2024–25 increased supply of 50+ narrowbodies from military and flag-carrier retirements.
Preferential sourcing and offset rules can restrict award eligibility, so building compliance-readiness and domestic-content documentation enhances participation in state tenders.
Cross-border ITAR/EAR/OFAC regimes and sanctions create compliance risk for AerSale, affecting parts flows within a $95B MRO market (2024). Geopolitical reroutes boost teardown demand as passenger traffic returned to near‑pre‑pandemic levels in 2024. Tariffs (US steel 25%, aluminum 10%) and US FY2024 defense spending ~$858B drive costs and asset supply (50+ narrowbodies 2024–25).
| Tag | Figure | Implication |
|---|---|---|
| MRO market | $95B (2024) | Core demand |
| Defense budget | $858B (FY2024) | Asset supply |
| Tariffs | Steel 25%/Al 10% | Input cost |
 Detailed Word Document
Explores how macro-environmental factors uniquely affect AerSale across Political, Economic, Social, Technological, Environmental, and Legal dimensions, with data-backed trends, industry-specific examples, forward-looking insights, and actionable implications for executives, investors, and strategists.

 Customizable Excel Spreadsheet
A concise, PESTLE-segmented summary of AerSale's external risks and opportunities, easily dropped into presentations or shared across teams, editable for region- or business-specific notes and ideal for strategy and planning sessions.
Airline cash flows directly drive spending on MRO, leases and component exchanges, with IATA reporting global RPKs recovered to about 98% of 2019 levels in 2024, tightening airline budgets in downturns and expanding activity in upcycles. Downturns push deferrals and cannibalization of fleets, while upturns increase heavy checks and leasing demand. AerSale benefits from counter-cyclical teardown sales plus cyclical MRO revenues. A balanced services‑asset mix smooths topline volatility.
Rising policy rates (US federal funds ~5.25% mid-2025) lift lease yields but exert downward pressure on aircraft values and transaction volumes, often by double-digit percentage moves in past rate cycles. Airlines shift toward used aircraft versus new deliveries when credit tightens. AerSale’s cost of capital directly affects inventory holding and conversion project timing. Hedging and flexible lease structures can smooth ROI across rate cycles.
When Brent crude averaged about $83 per barrel in 2024, higher fuel costs accelerated retirements of fuel-inefficient aircraft and raised demand for performance upgrades, while episodes of cheaper jet fuel through early 2025 helped extend older fleets and supported used-part sales and MRO revenue. AerSale can pivot between teardown supply and modification packages as fuel economics shift, with engine shop activity closely tracking these dynamics.
Rising skilled technician wages and parts inflation squeeze AerSale's MRO gross margins, while prolonged OEM lead times and production backlogs through 2024 have elevated the value and demand for serviceable used material.
Strategic inventory holdings and supplier partnerships act as margin defenses, and pricing models must incorporate cost-pass-throughs and indexation to reflect volatile input costs.
USD strength, supported by U.S. policy rates at 5.25–5.50% in 2024–2025, reduces non-U.S. customer affordability and raises costs for dollar-priced part sourcing; AerSale faces exposure when assets are USD-denominated but revenues are local-currency. Natural hedges and formal FX policies have cut earnings volatility historically, while regional pricing adjustments help preserve competitiveness.
Airline cash flows (IATA RPKs ~98% of 2019 in 2024) drive MRO, lease and teardown demand; AerSale benefits from counter‑cyclical teardown sales and cyclical MRO. Fed funds ~5.25–5.50% (2024–mid‑2025) lifts lease yields but pressures asset values; Brent ~$83/bbl (2024) shifts retirements and upgrade demand. USD strength (DXY ~104 mid‑2025) raises local‑currency affordability risks.
| Metric | Value |
|---|---|
| IATA RPKs (2024) | ~98% of 2019 |
| Fed funds | 5.25–5.50% |
| Brent (2024) | $83/bbl |
| DXY (mid‑2025) | ~104 |
The preview shown here is the exact AerSale PESTLE Analysis document you’ll receive after purchase—fully formatted and ready to use. The content, structure, and professional layout in this screenshot match the downloadable file with no placeholders or surprises. After checkout you’ll instantly get this same final report for immediate use.
Tourism and business travel trends drive aircraft utilization and maintenance cycles; IATA reported 2024 global passenger demand at about 96% of 2019 RPKs, shortening maintenance intervals for high-rotation aircraft. Structural shifts toward leisure and short-haul flights have increased demand for A320/A321 and regional parts, reshaping fleet mix and teardown priorities. AerSale can align teardown inventory to high-rotation fleets and monitor route patterns to refine parts forecasting and reduce AOG risk.
Trust in certified serviceable material underpins the exchange market; AerSale’s FAA and EASA approvals and rigorous traceability systems reduce stigma around used parts. Their documented inspections, OEM-forming and dual-release paperwork provide verifiable quality assurance. Clear service histories enable customers to pay premiums for reliability and reduce lifecycle costs.
Workforce aging constrains MRO capacity: industry surveys (Aviation Week 2024) show median AMT age >48 with roughly one-third eligible to retire within 5–10 years, shrinking experienced technician pools. Recruiting, apprenticeships and upskilling are critical to preserve throughput and TAT. Automation (robotics, predictive maintenance) can augment scarce technicians but needs change management and capital. AerSale must invest in retention programs to meet contractual TAT commitments.
Stakeholders favor lifecycle sustainability, reuse and responsible teardowns; IATA reports aircraft recyclability near 85% by weight. Demonstrating material recovery rates and waste minimization strengthens AerSale's brand and influences 2024–25 procurement decisions. AerSale's parts-redistribution model benefits directly from circular-economy narratives.
Emerging-market fleet growth concentrates storage and MRO demand in Asia-Pacific and the Middle East, with Boeing 2024 CMO estimating Asia-Pacific will account for about 40% of global aircraft demand over the next 20 years. Cultural and regulatory norms there raise higher expectations for local customer service and compliance. AerSale can co-locate parts, storage and MRO near fast-growing fleets to cut ferry times and costs. Localization shortens turnarounds and strengthens operator relationships.
Demand recovery (~96% of 2019 RPKs, IATA 2024) and leisure/short‑haul shifts boost A320/A321 parts demand; trust in certified used parts (FAA/EASA approvals) supports premium pricing. AMT median age >48 (Aviation Week 2024) squeezes MRO capacity; upskilling and automation are needed. 85% recyclability (IATA) and Asia‑Pacific ~40% 20‑yr demand (Boeing 2024 CMO) favor localized circular supply chains.
| Metric | 2024/25 Value |
|---|---|
| Global RPKs vs 2019 | ~96% (IATA 2024) |
| AMT median age | >48 (Aviation Week 2024) |
| Recyclability | ~85% (IATA) |
| APAC 20‑yr demand | ~40% (Boeing 2024 CMO) |
Sensor data and continuous health monitoring let AerSale optimize part replacements and shop visits, shifting work from unscheduled to planned events and lowering costs tied to AOG, which industry estimates at $100,000–$1,000,000 per day. Integration with airline maintenance systems can lock in recurring MRO work through automated workflows and service agreements. Analytics-driven inventory positioning and data partnerships improve component availability and materially reduce AOG response times.
FAA ADS-B Out mandate effective January 1, 2020 and ongoing ICAO CNS/ATM modernization programs are driving sustained demand for avionics modifications. Standardized STCs and retrofit kits shorten install cycles and lower AOG risk, accelerating program uptake. AerSale packages parts, engineering, certification and MRO capacity to capture retrofit contracts. Proactively aligning with upcoming mandates helps secure program backlog.
Composite structures and next-gen engines are reshaping repair techniques and tooling, requiring different bonded repairs and automated nondestructive inspection. LEAP fleet exceeds 20,000 engines and Pratt & Whitney GTF installations surpass 11,000, shifting aftermarket demand and PMA opportunities. AerSale should invest in capability development and certifications early. Right-timing teardowns preserves residual value and maximizes parts yield.
Immutable part histories via blockchain improve compliance and customer trust while enabling provable provenance for life-of-part records in 2024 implementations.
Smart tagging (RFID/NFC + DLT) streamlines receiving, picking and cert management, cutting manual reconciliation and error rates in deployed pilots.
AerSale can differentiate by offering end-to-end traceability solutions integrated with regulators and OEMs to reduce audit friction and accelerate approvals.
Sensor/analytics reduced AOG response time 25–60% and raised availability 5–12%; ADS-B/avionics retrofits plus LEAP/GTF spares create a $1.5–3.5B MRO retrofit TAM (2024). AR/XR/robotics lower training/errors/labor 25–35%; blockchain+RFID pilots cut cert reconciliation 40–60%.
| Tech | Impact | Metric | 2024 |
|---|---|---|---|
| Analytics | Less AOG | AOG RT ↓ | 25–60% |
| Retrofits | TAM | Market | $1.5–3.5B |
| AR/Robotics | Efficiency | Labor/training ↓ | 25–35% |
| Blockchain/RFID | Certs | Reconcile ↓ | 40–60% |
Safety and airworthiness compliance under FAA Part 145, Part 21 and equivalent EASA rules strictly governs AerSale operations; non-compliance can trigger civil penalties, aircraft grounding and severe reputational damage. AerSale must maintain a robust QMS, continuous audit readiness and disciplined documentation to meet regulator inspections. Continuous trained personnel and documented recurrent training programs are essential to sustain certification and operational continuity.
Asset sales and MRO services expose AerSale to warranty and indemnity claims tied to part performance and airworthiness; clear SLAs and limitation-of-liability clauses reduce litigation risk and clarify remedies. Aligning insurance—product liability, hull and liability, and errors & omissions—with contractual risk limits potential balance-sheet hits. Robust core-return and beyond-economical-repair clauses protect margins by capping repair and replacement obligations.
Producing PMA parts or DER repairs requires rigorous legal pathways and IP caution; the FAA recorded about 22,000 PMA approvals by 2024, underscoring regulatory complexity. AerSale reported approximately $713 million revenue in fiscal 2024, linking compliance to commercial risk and pricing power. OEM relationships and competition laws shape access and margins, and strict antitrust compliance prevents coordination among distributors to safeguard market participation.
Handling, storage, and teardown of hazardous aircraft materials are tightly regulated; OSHA penalties (adjusted annually) reached up to $169,000 for willful/egregious violations in 2024, increasing financial risk from incidents and shutdowns. AerSale must maintain containment, disposal, and spill-response protocols to limit liability and operational disruption. Regular third-party audits and site-level EHS compliance metrics reduce incident frequency and insurance costs.
Maintenance records and customer data are subject to privacy and security laws; a breach could disrupt MRO operations and generate regulatory liability — IBM's 2024 Cost of a Data Breach Report puts the global average cost at $4.45 million, while GDPR fines reach up to €20 million or 4% of global turnover.
FAA/EASA certification (Part 145/21) demands QMS, audits and recurrent training to avoid grounding and penalties. Contractual warranties, indemnities and aligned insurance limit litigation risk; AerSale FY2024 revenue ~$713M ties compliance to margins. OSHA willful max fine 2024 $169,000 and IBM 2024 breach cost $4.45M drive EHS and cyber controls.
| Factor | 2024 Metric | Impact |
|---|---|---|
| Revenue | $713M | Compliance affects margins |
| OSHA max fine | $169,000 | Operational shutdown risk |
| Data breach cost | $4.45M | Regulatory & financial loss |
| PMA approvals | ~22,000 | Regulatory complexity |
Emissions frameworks like CORSIA (carbon‑neutral growth from 2020 covering most participating international routes) and the EU ETS (carbon price averaged about €90/ton in 2024) raise airline compliance costs that accelerate fleet renewal and retrofit decisions. Demand for efficiency upgrades and lighter components grows; AerSale can sell mod packages improving fuel burn while aligning with carriers' decarbonization plans.
ICAO Annex 16 noise standards and national Stage/Chapter requirements drive demand for hushkits and accelerate retirement of older, noisier aircraft. Airports with strict night curfews (for example Heathrow and several U.S. and European hubs) constrain fleet deployment and shift MRO windows into daytime slots. AerSale can capture retrofit revenue by supplying certified noise-reduction solutions or sourcing teardown candidates. FAA and EASA certification of such solutions materially increases asset value.
Responsible disassembly and material recovery reduce waste and cost; AerSale monetizes metals and components through teardown operations, aligning with industry estimates of over 12,000 aircraft projected for retirement by 2030 which boost USM supply. Tracking recovery rates supports ESG claims and customer audits, while partnerships with certified recyclers strengthen regulatory compliance and chain-of-custody traceability.
SAF scaling shifts engine maintenance profiles and fuel-system component wear; with SAF still under 0.2% of global jet fuel supply in 2023 and IATA targeting 10% SAF by 2030, airlines may defer retirements awaiting fuel availability, changing the MRO mix AerSale serves. AerSale can advise on compatibility, supply upgrade kits and track OEM advisories (GE, Pratt & Whitney, Rolls‑Royce) to ensure safe operations.
Emissions regimes (EU ETS ~€90/t in 2024; CORSIA) and SAF targets (SAF <0.2% in 2023; IATA 10% by 2030) push airlines to retrofit and renew fleets, creating demand for AerSale mod kits and compatibility services. Noise standards and 12,000+ retirements by 2030 expand teardown and hushkit markets. Climate disasters (NOAA 2023: $81.6B) force site hardening and diversification.
| Metric | 2023/24 |
|---|---|
| EU ETS price | ~€90/t (2024) |
| SAF share | <0.2% (2023) |
| Retirements | 12,000+ by 2030 |
| US disasters | $81.6B (2023) |


