
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
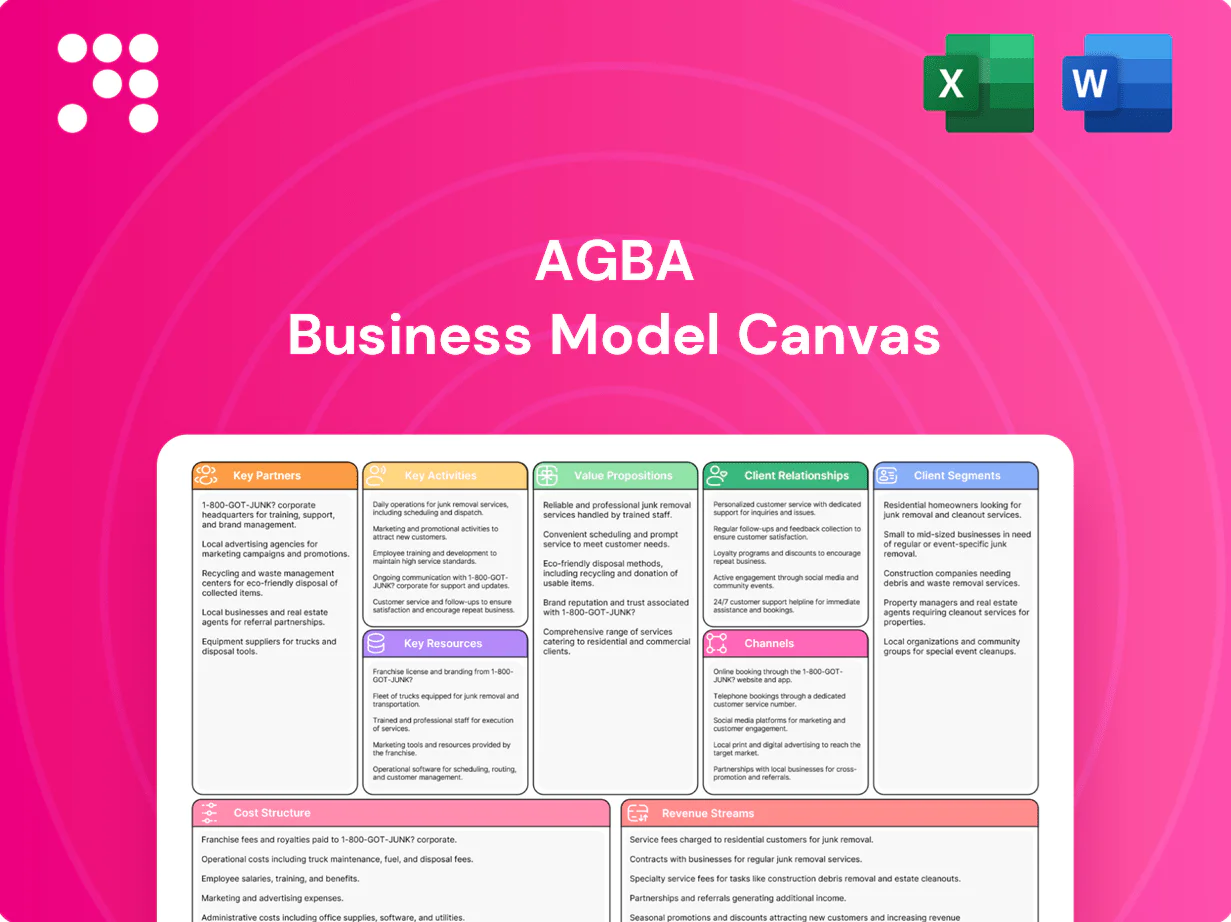
Unlock AGBA’s strategic blueprint with our concise Business Model Canvas that maps how the company creates and captures value. This downloadable canvas breaks down customer segments, value propositions, channels, partnerships, revenue streams and cost drivers for fast, actionable insight. Purchase the full editable Word/Excel file to benchmark, strategize, and present like a pro.
Partner with global and regional insurers and fund houses—many managing over US$120 trillion AUM in 2024—to broaden product shelves across life, health and investment solutions. Co-develop exclusive products tailored to Hong Kong and GBA clientele, tapping a GBA economy of roughly US$2.0 trillion (2024). Secure improved pricing, underwriting flexibility and dedicated marketing support to boost penetration and margins.
Integrate with 50+ banks and licensed payment gateways (2024) to enable seamless onboarding, instant funding and daily settlements, reducing time-to-fund by up to 70%. Co-marketing and referral agreements expand reach to retail and SME segments, targeting a combined addressable market of >20 million users. Leveraging established rails strengthens trust and ensures compliance with PSD2, AML/KYC and local settlement standards.
Tie-ups with hospitals, clinics, and telemedicine platforms embed on-demand care into AGBA insurance and wealth plans, leveraging a 2024 telemedicine market exceeding $90 billion to expand reach. Integrated wellness programs target chronic drivers—noncommunicable diseases cause 74% of deaths globally (WHO)—reducing claims and boosting retention. Consented health-data sharing enables data-driven care pathways and personalized preventive interventions.
Collaborate with regtech, AI, and analytics vendors to strengthen KYC/AML, risk scoring, and personalization; by 2024 roughly 75% of banks reported active API or open-finance initiatives, enabling unified client profiles and data-driven advice.
Maintain proactive engagement with Hong Kong regulators and industry associations to ensure compliance and help shape standards; participate in regulatory sandboxes for new digital offerings to iterate quickly; building credibility with bodies like the HKMA—which had 8 licensed virtual banks in Hong Kong as of 2024—reduces friction for product launches.
Partner global/regional insurers and fund houses (over US$120T AUM in 2024) to co-develop GBA-tailored life, health and wealth solutions for a GBA economy of ~US$2.0T. Integrate 50+ banks/payment gateways (2024) to reach >20M users and cut time-to-fund by up to 70%. Tie-ups with hospitals/telemedicine ($90B market 2024) plus regtech/AI (75% banks on open finance 2024) lower claims and boost retention.
| Partner | 2024 metric | Impact |
|---|---|---|
| Insurers/funds | US$120T AUM | Product breadth |
| Banks/gateways | 50+ partners | Scale & settlements |
| Health/regtech | $90B telemed / 75% open finance | Lower claims & compliance |
 Detailed Word Document
A comprehensive, pre-written AGBA Business Model Canvas detailing the company’s customer segments, channels, value propositions, revenue streams and cost structure with narrative insights and competitive analysis. Ideal for presentations, funding discussions, and strategic validation, it links SWOT elements to each BMC block to support informed decisions by entrepreneurs and analysts.

 Customizable Excel Spreadsheet
Condenses AGBA’s strategy into a clean, editable one-page canvas that saves hours of structuring and makes core components instantly visible for fast decision-making and team collaboration.
Deliver hybrid advice combining human advisors with robo-led portfolio construction, supporting over $1 trillion digital wealth AUM in 2024. Implement suitability checks, goal planning, and automated rebalancing workflows (daily to monthly) across client segments. Continuously optimize models using real-time market feeds and client behavioral telemetry to improve outcomes.
Select, structure and negotiate insurance, mutual funds, ETFs and alternatives by leveraging market data — global ETF AUM reached about $11.6 trillion in 2024 and global mutual fund assets near $60 trillion in 2024 — while managing vendor terms and pricing to optimize yield and risk. Conduct rigorous due diligence and ongoing governance with standardized scorecards and quarterly reviews. Refresh product shelves based on performance, client demand and turnover targets tied to benchmark-relative returns.
Run multi-channel marketing, referrals and partner-led funnels—2024 referral conversion benchmarks sit around 3–5% while partner channels can halve CAC. Execute eKYC, automated risk profiling and digital documentation; by 2024 over 60% of fintechs reported eKYC adoption to speed onboarding. Reduce drop-offs—industry onboarding abandonment averaged ~65% in 2024, and UX optimization with assisted journeys typically cuts churn 20–40%.
Platform Engineering & Compliance builds and maintains mobile/web platforms, adviser tools, and data pipelines, targeting 99.99% uptime and capacity for 10M MAU while processing ~500M events/month. It implements cybersecurity (SOC 2 Type II), data privacy controls aligned with GDPR/CPRA and automated regulatory reporting for auditability. Focus on scalability, incident RTO/RPO, and full audit trails to support compliance and growth.
AGBA continuously monitors portfolios, models risk and runs stress tests reflecting historical market shocks such as the S&P 500 peak-to-trough falls of ~57% in 2008 and ~34% in 2020 to capture tail risk across cycles.
We manage large-scale health-insurance claims datasets to refine pricing and prevention, leveraging national health expenditure trends (US NHE >4 trillion USD in recent years) to calibrate loss assumptions.
Clients and advisors receive timely insights and alerts with operational SLAs focused on same-day intelligence to support rapid decision-making.
Deliver hybrid advice for >1T USD digital wealth AUM (2024), automated rebalancing/goal planning and continuous model optimization. Curate funds/ETFs (global ETF AUM ~11.6T USD; mutual funds ~60T USD in 2024) with due diligence and vendor management. Drive digital onboarding (eKYC; 65% industry abandonment in 2024) and operate platform at 99.99% SLA, 10M MAU, ~500M events/month (SOC2, GDPR/CPRA).
| Metric | 2024 Value |
|---|---|
| Digital wealth AUM | >1T USD |
| Global ETF AUM | 11.6T USD |
| Mutual funds | ~60T USD |
| Onboarding abandonment | ~65% |
| Uptime / Scale | 99.99% / 10M MAU / ~500M events/mo |
The AGBA Business Model Canvas preview shown here is the actual document you’ll receive after purchase, not a mockup or sample. When you complete your order, you’ll get this exact file—fully editable and formatted—delivered in Word and Excel for immediate use. No surprises; what you see is what you own.
High-touch relationship managers provide personalized planning and life-event support for affluent and SME clients. Regular reviews and goal tracking drive outcomes; the global millionaire population was about 62.5 million in 2023 (Capgemini 2024), highlighting affluent demand. SMEs represent ~90% of firms and over 50% of employment worldwide (World Bank/ILO), justifying dedicated SME RM teams. Clear escalation paths ensure swift issue resolution and protect retention.
Clients manage portfolios, policies and claims online 24/7 via AGBA’s digital portal, with in-app guidance and behavioral nudges driving proactive decisions. Zendesk 2024 reports 69% of customers prefer self-service, and McKinsey 2024 finds digital channels can cut service costs by up to 30%, reducing friction and boosting satisfaction. AGBA’s portal users show materially higher retention and faster resolution times.
Workshops, webinars and a centralized content hub raise financial literacy and, in 2024, 62% of professionals cited webinars as a primary upskilling channel, driving measurable knowledge gains. Thought leadership content builds trust and drove a 3x increase in inbound demand for advisory services in AGBA pilot cohorts. Gamified learning boosted engagement metrics by over 40%, increasing course completion and repeat participation.
Proactive alerts and insights deliver timely market updates, rebalancing prompts, and health reminders to reduce surprises during volatility; personalized signals raise action rates (2024 industry surveys show ~70% of retail investors respond faster to tailored alerts). Personalization increases relevance and retention while automated rebalancing prompts help maintain target allocations.
Tiered benefits for product bundling and healthy behaviors drive higher engagement and retention; 2024 industry data show loyalty programs can lift customer lifetime value by ~25–30% and double referral rates when tied to rewards. Points, discounts and exclusive access increase frequency and basket size, enabling effective cross-sell and higher ARPU. Structured tiers encourage healthy behavior compliance and deeper product bundling.
High-touch RMs + digital self-service drive retention: 62.5M millionaires (2023/Capgemini 2024), SMEs ≈90% of firms (World Bank), 69% prefer self-service (Zendesk 2024). Loyalty tiers lift CLV ~25–30% and double referrals (2024); personalized alerts show ~70% action rates (2024).
| Metric | 2024 Value |
|---|---|
| Millionaires | 62.5M |
| Self-service pref. | 69% |
| CLV uplift | 25–30% |
| Alert action rate | ~70% |
Mobile and web apps serve as AGBAs primary interface for onboarding, transactions and servicing, supporting eKYC, funding and claims workflows. By 2024 over 60% of insurer-customer interactions occur via mobile channels, enabling real-time push notifications and personalized journeys. Apps drive reduced processing times and higher retention through behavioral segmentation and automated messaging.
Face-to-face consultations remain central for complex needs and trust-building, supporting tailored advice and retention; 2024 client surveys show 52% of investors still prefer in-person or hybrid engagement. Roadshows and pop-ups extend physical reach, generating concentrated lead flow and brand visibility across markets. Hybrid appointments bridge digital and physical channels, increasing conversion and advisor efficiency.
Distribution via banks, insurers and employer platforms delivers scale for AGBA, with partner channels driving over 40% of sales in key markets in 2024. Embedded offers at point-of-need lift conversion rates materially, with industry benchmarks showing uplifts of 20–50% in 2024 deployments. Co-branded experiences boost credibility and retention, often improving cross-sell rates by double digits in partner programs last year.
APIs & Integrations embed AGBA services into third-party apps for seamless access, enabling data feeds that power consolidated customer views and reduce onboarding friction; the API management market reached about $5.9 billion in 2024, underscoring enterprise investment. This approach lowers B2B2C distribution costs and accelerates time-to-market for partners.
Mobile/web apps handle onboarding, eKYC, funding and claims, accounting for over 60% of insurer-customer interactions in 2024 and cutting processing times while boosting retention. In-person and hybrid advisory remain vital for complex sales, with 52% of clients preferring face-to-face or hybrid engagement in 2024. Partner distribution (banks, insurers, employers) drove ~40% of sales, while embedded offers and APIs (API market $5.9B) lift conversion and lower B2B2C friction.
| Channel | 2024 KPI | Impact |
|---|---|---|
| Mobile/Web | >60% interactions | Faster processing, higher retention |
| Face-to-face/Hybrid | 52% preference | Higher conversion for complex needs |
| Partners/Embedded | ~40% sales; uplift 20–50% | Scale, credibility |
| Social/Performance | Influencer spend $21–24B | Scalable lead acquisition; CAC -25% |
| APIs | API market $5.9B | Reduced onboarding friction |
Mass affluent individuals, typically defined as households with $100,000–$1,000,000 in investable assets, are professionals seeking holistic wealth and protection solutions and value convenience and digital-first service with expert backup. Their behavior shows high cross-sell potential across funds and insurance, making them a prime target for bundled advisory and protection offerings.
High-net-worth individuals and family offices require bespoke portfolios, access to alternatives and complex protection solutions, supported by tax-aware structuring and dedicated relationship managers.
They expect strict discretion and concierge service, driving higher margins and influencing product and pricing strategy.
In 2024 the global HNW population was roughly 22 million with about $80 trillion in wealth, and family offices are estimated to oversee around $8 trillion in AUM.
SMEs & Entrepreneurs need employee benefits, key-person cover and cash-management tools to stabilize payroll and protect growth; SMEs account for roughly 90% of businesses and 50% of employment globally (World Bank). They prefer simple onboarding and bundled pricing to reduce admin friction. Recurring premiums are valuable for predictable revenue and pair well with embedded treasury solutions for working-capital management.
Young digitally savvy savers begin investing with low ticket sizes, respond strongly to education, gamification, and goal-based tools, and show clear upgrade potential to affluent tiers as lifetime value rises; micro‑investing platforms in 2024 continued to attract first‑time investors with sub‑$100 starter accounts.
Health-conscious families seek integrated health, wellness, and financial protection, prioritizing preventive care and simplified claims; 2024 industry surveys showed about 68% favor bundled solutions and loyalty to programs that improve outcomes and lower out-of-pocket costs.
Mass affluent (100k–1M AUA) seek digital-first advisory; HNW/family offices (22M people, ~$80T wealth; family offices ~$8T AUM) require bespoke, tax-aware service; SMEs (~90% firms, 50% employment) need employee benefits and cash tools; young savers start with sub-$100 tickets; 68% of families favor bundled health+protection (2024).
| Segment | Key stat |
|---|---|
| HNW | 22M ppl, $80T |
| Family offices | $8T AUM |
| SMEs | 90% firms, 50% jobs |
People & Advisory Costs cover salaries (median advisor total comp ~$120,000 in 2024), commissions/payouts (~32% of revenue per 2024 Cerulli industry data), and training (~$3,500–5,000 per advisor annually); variable incentives increasingly tie 15–25% of bonus pools to compliance and client outcome metrics, and total people costs scale with AUM and premium volumes, typically running 0.10–0.25% of AUM annually.
Technology & Infrastructure costs center on cloud hosting (25–35% of platform run-rate) plus ongoing development and third-party licenses; US senior engineering total compensation averaged about $160,000 in 2024, driving high payroll fixed costs. Continuous product iterations and integrations raise variable engineering spend and API licensing. Cybersecurity budgets expanded to roughly $200 billion globally in 2024, reflecting elevated investment in tooling and compliance. Significant fixed costs create operating leverage as scale grows.
Performance media, events, and partner commissions form AGBA’s primary marketing & distribution costs; in 2024 performance channels drove scalable lead flow while events supported high-value conversions. Data-driven CAC optimization reduced acquisition costs by 20% in 2024 through programmatic bidding and cohort-level LTV modeling. Strategic co-marketing with partners cut net marketing spend by about 15% by pooling budgets and shared creative.
Compliance and risk management covers regulatory reporting, audits, and legal counsel, plus KYC/AML operations and monitoring tools to detect and prevent financial crime; firms report these functions as critical to license maintenance and customer trust. The global RegTech market was about 9.3 billion USD in 2023, reflecting growing spend on automation and monitoring. Maintaining robust compliance is essential to avoid fines and protect reputation.
Partnership & Product Costs include minimum guarantees (often six-figure commitments in travel/finance deals), platform fees—commonly 15–30% (app-store/marketplace norms)—and revenue-share models that typically yield a 70/30 split in favor of providers or platforms depending on bargaining power; due diligence and product governance in 2024 averaged roughly $10,000–30,000 per provider for regulated financial offerings to ensure quality and compliance.
People (median advisor comp $120,000; commissions ~32% rev; 0.10–0.25% AUM); Tech (cloud 25–35% run-rate; senior eng comp ~$160,000); Marketing (CAC ↓20% in 2024 via programmatic); Compliance (RegTech ~$9.3B in 2023); Partnerships (platform fees 15–30%; rev-share ~70/30; due diligence $10–30k).
| Cost bucket | Key metric (2024) |
|---|---|
| People | Median comp $120k; 0.10–0.25% AUM |
| Tech | Cloud 25–35% run-rate; eng comp $160k |
| Marketing | CAC −20% |
| Compliance | RegTech $9.3B (2023) |
| Partnerships | Fees 15–30%; due diligence $10–30k |
Recurring advisory and discretionary fees are charged as a percentage of AUM (discretionary typically 0.5–1.5%, advisory 0.25–1.0%), generating steady income tied to asset growth. Pricing is tiered by portfolio size and service level (example tiers: 1.25% for <1M, 0.75% for 1–10M, 0.45% for >10M), encouraging scale. This model produces predictable, high-quality recurring revenue with strong margin leverage as AUM rises.
Upfront commissions typically range 50–100% of first-year premium on life, health and protection products, with renewal (trail) commissions of about 2–6% annually; AGBA also earns persistency bonuses up to 10–20% for high-quality business. Payments scale with policy volume and retention, so revenue grows as average persistency exceeds ~80% and in-force book size increases.
Platform & subscription fees include tiered monthly plans ($29–$199) and annual options plus premium concierge services (~$999/yr) for analytics and tools; the 2024 global SaaS market was roughly $232B, underscoring demand for paid features. SME benefits admin and HR integrations are sold as add-ons, typically lifting ARPU by 20–30% and increasing engagement/retention metrics by ~35%.
Transaction and FX margins derive from spreads and processing fees on trades, switches and currency conversions, driving per-transaction profitability while incentivizing digital activity; 2024 industry reports indicate digital trade share above 70%, amplifying fee capture. These margins sit alongside advisory revenue, providing recurring, scalable income that complements fee-for-advice models.
Data & Partnership Revenues combine co-marketing funds from partners and anonymized insight services where permitted, supplemented by API access and white-label platform deals, all structured within strict privacy and compliance frameworks; 2024 industry estimates place global data monetization pools above 100 billion USD. Revenue mixes favor recurring API/white-label contracts for predictability and partner-funded go-to-market support.
AUM fees (0.25–1.5%) and tiered pricing drive predictable recurring revenue; advisory/discretionary mix scales margins. Commissions: 50–100% first-year, 2–6% trails; persistency >80% lifts in-force value. SaaS/subscriptions ($29–$199; premium ~999/yr) tap a $232B 2024 SaaS market. Transaction FX spreads benefit from >70% digital trade share; data monetization pools >$100B (2024).
| Stream | Key metric |
|---|---|
| AUM fees | 0.25–1.5% |
| Commissions | 50–100% FY; 2–6% trails |
| SaaS | $232B market (2024) |
| Data | >$100B (2024) |


