
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Agenus shows promising immuno-oncology assets and partnership potential, but faces clinical, regulatory, and funding risks that could affect long-term value. Our full SWOT uncovers competitive positioning, pipeline nuances, and strategic levers. Purchase the complete, editable SWOT for investor-ready analysis and actionable recommendations.
Agenus (NASDAQ: AGEN), founded in 1994, leverages in-house discovery engines to generate antibody therapeutics, cancer vaccines and cell therapies, enabling faster lead identification and optimization. Proprietary platforms reduce dependency on third parties and improve internal control, supporting accelerated speed-to-clinic and increased partner attractiveness.
Agenus (NASDAQ: AGEN) advances antibodies, vaccines and cell therapies across three modalities, providing diversified exposure to multiple cancer mechanisms. This modality mix helps balance development risk by not relying on a single technology while supporting internal combination regimens across programs. The breadth increases optionality for additional indications and partnership opportunities with biopharma collaborators.
Agenus leverages combination therapy expertise to design assets meant to work together, including checkpoint targets, addressing immuno-oncology's need for synergistic regimens to overcome resistance. Combination-ready programs aim to unlock responses in refractory patients, where single-agent ORRs are often low. Industry-wide, combinations account for over 50% of IO trials, supporting differentiated clinical profiles and commercial value.
Targeting patients who fail conventional therapies concentrates Agenus on high unmet need populations where breakthrough designations and expedited FDA pathways are more attainable, enhancing pricing power and payer willingness to reimburse. Positive data in refractory settings historically drives rapid uptake and label expansion, increasing clinical relevance and commercial upside. This focus also differentiates the pipeline in crowded immuno-oncology markets.
Partnering and out-licensing position Agenus (NASDAQ: AGEN) as an attractive collaborator for larger pharma, leveraging its clinical-stage immuno-oncology platform and IO assets to fill pipeline gaps. Licensing deals provide non-dilutive capital and external validation, while co-development partnerships expand trial footprints and commercial reach. Strategic alliances can also de-risk late-stage execution by sharing costs and regulatory responsibilities.
Agenus (NASDAQ: AGEN), founded 1994, combines in-house discovery platforms for antibodies, cancer vaccines and cell therapies, enabling faster lead ID and reduced third-party dependence. The three-modality pipeline diversifies development risk and supports internal combination regimens. Focus on refractory populations targets high unmet need where accelerated pathways and premium pricing are attainable.
| Metric | Value |
|---|---|
| Ticker | AGEN |
| Founded | 1994 |
| Modalities | 3 (antibodies, vaccines, cell) |
| Industry combo trials | >50% |
 Detailed Word Document
Provides a concise strategic overview of Agenus by outlining its core strengths and internal weaknesses alongside external opportunities and threats, highlighting competitive positioning in immuno-oncology and platform diversification while noting development-stage risks, funding needs, and regulatory and market challenges.

 Customizable Excel Spreadsheet
Provides a concise Agenus SWOT matrix for rapid strategic clarity, helping teams quickly identify immuno-oncology strengths, clinical risks, and partnership opportunities to streamline decision-making.
Immuno-oncology programs face unpredictable efficacy and safety outcomes, with oncology approval rates of roughly 5% historically (2011–2020 BIO/Biomedtracker). Many assets fail in Phase 2/3 — estimated failure rates of 70–80% — so negative readouts can erase biotech value almost overnight. Agenus' portfolio concentration in IO compounds this company-specific execution and market-risk exposure.
As a development-stage biotech with no approved commercial therapies as of mid-2025, Agenus has minimal recurring product revenue; R&D intensity drives sustained cash consumption and operating losses that necessitate continual financing or strategic partnerships, while market volatility can constrain access to capital.
Approval paths for novel IO mechanisms are complex; FDA PDUFA review is 6 months for priority and 10 months for standard, while EMA centralized reviews target 210 days, complicating timelines. Increasing FDA/EMA emphasis on randomized data and overall survival endpoints often forces larger Phase 3 trials, extending development. Regulatory shifts have required mid-trial redesigns for some IO programs, delaying launches and magnifying costs and competitive risks.
Large Phase 3 programs typically cost $100M–$500M and global launches can exceed $1B, stressing Agenus’ limited internal infrastructure and slowing execution; reliance on CROs or partners raises coordination and timelines risk, while commercial penetration vs established incumbents will demand sizable marketing and sales investment.
Agenus (NASDAQ: AGEN) remains heavily concentrated in oncology and immuno-oncology, so sector-specific shocks or scientific setbacks in immune modulation could materially affect its pipeline and valuation. Diversification into non-IO indications is limited, leaving revenue and R&D upside tied to a narrow set of assets. This focus amplifies exposure to intense oncology competition and evolving reimbursement pressures.
Agenus faces high IO clinical risk: oncology approval ~5% (2011–2020) and Phase 2/3 failure ~70–80%, concentrating downside in IO. As of mid-2025 it remains development-stage with no approved products, driving cash burn and financing need. Large Phase 3/global launch costs ($100M–$500M; >$1B) strain limited infrastructure and commercial resources.
| Metric | Value |
|---|---|
| Oncology approval rate (2011–2020) | ~5% |
| Phase 2/3 failure | 70–80% |
| Phase 3 cost | $100M–$500M |
| Global launch capex | >$1B |
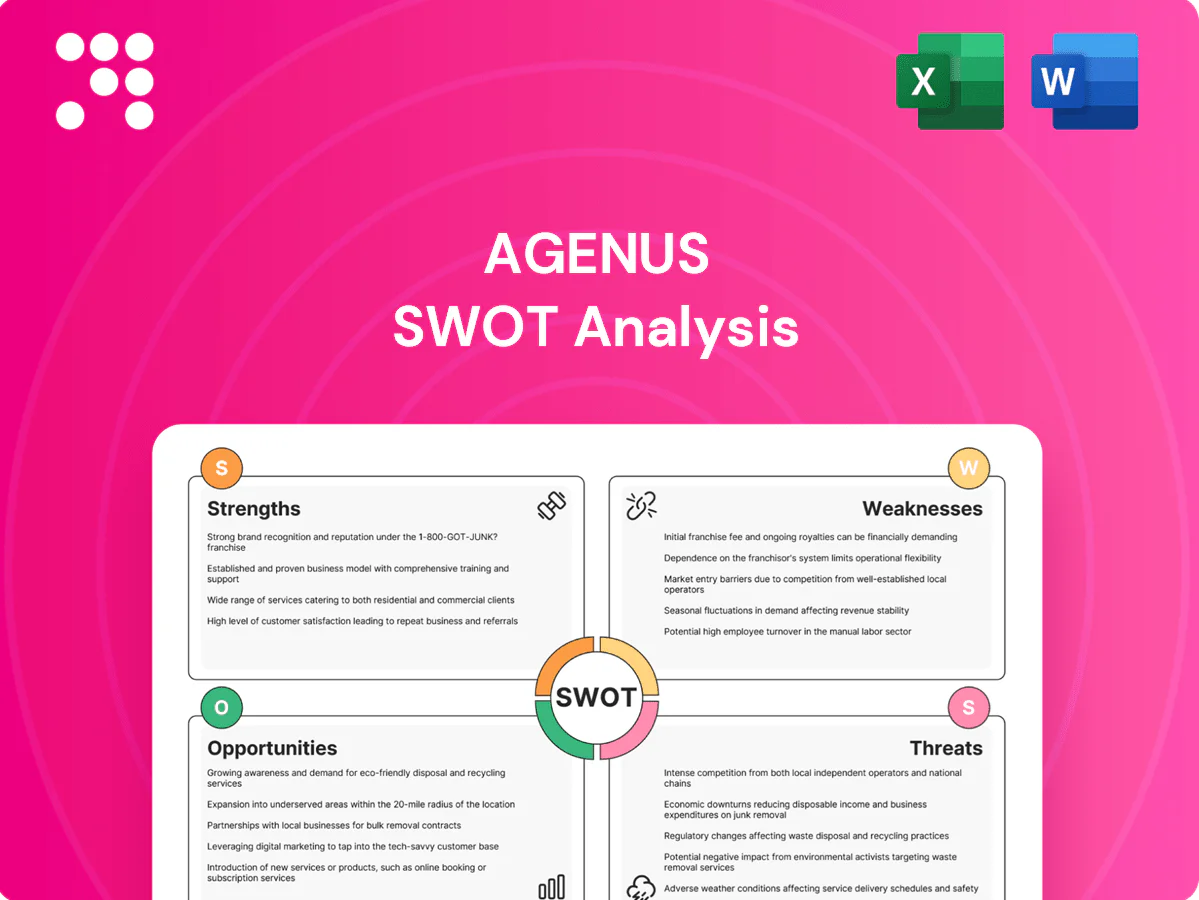
This is the actual SWOT analysis document for Agenus you'll receive after purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the same structured, editable file available for download post-checkout. Buy now to unlock the complete, in-depth version.
Immuno-oncology continues gaining share across tumor types and lines of therapy, driven by blockbuster PD-1 franchises such as pembrolizumab (Keytruda) which exceeded $20 billion in annual sales in 2023. Physicians are seeking options beyond PD-1 monotherapy as real-world response rates are often below 40% in many solid tumors. Novel mechanisms can capture refractory segments and broader indications materially expand TAM for companies like Agenus.
Companion diagnostics can identify responders and markedly improve trial success—biomarker-selected oncology trials often show response rates around 40–60% versus 10–20% in unselected populations, boosting statistical power and shortening timelines. Enrichment strategies increase observed effect sizes and regulatory appeal, contributing to faster approvals and higher likelihood of accelerated pathways. Biomarker-enabled labels allow premium pricing and better payer alignment, while real-world evidence loops (growing as RWE use rises annually) refine targeting and support label expansions and reimbursement negotiations.
Out-licensing select Agenus assets can immediately fund internal programs, with typical oncology partnerships delivering up-fronts often over $50 million and total deal values exceeding $1 billion in milestone potential. Big pharma collaborators accelerate global trials and market access—reducing time-to-market and regulatory burden. Milestones and tiered royalties diversify cash flow while joint combinations enable differentiated regimens and broader commercial positioning.
Hard-to-treat cancers can qualify for Fast Track, Breakthrough Therapy or Orphan Drug designations, which in the US provide benefits including 7 years of orphan exclusivity and expedited review. These pathways allow smaller single-arm trials and rolling/priority reviews, shortening timelines and lowering costs. Earlier entry can materially amplify Agenus's competitive edge in immuno-oncology.
Positive phase II/III data in one tumor type can support label expansion into adjacent indications, while regional approvals ex-US open additional revenue given global oncology drug sales exceeded $200 billion in 2023 and roughly half of demand lies outside the US. Lifecycle management via combinations and moving into earlier lines can extend commercial value and duration, and post-approval studies routinely broaden labels and uptake.
Agenus can capture PD-1 refractory and combo markets as immuno-oncology grew (Keytruda >$20B in 2023; global oncology >$200B in 2023). Biomarker enrichment (response 40–60% vs 10–20% unselected) and orphan/Breakthrough pathways (7-year US orphan exclusivity) accelerate approval. Out-licensing/partnerships often deliver >$50M up-front and >$1B total deal value.
| Opportunity | Metric | Impact |
|---|---|---|
| Market size | Global oncology >$200B (2023) | Large TAM |
| Blockbuster benchmark | Keytruda >$20B (2023) | Revenue potential |
| Biomarkers | 40–60% vs 10–20% response | Higher trial success |
| Deals | >$50M up-front; >$1B total | Non-dilutive funding |
| Regulatory | 7y US orphan exclusivity | Commercial protection |
PD-1/PD-L1 leaders like Keytruda (≈$20B+ sales in 2023) and Opdivo dominate IO market share, making it hard for Agenus to capture commercial traction.
Incumbents and multi-target portfolios can outspend on trials and commercialization, with top pharma R&D budgets often exceeding $10B annually.
Fast-followers rapidly crowd novel targets, and high differentiation hurdles impede payer and physician adoption, raising reimbursement and uptake risks.
Payers are tightening value assessments for cancer drugs, demanding clear survival benefit and biomarker-restricted use; a 2023 ASCO-linked survey found ~90% of oncologists reported treatment delays from prior authorization. Step-edits and prior authorizations slow uptake, while rebates and gross-to-net discounts often above 25% in oncology risk significant price erosion and margin compression for Agenus.
Checkpoint and immune-agonist therapies can trigger serious immune-related toxicities; CTLA-4 ipilimumab shows grade 3–4 irAEs in ~20–28% of patients and PD-1/CTLA-4 combos reached ~59% in CheckMate-067. Historic safety signals (eg, urelumab hepatotoxicity) halted development or forced dose reductions. Mandatory risk-management and pharmacovigilance (REMS/monitoring) increase trial complexity and costs. High-profile safety headlines can depress investor and class perception, amplifying commercial risk.
Operational and trial execution risks for Agenus include enrollment delays in niche indications that can push timelines and increase burn, complex biologics and cell therapy manufacturing scale-up that raises COGS and delay commercial readiness, supply chain or CMC setbacks that can jeopardize regulatory filings, and global trials exposed to geopolitical issues and site variability that threaten data integrity and timelines.
Overlapping immuno-oncology targets raise freedom-to-operate challenges for Agenus, increasing risk of IP disputes that can divert capital and management attention; recent industry litigation trends show elevated patent suits in IO, pressuring small biotechs dependent on limited pipelines. Narrow composition claims are often designed around by competitors, while patent expirations shorten market exclusivity and compress potential returns.
PD-1/PD-L1 incumbents (eg, Keytruda ≈$20B+ sales in 2023) dominate IO share, limiting Agenus commercialization pathways.
Payers tighten value; ~90% of oncologists reported treatment delays from prior authorization (2023) and oncology rebates/gross‑to‑net often exceed 25%, pressuring pricing and uptake.
Manufacturing scale‑up, enrollment delays and elevated IO patent litigation risk can raise costs, timelines and capital burn.
| Threat | Key metric | Impact |
|---|---|---|
| Market dominance | Keytruda ≈$20B+ (2023) | Limited market access |
| Payer pressure | Prior auth ~90%; rebates >25% | Revenue erosion, slower uptake |
| Ops/IP risks | Scale‑up & litigation exposure | Higher costs, delayed launches |


