
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
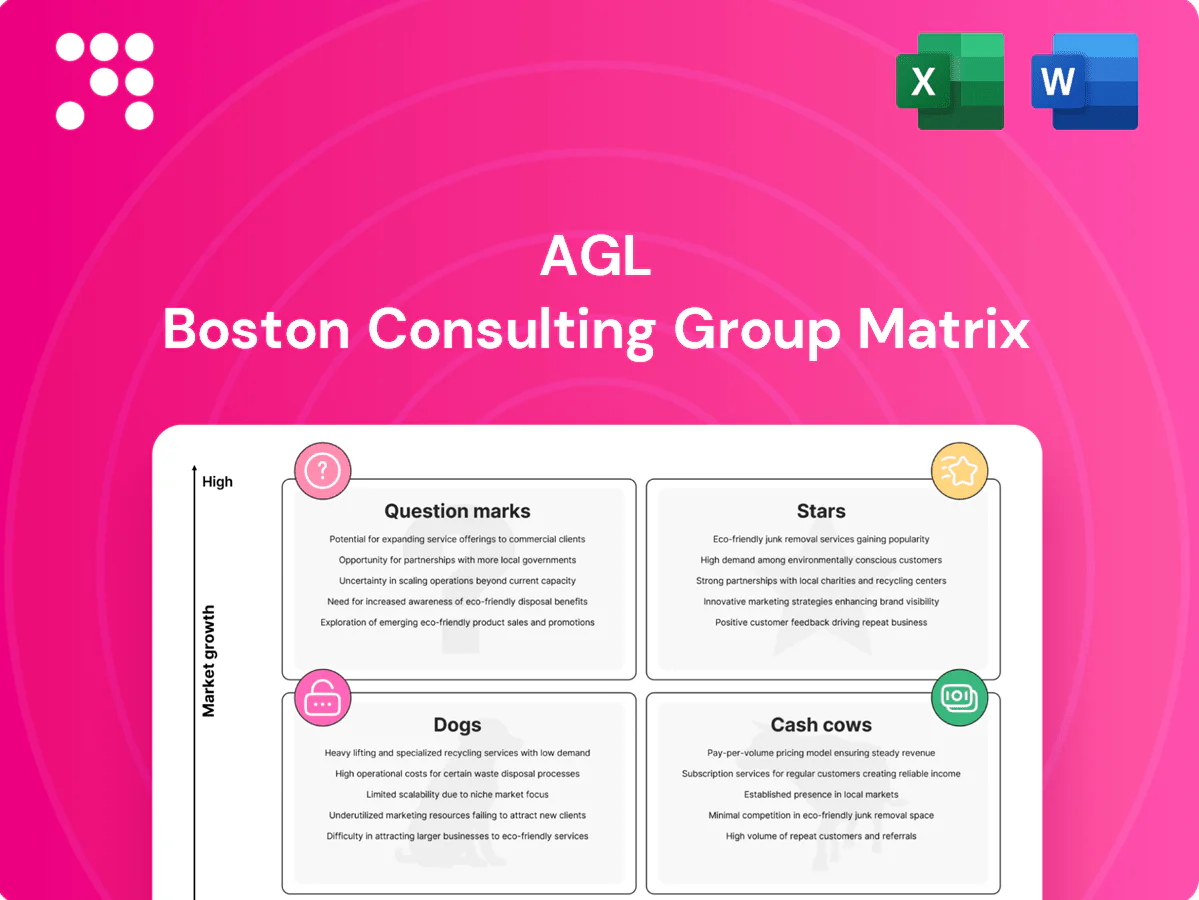
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where AGL’s products sit—Stars, Cash Cows, Dogs, or Question Marks? This snapshot points the way, but the full AGL BCG Matrix gives you quadrant-by-quadrant placement, data-backed recommendations, and a clear action plan. Buy the complete report for a polished Word analysis plus an Excel summary you can edit and present—skip the guesswork and get strategic clarity fast.
AGL’s growing utility-scale wind and solar pipeline—now exceeding 5 GW of capacity in development as of 2024—sits squarely on a surging demand curve for clean power driven by coal exits and tightening emissions targets. Market share is climbing as coal plants retire and corporate and government PPAs accumulate, supporting locked-in revenue streams. The business requires heavy near-term capex and grid reinforcement (hundreds of millions annually) but can harden into long-term cost leadership through scale and contracted cash flow; keep feeding projects to lock future cash flow.
Storage demand is exploding as renewables penetration and price volatility rise; global grid-scale deployments grew more than 2x from 2020–2024, opening large arbitrage windows. Early assets capture arbitrage, FCAS and capacity revenues, while building brand and operational know‑how that compound value. Capital‑hungry now, but once scaled storage generally stabilizes earnings via diversified revenue stacks. Double down while the investment window is wide open.
Customer batteries, smart inverters and flexible loads are piling up fast—Australia had over 3 million rooftop solar systems by 2024, driving rapid behind-the-meter storage adoption. Aggregation is a land‑grab: more nodes improve trading, reserve value and resilience across networks. It’s promo‑heavy and tech‑heavy today, but scale flips unit economics as marginal cost per kW falls. Hold share and VPP orchestration becomes a durable moat for AGL.
Enterprise buyers in 2024 demand firmed, high-volume green power now; AGL’s brand and balance-sheet scale win multi-year offtakes (typically 5–15 years), positioning it in a growing C&I market. Delivery is complex—firming, storage and active risk management require capital and trading muscle; maintaining win rates is key to cementing leadership.
Consumer adoption of solar+battery+tariffs is accelerating as bills and sustainability pressures rise, with residential solar penetration in Australia exceeding 30% of homes by 2024; bundles lock customers and enable cross‑sell. Acquisition and installation costs are steep, but churn falls and unit margin widens at scale. Push aggressively while competitors still stitch offerings together.
AGL’s Stars: >5 GW utility renewables pipeline (2024) and fast‑growing storage capture surging firming demand; rooftop solar >3m systems and >30% household penetration lift behind‑meter growth. High near‑term capex and grid spend; contracted PPAs and scale can convert to long‑term cash‑generating assets.
| Metric | 2024 | Implication |
|---|---|---|
| Renewable pipeline | >5 GW | High growth, scale |
| Rooftop solar | >3m systems / >30% homes | VPP & retail leverage |
| Storage growth | 2x since 2020 | Arbitrage & firming revenue |
 Detailed Word Document
Comprehensive AGL BCG Matrix review with strategic moves per quadrant, investment guidance and trend-driven risks.

 Customizable Excel Spreadsheet
One-page AGL BCG Matrix: quadrant view that exposes priorities, cuts guesswork and speeds C‑level decisions.
AGL’s residential electricity retail base comprises roughly 3.7 million customer accounts in 2024, a large, mature pool with predictable annual churn around 15–20%. Marketing spend is measured and margins hinge on strict cost‑to‑serve discipline, keeping customer acquisition efficient. The retail business throws off steady cash that helps fund transition capex; strategy is to maintain service, reduce opex, and quietly milk cash flow.
Small business power & gas retail is a mature, price-sensitive segment for AGL with low growth but high stickiness when paired with strong service; AGL reported about 3.7 million customer accounts at 30 June 2024, underpinning steady receivables. Bad debt remains manageable (typically low-single-digit percent of receivables with controls), limiting need for heavy promos beyond retention plays. Optimize margin via smart pricing, targeted retention offers, and channel efficiency to protect cash cows.
Hydro and fast-start peakers are established AGL assets with known cost curves and dispatch flexibility, routinely deployed into NEM volatility where 2024 average spot prices ran near A$110/MWh. Earnings remain resilient in tight market windows without massive capex, supporting strong cash conversion. Continuous efficiency and planned maintenance upgrades further squeeze more cash, while keeping units nimble to capture short-duration price spikes.
AGL’s legacy gas retail portfolio faces flat to declining demand but retains solid infrastructure and roughly 3.6 million energy customers in 2024, sustaining strong regional market share. Low growth drives modest support costs and stable cash flows; margin tuning and tighter credit management preserve profitability. Strategy: harvest while gradually migrating customers to electrified alternatives.
Long-term PPAs and the hedging book provide contracted, predictable gross margin with minimal incremental capital, funding growth without diluting returns. Risk is controlled through established trading frameworks and counterpart credit processes, keeping volatility low. Not flashy, but a steady cash engine that supports new investments. Maintain discipline and extend selectively.
Residential 3.7M accounts (2024), churn ~15–20%, predictable margins that fund transition capex. Hydro/peakers capture NEM spikes (avg spot ~A$110/MWh in 2024), high cash conversion. Long‑term PPAs/hedge book deliver contracted, capital‑light margins. Legacy gas 3.6M customers, flat demand—harvest strategy.
| Segment | 2024 metric | Role |
|---|---|---|
| Residential | 3.7M; churn 15–20% | Primary cash cow |
| Hydro/Peakers | Avg spot A$110/MWh | High cash conversion |
| Gas retail | 3.6M; flat demand | Harvest |
| PPA/Hedge | Multi‑yr contracts | Stable margin |
The file you're previewing is the exact AGL BCG Matrix report you'll receive after purchase — no watermarks, no placeholders, just the finished, fully formatted document. It's crafted for strategic clarity by experts and ready to plug into your planning, decks, or client meetings. After payment you'll get immediate access to download, edit, and present with confidence. No surprises, no extra steps — just ready-to-use analysis.
Dogs:
High-cost legacy gas peakers retain peaking value but in 2024 fuel costs (~A$12–20/GJ) and carbon prices (around A$60–90/t) crush margins except during rare spot spikes above A$500/MWh. Upgrades yield limited uplift versus capital outlay, with retrofit CAPEX often exceeding incremental revenue. Cash becomes tied up for thin returns; retire, replace with batteries/renewables or convert to low-emissions fuel are viable pathways.
Non-core home services add-ons (warranty/ancillary) sit in Dogs: low differentiation and low growth, distracting focus and soaking operational bandwidth. For AGL, with ~3.6 million customer accounts in 2024, these offers generated under 1% of group revenue and are break-even at best after overhead. Trim or partner out to redeploy resources to core energy transition businesses.
Paper-centric billing and legacy metering tech create operational drag with little upside for AGL, where print+post per bill typically exceeds AUD 1.30 (standard Australia Post stamp, 2024) while roughly 3.7 million customer accounts migrate to digital channels.
Costs persist as customers move online, making transformation spend (platform consolidation and AMI/smart meter rollout) more cost-effective than incremental patching of aging systems.
AGL should sunset paper workflows and legacy metering, shifting to modern billing platforms and smart-meter-led operational models to cut per-account costs and accelerate digital adoption.
Stranded small-scale thermal assets are odd-lot units that fail to scale commercially; they generate negligible market share and show no growth trajectory, yet compliance and maintenance continue to burn cash quietly, eroding margins and tying up capital. Divest or decommission to stop ongoing losses.
Dogs: aging coal fleet (>40 yrs) with maintenance >AUD100m/unit and shrinking margins; high-cost gas peakers crushed by 2024 fuel A$12–20/GJ and carbon A$60–90/t; non-core services <1% revenue of ~3.7M accounts and paper billing >AUD1.30/bill are low-growth drains—divest, retire, or sunset and redeploy to renewables/storage.
| Item | 2024 Metric |
|---|---|
| Accounts | ~3.7M |
| Coal maint. | >AUD100m/unit |
| Paper bill cost | >AUD1.30 |
| Gas fuel | A$12–20/GJ |
EV charging & smart tariffs sit in Question Marks: EV load is set to surge but AGL’s share isn’t locked, requiring network deals, hardware partners and slick pricing. AGL serves about 3.7 million retail customers (2024), so charging could become a major stickiness lever if deployed at scale. Invest to win key corridors and fleets early to capture long-term load and revenue.
In 2024 green hydrogen pilots sit squarely in AGLs Question Marks: high-growth buzz but near-zero current revenues. Technology, offtake structures and policy frameworks remain immature in 2024, keeping commerciality uncertain. If electrolyser and renewable levellised costs fall, green H2 can anchor firming and industrial decarbonization. Place disciplined bets and stage-gate hard with clear scale/exit triggers.
Migration from gas accelerated in 2024 but remains fragmented across installers and regions; heat pumps typically deliver COP 3–5, making electrification energy-efficient. Installation logistics and upfront financing—often several thousand dollars per home—are the primary hurdles to adoption. Whoever streamlines the homeowner journey (sales, permits, install, finance) will own the category, so test, learn, and scale with local partners.
Embedded networks and strata energy services target a growing multi-dwelling market with bespoke metering and billing needs; Australia has over 1.1 million strata lots (SCA Australia, 2024). AGL’s share is low today but offers strong cross-sell into retail and services, with contracts often becoming sticky once landed, supporting higher lifetime value. Focused go-to-market and scalable platform tools are essential to capture this segment.
Data & AI energy management for C&I sits as a Question Mark: early revenues and high attach potential via supply contracts, with clients demanding cost cuts plus carbon reporting in one pane of glass; CSRD expanded EU reporting to about 50,000 companies from 2024, raising demand for integrated reporting and measurable savings.
EV charging, green H2, heat-pump migration, strata energy and C&I Data&AI are Question Marks for AGL in 2024: high growth potential but low current share. AGL serves ~3.7m retail customers (2024) and must invest selectively with clear scale/exit triggers. Prioritise corridor/fleet EVs, staged H2 pilots, streamlined heat-pump installs, scalable strata platforms and provable analytics.
| Segment | 2024 metric | Priority |
|---|---|---|
| EV charging | 3.7m customers | High |
| Green H2 | pilot revenues≈0 | Medium |
| Heat pumps | COP 3–5 | High |
| Strata | >1.1m lots | High |
| Data&AI C&I | CSRD ≈50k firms | Medium |


