
Digital download
Access the files immediately after checkout.
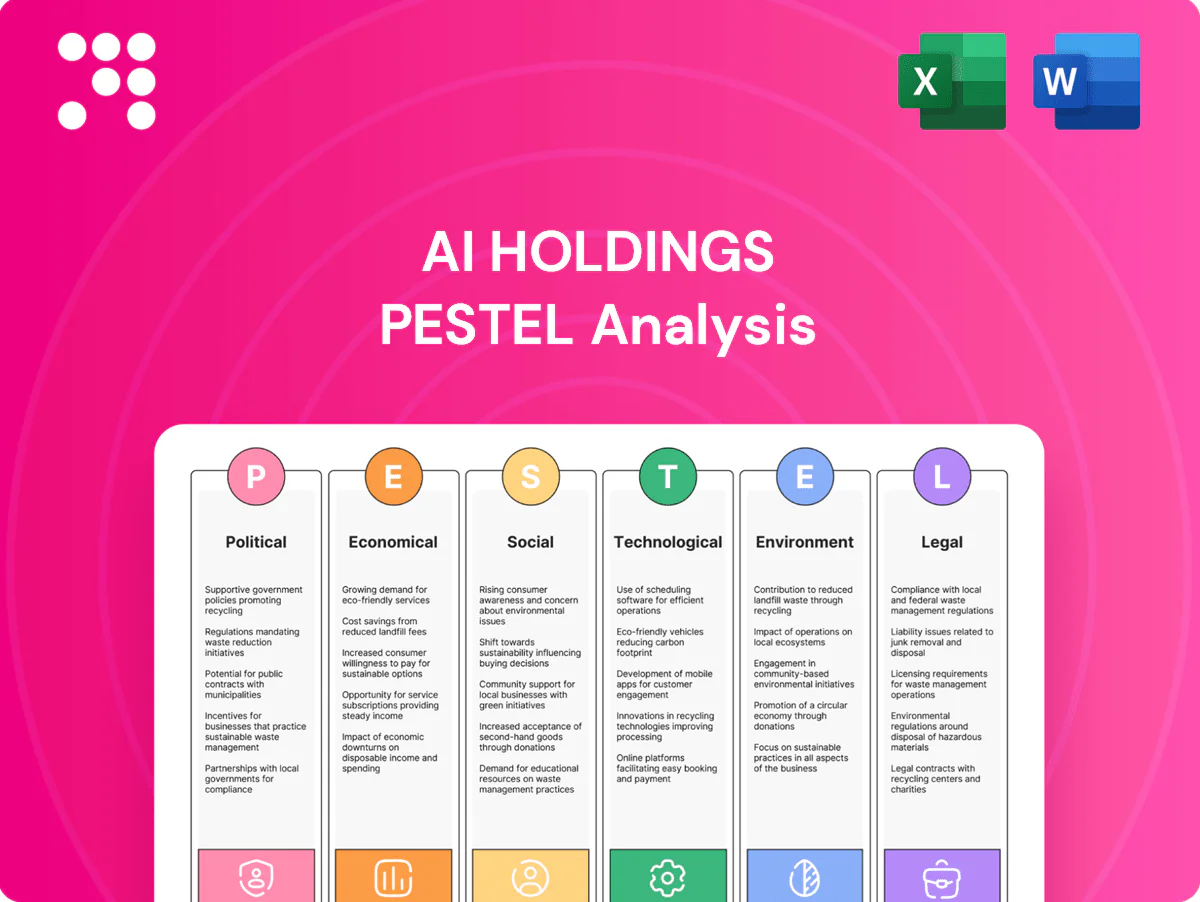
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Gain a strategic advantage with our PESTLE analysis of Ai Holdings—uncover political, economic, social, technological, legal and environmental forces shaping its trajectory. Packed with actionable insights for investors and strategists, it highlights risks and growth opportunities you can act on immediately. Purchase the full, editable report to get the complete breakdown and start making smarter decisions today.
National and municipal policies determine where Ai Holdings can deploy capital, steering pipeline timing and yield realizations; 2024 planning reforms in key markets increased allowable FAR in priority transit districts by up to 3x, unlocking significant value-add upside. Zoning constraints in low-density wards continue to limit conversions or mixed-use schemes and compress IRR. Close, ongoing engagement with city planners and early entitlement strategies reduces approval delays and entitlement risk, protecting projected cash-on-cash returns.
UK public infrastructure projects like the Elizabeth line (approximate cost £18bn) and the government flood‑defence programme (£5.2bn allocated to 2021–27) materially lift demand and achievable rents for nearby assets; slippages or budget rephasing change expected footfall and capex timetables. Aligning leasing with planned station openings can secure pre‑leasing premiums, and tracking stimulus cycles (eg fiscal 2024–25 capital plans) times refurbishments for maximum yield.
Japan offers grants and tax incentives for building retrofits as part of its drive to meet a 46% greenhouse gas reduction target by 2030. Capturing available subsidies materially lowers payback on HVAC, insulation and smart controls. Program eligibility and application timing are critical to realized ROI. Policy rollbacks or funding cuts could extend breakeven periods materially.
Regional tensions can reduce foreign capital and tenant demand; rising global military expenditure (SIPRI: $2.24 trillion in 2023) highlights heightened geopolitical risk. Supply-chain or import delays push refurbishment timelines and costs higher, while insurance premiums tend to increase with perceived risk. Diversification across multiple cities cushions revenue and occupancy volatility.
Policy shifts drive deployment timing, with 2024 planning reforms raising FAR up to 3x in transit zones and unlocking value‑add upside while low‑density zoning compresses IRR. UK infrastructure (Elizabeth line ~£18bn; flood defence £5.2bn to 2021–27) and Japan retrofit subsidies tied to 46% GHG cut by 2030 materially affect rents, capex and payback. Geopolitical risk (global military spend $2.24tn in 2023) tightens capital flows, raises insurance and supply delays.
| Item | Political impact | 2024–25 metric |
|---|---|---|
| FAR reforms | Higher development yield | Up to 3x in transit districts |
| UK infra | Rent uplifts | Elizabeth line ~£18bn |
| Japan subsidies | Lower retrofit payback | 46% GHG target by 2030 |
| Geopolitics | Capital/insurance risk | Military spend $2.24tn (2023) |
 Detailed Word Document
Explores how macro-environmental factors uniquely affect Ai Holdings across Political, Economic, Social, Technological, Environmental and Legal dimensions, with data-backed insights and forward-looking scenarios to identify threats, opportunities and strategic responses; designed for executives, investors and consultants and ready for inclusion in plans and decks.

 Customizable Excel Spreadsheet
A concise, visually segmented PESTLE summary of Ai Holdings that’s easily dropped into presentations, editable for region or business-line specifics, and shareable across teams to streamline external risk discussions and accelerate strategic alignment.
BoJ policy (short-term rate ~0.1% and 10‑yr JGB ~0.8% mid-2025) directly shapes financing costs and valuation multiples; even a 25bp shift typically lifts cap rate expectations ~20–40bp and can cut valuations 3–6%, materially changing acquisition math. Fixed-rate debt ladders are used to hedge refinancing risk during upcycles, while rigorous sensitivity analysis (IRR and cap‑rate scenarios) enforces bid discipline.
Materials and labor cost inflation—U.S. construction wages rose about 4.5% YoY in 2024 and steel prices eased roughly 8% from 2022 peaks—directly compress renovation yields for Ai Holdings. Locked contracts and supplier diversification can stabilize margins, while indexation clauses in leases permit partial cost pass-through. Deferred capex raises lifecycle expense and asset deterioration risk.
Ai Holdings faces divergent cycles: US office vacancy rose to ~16% in 2024 amid remote work (~20% of workdays remote), pressuring demand; logistics vacancy stayed tight at ~4.5% with industrial rent growth ~7% y/y (2024); multifamily rent growth slowed to ~3% y/y but remains resilient; retail vacancy ~6.5%. Active asset rotation and dynamic pricing with shorter leases boost portfolio NOI flexibility.
Yen weakness (around 155 JPY/USD peak in 2022–23) can boost inbound investment and tourism, lifting occupancy rates and asset valuations while raising imported retrofit equipment costs; Ai Holdings must price projects accordingly and use FX forwards/options to hedge cross-border contract cash flows. Targeted marketing to global tenants widens demand and supports higher rents in USD-linked leases.
IMF Apr 2025 projects global GDP growth ~3.1% for 2025, while UNWTO/IATA data show international arrivals recovered to roughly 90–95% of 2019 levels by 2024; buoyant inbound travel lifts retail and hospitality-adjacent asset rents, especially high-street and station-area leases. Economic slowdowns force conservative tenant-credit underwriting; flexible space models enable rapid pivot to demand shifts.
Low BoJ rates (~0.1%) and 10‑yr JGB ~0.8% mid‑2025 lower cap rates but a 25bp hike can cut valuations 3–6%; fixed‑rate debt and IRR sensitivity guard acquisition math. 2024: US construction wages +4.5% YoY; logistics rent +7% y/y; office vacancy ~16% compresses demand. Yen ~155 JPY/USD raises asset prices and import costs; FX hedges and global tenant targeting mitigate risk.
| Metric | 2024/2025 | Impact | Mitigation |
|---|---|---|---|
| BoJ rates/JGB | ~0.1% / 0.8% | Valuation sensitivity | Fixed debt, IRR stress |
| Wages/rents | Wages +4.5%; logistics +7% | Margin pressure | Indexed leases |
| Yen FX | ~155 JPY/USD | Higher imports, tourism uplift | FX hedges |
The preview shown here is the exact Ai Holdings PESTLE Analysis you’ll receive after purchase—fully formatted and ready to use. It contains the same structured political, economic, social, technological, legal and environmental assessments shown, with no placeholders or edits. After checkout you’ll instantly download this final, professionally prepared document.
Japan’s 65+ cohort reached about 29.1% of the population in 2024—roughly 36.6 million people—driving demand for barrier-free designs and elder-friendly services. Retrofitting elevators, ramps and clearer signage improves accessibility and can raise occupancy rates in aging stock. Proximity to healthcare and senior-living facilities creates high-demand leasing niches. Compliance with universal design strengthens brand equity and market differentiation.
Tenants increasingly favor locations near major stations with amenities, driving stable demand and higher occupancy. Concentrating assets in vibrant transit nodes supports rent resilience as urbanization accelerates—UN projects urban population to reach 68% by 2050. Mixed-use activation boosts dwell time and spend, while real-time footfall data guides precise tenant curation.
Office tenants increasingly demand flexible footprints, improved air quality and dedicated collaboration zones, with 2024 surveys showing about 65% of major occupiers prioritizing hybrid-ready space. Subdivisible floors and short-term agreements have expanded, meeting demand for agility; amenity upgrades now support roughly a 5% rent premium in competitive markets. Utilization analytics, adopted by many landlords, reduce wasted space by up to 20% and guide reconfigurations to boost ROI.
Post-pandemic standards drive higher demand for rigorous maintenance; the global facility management market exceeded $1 trillion in 2024, increasing opportunity for Ai Holdings to scale cleaning and filtration offerings. Enhanced cleaning, advanced air filtration, and third-party certifications have been shown to reduce tenant churn and vacancy risk. Transparent reporting and bundled FM services enable cross-sell, raising revenue per tenant and trust.
ESG-conscious occupiers and capital increasingly screen properties for green credentials; buildings account for ~40% of global energy use (IEA), and sustainable fund assets topped roughly $3.2 trillion in recent years, fueling demand for ESG-ready space. Publishing energy, water, and waste metrics supports leasing and can command valuation premiums (often 3–5% for green-certified assets). Community engagement programs improve reputation while aligning KPIs with frameworks like GRESB and TCFD attracts institutional capital.
Aging Japan: 65+ = 29.1% (2024), boosting demand for accessible, healthcare-adjacent assets. Transit-oriented tenants prefer station nodes; urbanization to 68% by 2050 supports rent resilience. 65% of occupiers in 2024 prioritize hybrid-ready offices; ESG screening and green premiums (3–5%) attract institutional capital.
| Factor | Key stat |
|---|---|
| Aging | 65+ 29.1% |
| Urbanization | 68% by 2050 |
| Hybrid demand | 65% occupiers (2024) |
| Green premium | 3–5% |
IoT sensors, smart meters and BMS in retrofits have cut building energy use 15–20% and improved occupant comfort, supporting Ai Holdings green targets; global smart buildings market was about $120 billion in 2024 with ~12% CAGR. Retrofits typically lower opex 8–12% with paybacks of 3–5 years. Interoperable platforms speed portfolio rollouts and clear ROI cases have driven tenant uptake and leasing premiums of 3–5%.
Condition monitoring and predictive maintenance can cut unplanned downtime by up to 50% and emergency callouts by ~40%, while CMMS standardizes workflows and trims parts/inventory costs ~20–30%. Data-driven scheduling boosts technician productivity 15–25%, and vendor integrations drive SLA compliance toward 95%, lowering contract penalties and mean time to repair.
Digital twins and BIM enable clash detection, retrofit planning and scenario testing—reducing change-orders/rework by about 20–30% and cutting commissioning time; accurate asset data lowers change-order risk and supports twinned operations that can drive 10–20% OPEX reductions; targeted team training shortens time-to-value, with pilot programs reporting benefit realization within 6–12 months.
Connected HVAC, access and energy controls expand attack surfaces, with IoT-linked breaches driving operational outages and remediation costs; IBM's 2024 Cost of a Data Breach found average losses of $4.45 million. Segmented networks, MFA (blocks ~99.9% of automated attacks) and timely patching materially reduce tenant exposure and downtime. Compliance with data laws limits liability, while regular audits and drills improve incident resilience.
Tenants demand reliable high-speed 5G and wired connectivity; JLL 2024 found fiber-connected commercial buildings command a 4–6% rent premium, while in-building 5G DAS and small cells improve lease appeal. Neutral-host deployments can cut infrastructure costs roughly 30–40% (Deloitte 2024), and active uptime monitoring with 99.99% SLAs supports premium positioning.
Smart-building tech (global market $120B in 2024, ~12% CAGR) and IoT retrofits cut energy 15–20% and opex 8–12%; digital twins/BIM reduce rework ~20–30% and OPEX 10–20%. Cyber risk: IBM 2024 breach cost $4.45M average; segmentation/MFA/patching reduce exposure. Fiber/5G demand lifts rents +4–6%; neutral-host cuts infra capex 30–40%.
| Metric | Impact | 2024/25 Data |
|---|---|---|
| Smart buildings | Market growth | $120B; ~12% CAGR (2024) |
| Energy reduction | Retrofits | 15–20% energy cut |
| Cyber loss | Avg breach cost | $4.45M (IBM 2024) |
| Connectivity | Rent premium/capex | Fiber +4–6% rent; neutral-host −30–40% capex |


