
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Alliar's SWOT snapshot highlights a strong diagnostic network and brand reach, balanced by regulatory exposure and capital intensity. Our full SWOT unpacks competitive positioning, financial risks, and growth levers with actionable strategy. Purchase the complete, editable Word + Excel report to plan, pitch, or invest with confidence.
Alliar's nationwide network—over 300 service points as of 2024—boosts brand visibility and patient access across Brazil. Dense site density shortens turnaround times and increases referral stickiness, improving retention and per-patient revenue. Scale enhances negotiating leverage with suppliers and payers and allows capacity rebalancing across regions to smooth demand peaks.
Alliar (AALR3 on B3) combines imaging, clinical analysis and specialized exams to drive cross-sell and single-stop convenience, increasing per-patient revenue and appointment stickiness. A broad menu raises utilization of fixed assets such as imaging suites and labs, improving throughput. Diversified modalities and acuity spread revenue sources, reducing dependence on any single service line.
Alliar (AALR3 on B3) delivers high-quality diagnostic results that underpin physician loyalty and steady referral flows. Consistent accuracy reduces rework and patient dissatisfaction, supporting faster report turnaround and fewer repeat scans. Accreditations and standardized protocols (ISO/ONA) reinforce operational reliability. Clinical trust functions as a durable moat in diagnostic decision pathways.
Advanced equipment and digital workflows in Alliar improve throughput and image quality through integrated RIS/PACS and centralized labs, enabling faster reads and consistent diagnostics. Data-driven scheduling and routing cut bottlenecks and reduce patient wait times while standardization spreads scalable best practices across sites.
Deep, embedded referral networks sustain stable imaging volumes for Alliar, while negotiated payer relationships secure reimbursement and inclusion on key panels; joint programs with physicians improve care pathways and measurable outcomes, raising utilization and quality metrics and creating tangible switching costs for hospitals and payers.
Alliar (AALR3) operates a nationwide network of over 300 service points as of 2024, enhancing access, retention and per-patient revenue. Integrated imaging, clinical analysis and centralized labs boost asset utilization and cross-sell. Standardized protocols and RIS/PACS drive consistent quality and faster turnarounds.
| Metric | Value | Source/Year |
|---|---|---|
| Service points | >300 | Company 2024 |
| Ticker | AALR3 (B3) | Exchange 2024 |
| Key systems | RIS/PACS, central labs | Company 2024 |
 Detailed Word Document
Provides a concise SWOT analysis of Alliar, outlining internal strengths and weaknesses and external opportunities and threats to clarify its strategic position, growth drivers, and key risks.

 Customizable Excel Spreadsheet
Provides a clear, concise SWOT matrix tailored to Alliar for rapid strategy alignment and stakeholder-ready summaries; editable format enables quick updates as priorities shift.
Imaging and lab platforms demand large upfront spends—typical scanners and analyzers range from roughly $200,000 to $3 million—plus ongoing maintenance and service contracts that can run 5–10% of capex yearly. High depreciation means payback hinges on sustained high utilization (often >60–70%) to cover fixed costs. Higher rates raise financing costs; Brazil’s SELIC peaked at 13.75% in 2023, increasing borrowing pressure.
Multi-site, multi-modality operations at Alliar are difficult to standardize, leading to inconsistent protocols across units. Variability in local demand and staffing causes uneven performance and patient throughput. Sample and image logistics require complex coordination, raising turnaround-time risk. Operational complexity tends to inflate overhead and can increase error rates.
Revenue is highly dependent on negotiated tariffs and public/private payer policies, making Alliar vulnerable to reimbursement cuts that compress margins; payment delays and stricter authorization rules also depress cash flow and slow patient volumes. Shifts toward lower-paying plans or greater reliance on public payers reduce average ticket size and profitability, increasing sensitivity to policy and contracting changes.
Scarcity of radiologists, pathologists and technologists in some Brazilian regions forces Alliar to route exams to hubs, extending turnaround times by up to 48 hours in 2024; hiring and retention costs rose ~12% year‑over‑year, pressuring margins. Overreliance on a handful of specialists creates continuity risk and episodic capacity shortfalls during absences. Recruitment investment and contract premiums increased to secure shift coverage.
Legacy IT fragmentation leaves Alliar with disparate RIS/LIS/PACS instances that impede data interoperability, slow deployments of new tools and AI, and force manual workarounds that raise error risk; each legacy node also expands the cyberattack surface.
High capex ($200,000–$3M per scanner) with 5–10% annual maintenance and required utilization >60–70% strain margins; SELIC 13.75% (2023) raised financing costs. Multi-site variability and legacy IT fragmentation slow AI rollouts, increase errors and cyber surface. Staffing shortages raised hiring/retention costs ~12% (2024) and caused turnaround delays up to 48h.
| Metric | Value |
|---|---|
| Scanner cost | $200k–$3M |
| Maintenance | 5–10% capex/yr |
| Required utilization | >60–70% |
| SELIC peak | 13.75% (2023) |
| Hiring cost rise | +12% (2024) |
| Turnaround | up to 48h |
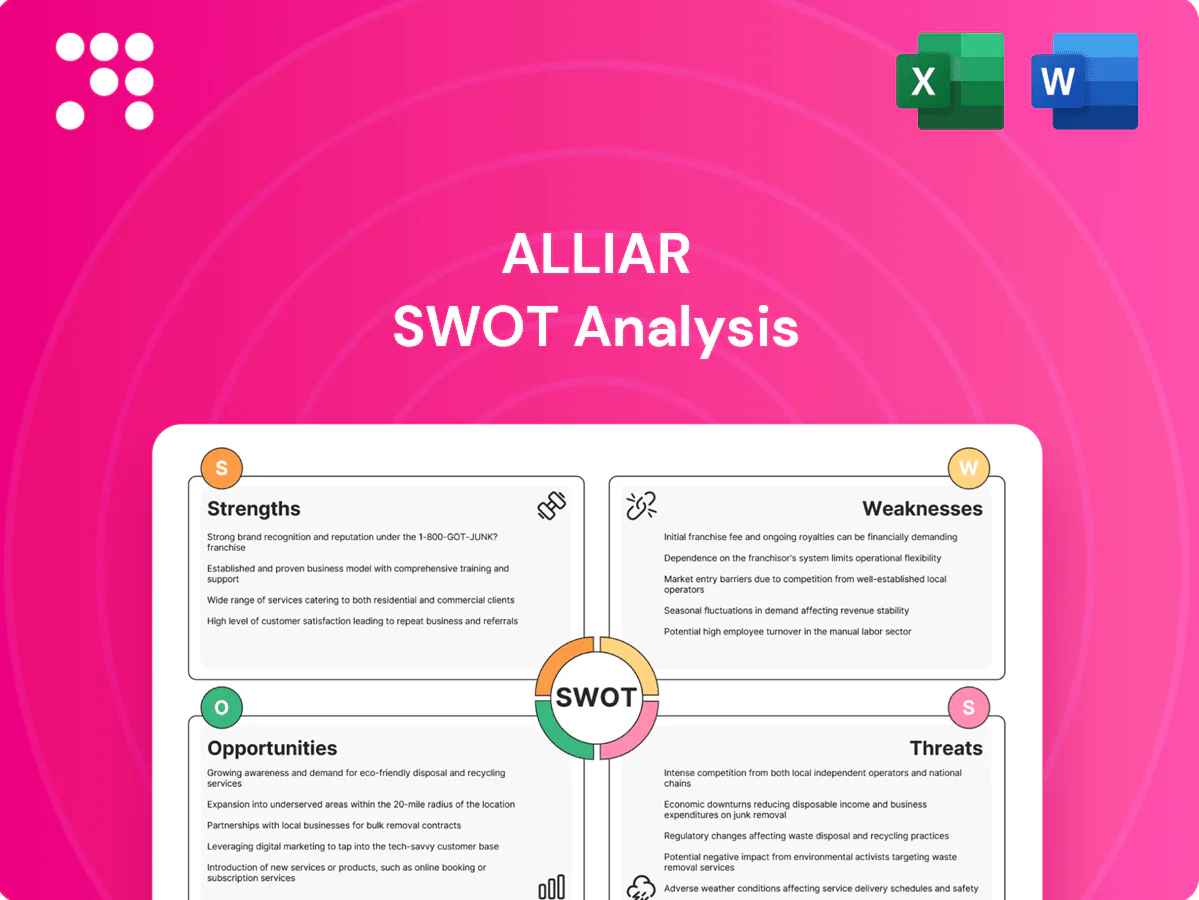
This is the actual Alliar SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the same structure, findings, and editable content. Purchase unlocks the complete, detailed version ready for download and immediate use.
Aging populations—over 700 million people aged 65+ globally (UN DESA 2020) —boost demand for imaging and lab tests, raising long-term volume for Alliar. Noncommunicable diseases cause ~74% of global deaths (WHO), driving recurring monitoring and revenue predictability. Wider adoption of earlier screening and preventive care programs expands addressable volumes and can anchor multi-year patient pipelines.
Tier-2/3 markets in Brazil, which span over 5,570 municipalities, present lower competition and strong growth potential for Alliar. A hub-and-spoke lab model can increase coverage cost-efficiently by centralizing complex testing while using local collection points. Expanding home sample collection and mobile imaging taps a global home healthcare trend growing at ~8.5% CAGR through 2030, boosting convenience and retention. Strategic partnerships with clinics can accelerate market entry and referrals.
AI triage and workflow tools can cut radiologist reading time by up to 50%, boosting accuracy and productivity. Automated analytics shorten turnaround times by around 30–60% in diagnostic pathways. Digital booking, payments and instant results reduce no‑shows by 20–30% and raise patient satisfaction. Combined, these levers materially lower unit cost per exam.
Bundled diagnostics with insurers and employers can secure steady volumes in Brazil, population ~203 million with roughly 25% (~50 million) on private plans, while outcome-linked contracts align incentives on quality and cost; occupational and wellness programs provide recurring demand and shared data enables population-health insights for risk stratification and preventive care.
New service lines in genomics, advanced cardiology imaging and comprehensive oncology panels can improve revenue mix quality by capturing higher-margin, specialized diagnostics and reducing reliance on routine testing commoditization.
Growing demand from aging and NCD burdens increases long‑term test volumes; global 65+ population ~760M by 2024 (UN DESA) and NCDs ≈74% of deaths (WHO).
Expansion into 5,570+ Brazilian Tier‑2/3 municipalities and home care (8.5% CAGR to 2030) can boost market share and retention.
AI, digital booking and bundled insurer/employer contracts can cut unit costs ~30–50% and lock volume.
| Metric | Value |
|---|---|
| Brazil pop | 203M (2024) |
| Private plans | ≈50M |
| Home care CAGR | 8.5% to 2030 |
Large national groups like Dasa and Fleury and strong regional chains intensify price pressure on Alliar; consolidation has concentrated buyer power, with the top national players now commanding roughly 40% of diagnostic contract volumes in Brazil (2024). New digital entrants captured double‑digit growth in high‑margin imaging niches in 2024, and escalating price wars risk eroding service quality and Alliar’s margins.
Changes in regulation and accreditation can raise operating costs and require capital investments; updates to reimbursement rules may compress tariffs while tighter oversight on test utilization can reduce volumes. Non-compliance risk includes LGPD fines up to 2% of revenue per infraction, limited to BRL 50 million, plus material reputational damage.
Macroeconomic volatility and rising inflation squeeze consumers, delaying elective exams and lowering diagnostic volumes; Brazil's household consumption growth slowed to about 1.5% in 2024, reducing discretionary healthcare demand.
Inflation lifts payroll, reagent and energy costs—Brazil's IPCA was near 4.2% in 2024—pushing operating expenses higher for Alliar.
Repricing lags versus input inflation compress margins; sequential margin pressure was visible across Brazilian diagnostics peers in 2024.
Economic downturns increase bad debt and intensify payer price pressure, raising collection risk and reimbursement negotiation strain.
Protected health information is a prime target, with IBM Security 2024 reporting healthcare as the costliest sector for breaches—average breach cost $11.45M—while ransomware and data theft drive legal, financial and reputational fallout. Regulatory compliance (HIPAA, LGPD, GDPR) raises overhead and audit costs, and system downtime—often weeks after attacks—disrupts clinical operations and patient care.
Imported diagnostic equipment and reagents expose Alliar to foreign-exchange volatility, raising procurement costs and compressing margins when the real weakens against the dollar.
Extended lead times and global parts shortages have delayed planned upgrades and maintenance, reducing uptime at imaging centers and limiting revenue capture.
Currency swings also complicate multi-year pricing and capex budgeting, forcing more conservative forecasts and potential pass-through to patients or payers.
Competitive consolidation (top players ~40% of diagnostic volumes, 2024) and digital entrants growing double‑digits threaten pricing and volumes. Inflation (IPCA ~4.2% 2024) and FX volatility raise input and capex costs; household consumption slowed to ~1.5% (2024), lowering elective demand. Cyber risks high (IBM breach cost $11.45M, 2024) and LGPD fines up to 2%/BRL50M increase compliance burden.
| Threat | Metric (2024) |
|---|---|
| Consolidation | Top players ~40% |
| Inflation | IPCA ~4.2% |
| Consumption | Household +1.5% |
| Cyber | Avg breach $11.45M |
| Regulatory | LGPD 2%/BRL50M |


