
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
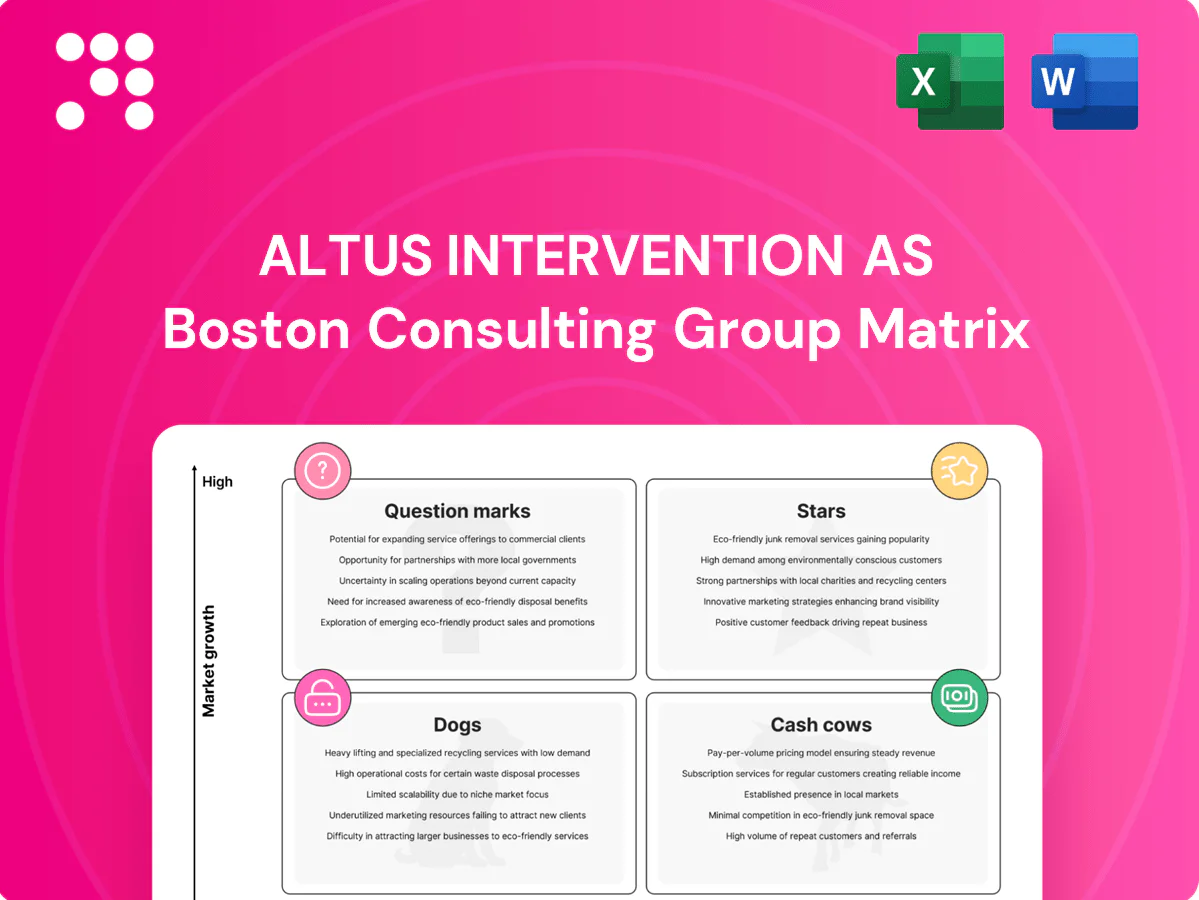
Altus Intervention’s quick BCG snapshot teases where its products sit—winners, cash generators, and underperformers—but the full picture is where the decisions get made. Buy the complete BCG Matrix to see quadrant-by-quadrant placements, data-backed moves, and practical strategies tailored to this company. Purchase now for a ready-to-use Word report plus a high-level Excel summary and act with confidence.
Altus is the go-to for electric-line interventions in key offshore basins, leveraging a strong installed base and high repeat-work rates. The market continues expanding as operators press more production from existing wells, keeping demand for e-line services robust. The business consumes cash for technology, crews, and uptime but delivers returns that match investment. Ongoing capacity, talent, and rapid mobilization are decisive competitive advantages.
Proprietary downhole tractor and mechanical tools position Altus as a Star by unlocking depths and sidetracks others cannot reach, supporting pricing power. As of 2024 demand for interventions on complex, aging wells has increased, expanding this niche. Continued R&D and field support are required to retain the technical edge; targeted investment will convert rivals’ rental usage into Altus-standard kits.
Integrated diagnostics, intervention and post-job optimization are enabling Altus Intervention to land larger multi-well packages by demonstrating measurable uplift to operators through repeatable case studies and performance tracking. Operators increasingly demand quantifiable KPIs and Altus’s analytics layer proves incremental production gains and reduced downtime. Growth in contract value is brisk but delivery remains engineering‑intensive, so funding the analytics and case‑study engine accelerates scalable wins and ROI.
Remote real-time operations centers cut offshore headcount and speed decisions, with operators reporting decision-cycle reductions and efficiency gains; global adoption climbed ~18% in 2024 driven by safety and OPEX pressure. Implementation requires platform, cybersecurity, and training capex, but client stickiness and multi-year usage agreements raise lifetime revenue and offset upfront spend.
Teaming on vessel-based subsea light well interventions unlocks high-value deepwater campaigns as operators defer new drilling, driving spare-capacity demand; 2024 vessel utilization for specialized intervention units rose above 70% in key basins, keeping campaign dayrates and margins elevated. Focus on fleet access, standardized spreads, and rapid turnarounds to capture margin-rich work.
Altus’s Stars: proprietary downhole tractors, integrated diagnostics and real‑time ops drove strong 2024 demand in complex aging wells, converting rentals to kit-based premium work. Remote centers lifted operator stickiness while vessel-based campaigns saw >70% specialized-unit utilization. Adoption of remote ops grew ~18% in 2024; adopters report up to 30% fewer offshore roles.
| Metric | 2024 |
|---|---|
| Remote ops adoption | ~18% |
| Vessel unit utilization | >70% |
| Offshore roles reduction | up to 30% |
 Detailed Word Document
In-depth BCG review of Altus Intervention's portfolio, spotlighting Stars, Cash Cows, Question Marks and Dogs with clear investment actions.

 Customizable Excel Spreadsheet
One-page BCG Matrix placing each Altus Intervention business unit, easing portfolio decisions for busy execs.
Routine slickline and mechanical services are mature, essential offerings for Altus Intervention AS with low market growth but high share, booked steadily into 2024. Crews and kits run efficiently—utilization around 80% in 2024—and operational EBITDA margins near 22%. Minimal promotion is required; management should focus on utilization optimization. Milk with strict process rigor and selective price discipline to sustain cash generation.
Casing/cement evaluation, leak detection and integrity checks remain must-do work in mature fields; the well-intervention market stayed flat in 2024 with firms targeting >95% integrity uptime to avoid costly shutdowns. Altus Intervention AS leverages long-standing customer playbooks and trusted relationships to win repeat work, focusing on quality, automated reporting and fleet utilization to keep trucks rolling and maximize recurring service revenue.
Standard downhole tool rental portfolio generates steady cash: repeat rentals account for roughly 60%+ of bookings with gross yields typically 40–55% when managed tightly. Growth is limited but cash flow reliability is high, driven by inventory turns of about 6–8x/year and industry non-productive time below 2%. Optimize maintenance cycles and retire low-turn assets to preserve margins. Tight fleet management keeps ROIC strong for cash cows.
Long-standing North Sea framework agreements and MSAs deliver predictable volumes and strong cash generation for Altus Intervention AS, with modest market growth but high entry barriers preserving share; operations are admin-light, revenue steady, focus on guarding service levels and negotiating CPI-linked pass-throughs while keeping renewal pipelines warm.
Production logging and routine surveillance are cash cows for Altus Intervention AS: in 2024 PLT underpins steady field management with high switching costs and proven methods, delivering predictable margins rather than growth glamour. Standardize workflows, bundle quick-win interventions to increase utilization, and bank the cash.
Routine slickline/mechanical services delivered 2024 utilization ~80% and operational EBITDA ~22%. Rentals: >60% repeat bookings, gross yields 40–55%, inventory turns 6–8x, NPT <2%. Frameworks provided stable volumes; production logging and surveillance remained predictable cash generators. Focus: utilization, maintenance, retire low-turn assets, secure CPI-linked pass-throughs.
| Metric | 2024 | Note |
|---|---|---|
| Utilization | ~80% | Crews/kits |
| EBITDA | ~22% | Operational |
| Repeat bookings | >60% | Rentals |
| Gross yield | 40–55% | Tool rentals |
| Turns | 6–8x/yr | Inventory |
| NPT | <2% | Industry |
The Altus Intervention AS BCG Matrix you’re previewing is the exact file you’ll receive after purchase. No watermarks, no placeholders—just a polished, analysis-ready report crafted for strategic decision-making. Buy once and download immediately; it’s ready to edit, print, or present to stakeholders. What you see is what you get—no surprises, just clarity.
Undifferentiated onshore tool rentals operate in price-led, crowded markets with fickle demand, leaving cash tied in idle inventory and driving negative working capital cycles. These assets sit squarely in the BCG Dogs quadrant: low growth, low share, where turnarounds are costly and often unsustained. Management should prune SKUs, exit unprofitable basins, or restrict bundling to cases linked with higher-value intervention work.
Legacy software modules tied to old workflows have outdated interfaces and limited integrations, driving 25% lower adoption and contributing under 10% of product revenue while consuming 30–40% of support costs per 2024 industry benchmarks. Clients refuse to pay for clunky add-ons, so revenue trickles while maintenance (~€1.2M/year) lingers. Sunset or fold these features into the core digital stack to stop carrying dead weight.
Obsolete mechanical tools chew maintenance budgets and fail more often, with 2024 industry benchmarks showing legacy fleets incur roughly 15–25% higher maintenance spend and deliver 10–20% lower utilization versus modern rigs. They lose tenders and drag group utilization down, becoming a cash trap that ties working capital and depresses returns. Decommission, salvage, and redeploy proceeds into fast-moving SKUs to lift utilization and ROI.
Small, stand-alone call-outs for Altus Intervention sit in the Dogs quadrant: one-off jobs at distance burn travel and standby time, eroding unit economics and turning apparent dayrates into low or negative net margins after logistics. Low repeat business and limited market growth make these engagements strategic drainers; tighten acceptance criteria or enforce minimums, or pass on them to protect fleet utilization and margins.
Low-volume geographies with heavy local barriers drain resources: high compliance overheads and permitting tie up people and capital for marginal revenues, often producing unstable, single-digit utilization and break-even margins in 2024; no scale means fixed costs dominate and demand remains volatile. Divest or pursue partner-light strategies unless a larger anchor client materializes to justify fixed commitments.
Low-growth, low-share assets (onshore rentals, legacy software, obsolete tools, one-off call-outs, low-volume geographies) cost more to run than they return: 2024 benchmarks show ~8% revenue share, +30–40% upkeep on legacy modules (€1.2M/year support), 10–20% lower utilization and negative net margins on distant call-outs. Prune, sunset, divest or enforce minimums to stop cash bleed.
| Item | 2024 Metric |
|---|---|
| Revenue share | ~8% |
| Legacy support | €1.2M/year (+30–40% cost) |
| Utilization hit | −10–20% |
| Call-out margins | Negative/low |
As of 2024, global CCUS installed capacity is ~50 MtCO2/yr with a project pipeline >200 Mtpa to 2030, making well integrity assurance a fast-growing but early-stage market. Altus has proven O&G remediation know-how but limited CCUS share; qualification costs often exceed hundreds of thousands USD per well and pricing remains uncertain. Recommend selective pilots and development of standardized tools that can port back to O&G.
Geothermal well intervention sits in a hot market—global geothermal capacity was ~16.9 GW in 2023 and drilling costs per well typically range $3–10M—yet service standards and access remain fragmented. Altus Intervention has the capable skill set but low brand presence today; unit economics can be attractive with partner-backed contracts and risk-sharing. Pilot in one or two high-potential hubs (e.g., Nevada, Iceland) and productize a standardized geothermal intervention kit to scale.
Autonomous downhole conveyance can cut crew size and exposure by up to 50% in pilot projects, but industry adoption remains steep with commercial deployments still under 5% of wells globally in 2024. Development costs commonly exceed $8–12m per platform and payback typically requires scale of hundreds of jobs or anchor-client commitments. Altus’ field data from 1,200+ interventions informs practical design; co-developing with anchor clients, using stage-gate R&D and monitoring regulatory approvals will de-risk rollout.
AI-driven production optimization and digital twins sit as Question Marks for Altus Intervention: operators demand predictive (not just diagnostic) solutions and predictive maintenance can cut costs 10–40% per McKinsey; market shows high growth (CAGR ~20%+), but Altus has low current share amid many competitors and evolving standards.
Subsea P&A and late-life decommissioning is a question mark for Altus Intervention AS: demand is ramping but procurement remains lumpy and technology needs vary by field, so upfront cash burn is required to win credibility.
Altus can leverage its intervention DNA to build case studies, align with vessel partners, and pursue multi-field packages to convert a nascent market share into scalable revenue.
Question Marks: CCUS (50 MtCO2/yr global capacity, >200 Mtpa pipeline to 2030) and geothermal (16.9 GW global 2023) are high-growth but early for Altus; autonomous conveyance (<5% deployment 2024) and AI (CAGR ~20%+) need capital and anchor clients; subsea P&A demand is lumpy with high upfront burn.
| Market | 2024 stat | Altus position | Action |
|---|---|---|---|
| CCUS | 50 MtCO2/yr; >200 Mtpa pipeline | low share | selective pilots |
| Geothermal | 16.9 GW (2023) | capable, low presence | hub pilots, productize |


