
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
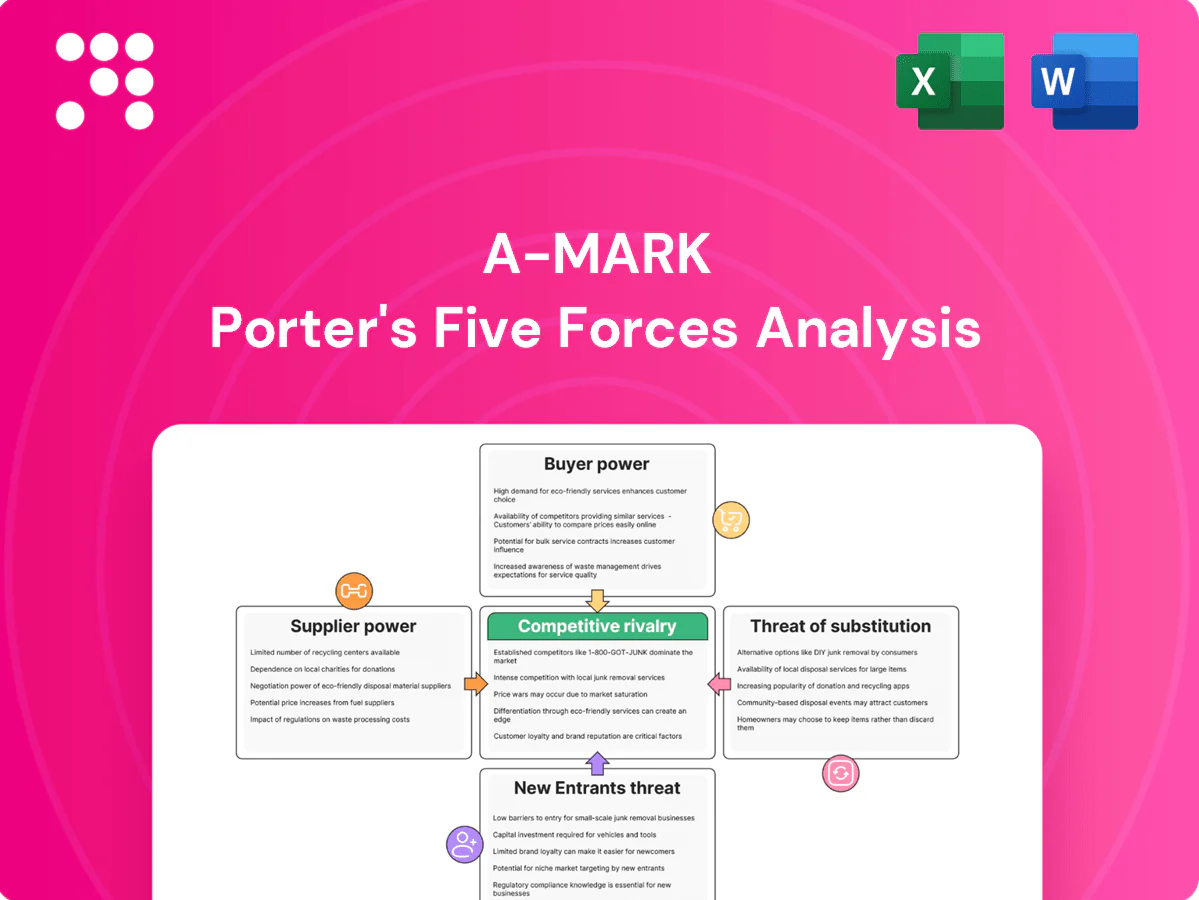
A-Mark’s Porter's Five Forces snapshot highlights moderate supplier power, high buyer price sensitivity, low substitute threat, and intense rivalry among bullion dealers. Regulatory and entry barriers shape profitability and margins. This brief preview outlines key pressures and strategic implications. Unlock the full Porter's Five Forces Analysis for detailed force ratings, visuals, and actionable insights.
A-Mark depends on a limited set of sovereign mints (notably the U.S. Mint and Royal Canadian Mint) and LBMA-accredited refiners that control iconic coins and purity standards, concentrating supply power. This concentration raises supplier leverage over allocations, premiums and commercial terms, even as preferred-dealer status and multi-sourcing mitigate but do not eliminate the dependence. Disruptions at these suppliers can rapidly tighten A-Mark inventory and widen retail–wholesale spreads.
Sovereign mints such as the U.S. Mint and Royal Canadian Mint control production schedules, product mixes and allocation formulas that can ration supply in high-demand periods. Suppliers raised fabrication premiums in 2024, compressing distributor margins and pressuring spreads. A-Mark offsets volatility with forward commitments and strategic inventory positioning, yet upstream pricing power and brand-specific coin scarcity maintain supplier leverage. Limited substitution for flagship coins sustains that influence.
Spot metal costs are largely pass-through to customers, while fabrication premiums and logistics are retained by suppliers and not fully passed through; when market volatility spikes suppliers can reprice terms and premiums faster than distributors can reset multi-channel pricing, temporarily increasing supplier power. Hedging reduces exposure but cannot eliminate basis mismatches and premium/logistics risk.
Approved vaults, assay labs, and insured transport providers remain specialized and limited, concentrating leverage among a few gateway nodes; dependence on these third parties gives suppliers pricing and priority power that can spike rapidly if capacity tightens. A-Mark’s integrated logistics reduce exposure but still interfaces with external custodians and carriers, creating chokepoints where a single bottleneck can abruptly elevate supplier bargaining power. Recent industry reporting in 2024 highlighted ongoing consolidation among custodial vaults, reinforcing this concentrated supply-side risk.
Compliance and ESG constraints (responsible sourcing, KYC/AML, sanctions screening) materially narrow eligible supplier pools; FATF's 40 recommendations (2024) underpin tougher due diligence that favors accredited suppliers who command price and contractual advantages. A-Mark’s scale and compliance infrastructure improve access but do not eliminate scarcity premiums, and further regulatory tightening would likely boost supplier power.
A-Mark faces concentrated supplier power from sovereign mints and LBMA refiners, giving suppliers leverage over allocations, premiums and terms. 2024 saw rising fabrication premiums and custodial consolidation, tightening allocations and widening retail–wholesale spreads despite A-Mark’s hedging and integrated logistics. Compliance rules further narrow suppliers, sustaining scarcity premiums.
| Metric | 2024 Signal |
|---|---|
| Fabrication premiums | Increased (industry reports 2024) |
| Custodial concentration | Higher consolidation (2024) |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks tailored to A‑Mark, with detailed evaluation of supplier and buyer power, substitutes, rivalry, and entry barriers; identifies disruptive threats and strategic levers to protect margins and market share, delivered in fully editable Word format for decks, plans, or reports.

 Customizable Excel Spreadsheet
A concise, one-sheet Porter's Five Forces for A‑Mark that instantly relieves decision paralysis by visualizing competitive pressures and priority actions; ready to drop into pitch decks or boardroom slides.
High price transparency — with spot quotes and premiums posted in real time on platforms like Kitco and dealers in 2024 — lets buyers compare and arbitrage spreads often below 1%, compressing margins. Buyers routinely exploit sub-1% spread differences, increasing pressure on dealer premiums and execution fees. A-Mark offsets this by offering deep inventory and reliable trade execution, but transparency structurally raises buyer leverage.
Wholesale and retail customers can pivot among dealers and e-commerce sites with minimal friction, as shipping, live pricing and payment rails are industry-standard; A-Mark (NASDAQ: AMRK) offsets this by offering financing, vaulted storage and liquidity services that increase client stickiness. Despite these services, baseline switching costs remain low, keeping buyer bargaining power elevated in 2024.
Institutions, large dealers, and OEMs extract tighter spreads and priority allocations from A-Mark, leveraging steady order flow — A-Mark reported $5.74 billion revenue in 2024, underscoring scale that attracts large buyers. The firm routinely trades concessions for wallet share and multi-year contracts to lock in volume. Concentration of top accounts materially amplifies buyer bargaining power, pressuring margins on headline volumes.
During risk-off surges buyers exhibit urgency that reduces price sensitivity and eases buyer power; 2024 saw the VIX average near 16, reflecting intermittent risk-off episodes that tightened supply willingness. In calmer 2024 quarters, buyers pushed for lower premiums and extended terms, and A-Mark’s diversified channels (wholesale, retail, B2B) smooth but cannot fully offset these shifts. Seasonality and macro sentiment swing leverage back to buyers in normal times.
Customers can pivot to ETFs, futures, or tokenized metals for exposure without handling physical, and ready alternatives compress A-Mark’s leverage over premiums and storage fees; SPDR Gold Shares (GLD) held about 60 billion USD AUM in 2024 while COMEX gold futures open interest regularly exceeded 600k contracts, keeping financial substitutes compelling despite A-Mark’s physical deliverability, product variety, and custody services.
High price transparency and low switching costs in 2024 give customers strong leverage, compressing premiums despite A-Mark’s scale. Large buyers extract tighter spreads; A-Mark reported $5.74B revenue in 2024 and concedes volume discounts. Financial substitutes (GLD ~60B AUM; COMEX OI >600k) and intermittent risk-off (VIX ~16) keep buyer power elevated.
| Metric | 2024 |
|---|---|
| A-Mark revenue | $5.74B |
| GLD AUM | $60B |
| COMEX OI | >600k contracts |
| VIX average | ~16 |
This preview shows A‑Mark's Porter’s Five Forces Analysis and is the exact document you’ll receive immediately after purchase—no placeholders or samples. The report is professionally formatted, complete, and ready for download and use the moment payment is processed. No surprises; the file available to you post‑purchase is precisely this one.
Physical precious metals distribution features many national and online dealers, driving tight dealer spreads typically in the 0.5–1.5% range and intense marketing and fulfillment speed battles. A-Mark (AMRK) leverages an integrated platform and scale—fiscal 2023 net sales were about $4.6 billion—to sustain margins, but rivalry remains vigorous. Differentiation increasingly depends on unique product access and deeper service offerings.
Bullion coins and bars are highly standardized, so differentiation is limited and commoditization drives intense price-based competition.
That dynamic pushed wholesale spreads on core 1 oz gold and silver SKUs sharply lower in 2024, squeezing margins and increasing pressure on throughput and scale.
Exclusive mint agreements and vintage/numismatic inventory provide higher-margin pockets—A-Mark leverages such niches to offset compression.
Digital acquisition, UX, and real-time pricing engines are table stakes as competitors pour resources into SEO, loyalty programs and instant financing to capture share; global e-commerce sales reached 5.7 trillion USD in 2023. A-Mark’s online channels and APIs support scale, yet low switching costs keep customers fluid. Speed and reliability remain the decisive rivalry factors.
During demand spikes capacity constraints, not price, determine who captures volume, forcing buyers to source from available suppliers; in lulls competitors increasingly discount to sustain throughput, amplifying margin pressure and strategic maneuvers across cycles. Firms with diversified revenue streams such as storage and lending sustain volumes and margins better during price wars, reducing vulnerability to short-term price swings.
Physical PM distribution is crowded with tight dealer spreads (0.5–1.5%) and heavy price/fulfillment competition; A-Mark uses scale and unique inventory to protect margins (FY2023 net sales ~$4.6B). Commoditization of coins/bars intensifies price rivalry; wholesale spreads fell sharply in 2024, pressuring throughput. Digital UX, APIs and financing are table stakes; A-Mark reported ~$1.2B 2024 YTD net sales.
| Metric | Value |
|---|---|
| FY2023 Net Sales (A-Mark) | $4.6B |
| 2024 YTD Net Sales (A-Mark) | $1.2B |
| Typical Dealer Spreads | 0.5–1.5% |
| Global e‑commerce (2023) | $5.7T |
Gold and silver ETFs offer low-cost, liquid exposure without storage or shipping, with over 200 global ETPs and expense ratios typically 0.12–0.50%; physically backed gold ETFs held roughly 3,500–4,000 tonnes (≈$200–$250bn) by end-2024. These products undercut physical distribution for investment-only buyers, while A-Mark differentiates via deliverable inventory and logistics; for pure price exposure, ETFs remain strong substitutes.
Derivatives offer leverage, deep liquidity and tight pricing—CME Group average daily volume reached about 22.8 million contracts in 2024—making futures attractive versus physical procurement for institutional clients. Substitution risk rises when carry costs widen (spot-forward spreads in oil spiked >5% annualized in some 2024 months), and physical delivery value-adds like quality and storage only partially offset this for hedgers.
Blockchain-based gold claims promise fractional ownership and easy transfers; tokenized gold holdings remain small (low single-digit billions) versus above-ground stock ~201,000 tonnes (~$12–13 trillion in 2024), so substitution is nascent. If trust and liquidity deepen, tokenized instruments could displace some coin/bar demand. A-Mark can engage via custody and distribution partnerships. Standards' maturation could elevate the threat.
Alternative stores of value—cryptocurrencies, TIPS and high-yield cash—compete with physical metals for inflation hedging; crypto market cap exceeded 1 trillion USD in 2024, TIPS real yields moved into roughly 0.5–1.0% territory and cash yields averaged about 4–5%, so when real yields rise or crypto rallies physical demand softens. Diversified mandates amplify substitution; A-Mark’s multi-metal breadth helps but cross-asset flows remain a headwind.
In industrial uses, platinum-group metals are swapped based on price/performance, and technology shifts — notably autocatalysts and electronics — change metal-mix demand; global EVs reached about 16% of new car sales in 2024 (IEA), redirecting catalyst volumes away from palladium-rich SKUs. Substitutions can move double-digit percentages of volumes across SKUs; A-Mark manages exposure by adjusting inventory mix and sourcing, but substitution risk remains material.
Gold/silver ETFs (3,500–4,000t held end‑2024; fees 0.12–0.50%) and low-cost ETFs are main substitutes for investors. Futures (CME ADV ≈22.8m contracts 2024) provide leverage/liquidity; tokenized gold remains small (low single‑digit $bn). Crypto >1T, TIPS real yields ~0.5–1%, cash ~4–5% (2024) and EVs ~16% new car sales (2024) drive cross-asset and industrial substitution.
| Instrument | 2024 Metric |
|---|---|
| ETFs | 3,500–4,000t; 0.12–0.50% fees |
| Futures | CME ADV ≈22.8m contracts |
| Crypto | Market cap >1T |
Scale and capital barriers: A-Mark–style wholesalers require significant working capital to hold volatile inventory and meet allocations, often running into hundreds of millions of dollars in inventory exposure in 2024. New entrants face high hedging, insurance and warehousing costs that erode margins, while scale unlocks tighter bid-ask spreads and priority access to supplier allocations. This capital intensity deters small newcomers.
KYC/AML, sanctions screening, tax and evolving responsible-sourcing rules (eg EU CSDDD) plus US BOI reporting effective 2024 raise complexity; FATF estimates $800 billion–$2 trillion laundered annually, driving stricter controls. Certification with mints and vaults adds time and incremental costs. Compliance failures can be existential for dealers; robust, mature programs therefore create a high barrier that advantages incumbents like A-Mark.
As of 2024, sovereign mints and top refiners prioritize established, compliant, high-volume partners with audited flows and robust AML controls, making initial allocations and exclusive SKUs hard for newcomers to secure. Relationship moats take years to replicate, so entrants are often relegated to secondary supply channels at weaker terms and higher premiums.
Operational know-how—live pricing, risk management, logistics and authentication—creates a high barrier: errors in hedging or fulfillment can wipe out bullion dealer margins, and A-Mark’s FY2024 revenue of $6.7 billion underscores its scale and integrated capabilities that raise the bar for newcomers; learning curves and trust-building slow entry.
Tech lowers storefront friction: turnkey platforms (Shopify: >4.7M merchants in 2024) and headless stacks make site launches trivial, modestly cutting barriers. Yet paid traffic costs, marketplace liquidity and fulfillment excellence (scale-driven) keep meaningful moat for incumbents; most entrants target niches or compete on price. Net threat: moderate, not trivial.
Scale and capital intensity (A-Mark FY2024 revenue 6.7B; dealers hold hundreds of millions in inventory) plus 2024 compliance complexity (FATF $800B–$2T illicit flows; BOI/CSDDD) and supplier allocation advantages make entry difficult. Operational risks in hedging, authentication and logistics amplify barriers. Tech lowers storefront friction (Shopify >4.7M merchants) but customer acquisition, liquidity and fulfillment keep threat moderate.
| Barrier | 2024 datapoint |
|---|---|
| Capital | Inventory exposure: hundreds of millions |
| Compliance | FATF est. $800B–$2T; BOI/CSDDD enforcement |
| Supplier access | Preferred allocations to vetted partners |
| Tech | Shopify >4.7M merchants; lowers launch cost |


