
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
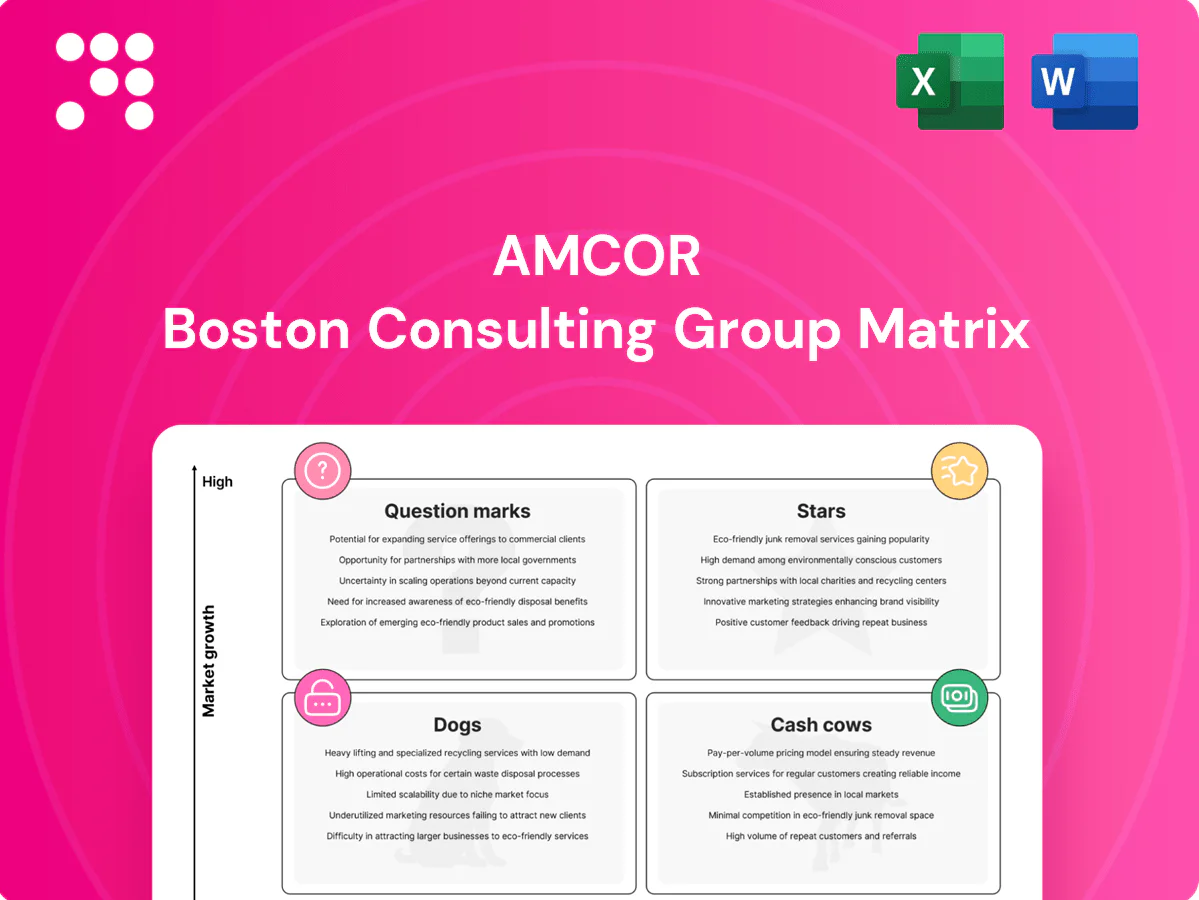
Want a straight, practical view of where Amcor’s products sit—Stars, Cash Cows, Dogs, or Question Marks? This preview scratches the surface; buy the full BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and strategic moves tailored to Amcor’s market reality. You’ll get a detailed Word report plus a high-level Excel summary—ready to present and act on. Purchase now and skip the guesswork; get clear priorities for investment and divestment fast.
High-growth, high-share: mono-material and recyclable pouches for food and personal care are Amcor’s star segment, with global flexible packaging volumes up about 5% in 2024 and demand for mono-material solutions accelerating. Amcor leads specs and has secured major brand conversions including Nestlé and Unilever, driving unit share gains. The category scales fast but consumes cash for capacity, testing and customer qualification; Amcor raised capex ~20% in 2024 to expand lines. Keep feeding it — this is the future cash cow.
Healthcare sterile packs sit in Stars: medical and pharma packaging is highly regulated with rising demand—global sterile packaging market ~ $10.8B in 2024 and projected CAGR ~7.3% to 2030—supported by sticky, long-duration contracts. Amcor holds a strong share (roughly mid‑single digits to low‑teens percent globally) and continues R&D on barrier films and sterilization-ready laminates. Growth is robust but validation cycles and audits add millions in upfront cost and lengthen payback. Invest to lock in long-term platform wins.
Beverage brands increasingly demand lighter, more recyclable PET bottles, and Amcor’s design IP combined with operations in over 40 countries gives it a clear commercial edge; as brand adoption rises, volumes tend to follow. Tooling, trials and regional certifications absorb significant upfront cash today, pressuring near-term margins. Leadership in lightweight PET compounds over time through scale, repeatable designs and global rollout efficiencies.
Stars: High-barrier recyclable films — Amcor leads with next-gen barrier films that fit curbside and closed-loop systems, backed by a 2024 pipeline and strategic partnerships placing it ahead in a market growing ~12% CAGR (2024–30); pilots and line changeovers run into multi‑million-dollar bills, so maintain investment while rivals scale up.
Premium closures & lids are Stars in Amcor’s BCG matrix: smart, tethered, lightweight designs align with 2024 EU tethered-cap mandates and brand upscaling, keeping growth tailwinds intact and strong share with multinationals; upfront tooling and multi-plant rollouts (typical line tooling ~$1–5m) require capex but margin uplift and customer stickiness justify the spend.
Stars: mono-material pouches (flexible volumes +5% in 2024) and sterile healthcare packs (market ~$10.8B in 2024) drive high growth but demand elevated capex (+~20% in 2024) for lines and validation; high-barrier films (~12% CAGR 2024–30) and premium closures (tooling $1–5m/line) need continued investment to convert scale into margin.
| Segment | 2024 Metric | Capex | Edge |
|---|---|---|---|
| Mono pouches | Volumes +5% | Lines | Brand wins |
| Healthcare | $10.8B market | Validation cost | Sticky contracts |
| Barrier films | ~12% CAGR | Multi‑M per change | R&D |
 Detailed Word Document
Concise Amcor BCG Matrix overview: quadrant analysis, investment priorities, and strategic implications for each business unit.

 Customizable Excel Spreadsheet
One-page Amcor BCG Matrix placing each business unit in a quadrant, simplifying portfolio decisions for speedy C-suite action.
Snack flex packs are a mature, massive cash cow for Amcor, with entrenched contracts across leading CPGs and stable, high-throughput lines that drive repeat orders and low promotional spend. In 2024 Amcor maintained focus on uptime and yield optimization to protect margins and service levels. The strategy is to milk operational efficiency and responsive service to keep steady cash flow.
Everyday pharma blister delivers steady, predictable demand for established tablet and OTC formats, making it a classic cash cow in Amcor’s BCG matrix. Qualification moats—regulatory approvals and validated supply chains—protect share and slow competitive shifts. Operations are cash generative with modest capex, while focus in 2024 remains on compliance, reducing scrap and shortening cycle time to improve margins. Continuous yield and cycle improvements sustain free cash flow.
Personal care tubes—mainstream skincare and hygiene formats—deliver steady demand and low volatility; in 2024 Amcor’s global flexible-packaging scale (around 190 sites) drives cost and service advantages, making tubes a reliable cash generator rather than a high-growth segment.
Amcor specialty cartons function as cash cows: well‑penetrated end markets with repeatable jobs and largely depreciated equipment, so conversion margins compound; promotional spend is minimal, so incremental profit comes from efficiency; focus capex on throughput and waste reduction to boost returns—Amcor reported ~US$11.3bn in FY2024 sales, underscoring scale advantages.
Snack flex packs, standard beverage PET, everyday pharma blister, personal care tubes and specialty cartons are Amcor cash cows in 2024, generating steady free cash flow from high-volume, low-promo contracts and depreciated assets; Amcor reported ~US$11.3bn sales in FY2024. Focus is on uptime, yield, long-term resin/logistics contracts and compliance to protect mid-teens plant EBITDA and repeatable margins.
| Segment | 2024 status | Key metric |
|---|---|---|
| Snack flex packs | Mature, high throughput | Stable orders, low promo |
| PET beverage | Low-single-digit growth | ~1–3% p.a.; mid-teens plant EBITDA |
| Pharma blister | Predictable, regulated | Low capex, high qualification moat |
The file you’re previewing is the exact BCG Matrix report you’ll receive after purchase. No watermarks, no demo text—just a fully formatted, ready-to-use strategic tool. Crafted by strategy pros for clarity and action, it’s immediately downloadable once you buy. Edit, print, or present straight away—no surprises, no extra steps.
Legacy multi-layer non-recyclables are Dogs in Amcor’s BCG view: low-growth, margin-pressure segments facing regulatory phase-outs in key markets and accelerating customer spec shifts toward mono-materials and recyclability.
Share is eroding as major FMCG customers tighten sustainability specs; cash sits idle in aging lines with limited throughput and declining ROI versus recyclable alternatives.
Plan a structured exit or selective retrofit: retire sites where retrofit payback exceeds capital cost, and only pursue line upgrades where modelled ROI and contract commitments justify CAPEX.
Price-led rigid container segments suffer single-digit EBITDA margins and overcapacity in 2024, with too many players compressing pricing power. Low-share pockets dilute Amcor’s blended profitability, shaving hundreds of basis points from segment returns. Turnarounds are costly and rarely durable; pruning SKUs or divesting sites that fail to clear mid-teens ROIC hurdle rates is the pragmatic response.
Print-heavy cartons sit in declining end categories in 2024, pulling volumes down and leaving low-utilization, choppy production runs with meagre margins. Cash is trapped in prolonged make-ready and numerous small runs, eroding working capital. Recommend winding down unprofitable SKUs or migrating customers to scalable formats and higher-run digital/gravure mixes to restore throughput and margin.
Non-core closures are low-volume, fussy parts that don’t scale; Amcor reported revenue of US$11.3bn in FY2024, but these SKUs sit in flat, price-sensitive segments where engineering hours outstrip returns. Prioritize sunset or bundle into broader supply deals only if margin improves; otherwise divest to cut SKU complexity and cost.
Dogs: Legacy PVC-based films face shrinking demand from regulatory and brand pressure, with EU restrictions on intentionally added microplastics (June 2024) intensifying compliance costs; market share no longer justifies the compliance drag, margins are at best break-even after operational headaches, so exit and redeploy capital to sustainable lines.
Legacy non-recyclable lines are Dogs: low-growth, margin-compressed segments with eroding share as customers shift to mono-materials. Cash tied in low-utilization lines yields single-digit EBITDA and sub-10% ROIC vs Amcor’s mid-teens target; recommend structured exit or selective retrofit where ROI >15%.
| Metric | Value |
|---|---|
| Amcor FY2024 revenue | US$11.3bn |
| Segment EBITDA | ~5% |
| Utilization | ~60% |
| ROIC hurdle | 15% |
Question Marks: Paper-based flex alternatives show high interest in 2024 but remain early and fragmented, holding low share today (under 5%) with many pilots and few full-scale wins.
Commercialisation requires targeted investment in coating technology and sealing performance to meet barrier and machinability needs and reduce conversion losses.
If barrier and machinability crack, the segment can flip to Star, unlocking higher-margin growth and premium sustainable-packaging demand.
Compostable films are a Question Mark for Amcor: rapid buzz and pilot programs have driven a global compostable packaging market estimated at ~USD 2.3 billion in 2023 with ~8% CAGR, but standards remain uneven and specs vary by region. Current share is small—pilot volumes under 1% of mainstream film sales—and demand is concentrated in pockets where municipal composting exists. Costs are materially higher and margins thin today, so Amcor should bet selectively where policy mandates and large retailers align.
Reusable/returnable packaging pilots with retailers and DTC brands are growing from a tiny base, still accounting for under 1% of FMCG packaging volumes in 2024, per industry reviews.
Operations and reverse logistics remain complex and costly, with pilots reporting up to 20–30% higher unit logistics costs versus single‑use systems.
Design, tracking and infrastructure drive upfront cash burn; many pilots require capital paybacks beyond three years unless scaled.
Amcor should double down only where partners commit meaningful volume and multi‑year contracts to achieve unit-cost parity.
Digital print customization sits in Question Marks: personalization and short runs are growing (industry reports show double-digit CAGR into 2024) but remain a small share of total packaging volume, not yet scaled to mainstream production.
Amcor’s digital share is modest compared with nimble niche players that dominate short-run flexibles and labels; Amcor needs targeted capex and workflow software to reach competitive speed and unit cost.
Strategically, Amcor must either invest to secure anchor customers and scale digitally (capex + ERP/automation projects) or exit the segment to avoid margin erosion.
Smart/traceable packaging for sensors, QR and anti-counterfeit targeting pharma and premium goods is a Question Mark: growth potential is real given WHO’s finding that one in ten medical products in low- and middle-income countries is substandard or falsified, yet Amcor’s current share in smart solutions remains light; tech integration and validation burn cash early, so targeted bets tied to compliance or value-based pricing are required.
Question Marks: multiple high‑interest segments (paper‑based flex <5% share, compostable market ~USD 2.3bn in 2023, ~8% CAGR, compostables <1% volumes, reusable <1% volumes, digital double‑digit CAGR into 2024, logistics +20–30% pilot costs, smart packaging demand driven by WHO pharma risk) — selective, partner‑backed investments only; otherwise exit.
| Segment | 2023/24 metric |
|---|---|
| Compostable | USD 2.3bn 2023; <1% volumes |
| Reusable | <1% volumes; +20–30% logistics |
| Digital | DD CAGR 2024; small share |


