
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Arcosa's Porter’s Five Forces snapshot highlights supplier leverage in materials, moderate buyer power, intense rivalry across infrastructure segments, meaningful entry barriers, and limited substitutes. This brief overview flags the strategic pressures shaping margins and growth. Unlock the full Porter's Five Forces Analysis to explore Arcosa’s competitive dynamics, market pressures, and strategic advantages in detail.
Arcosa depends on cement, aggregates, steel plate and specialty inputs that are regionally concentrated, making local quarry proximity and steel mill capacity key determinants of supply and price. US steel capacity utilization averaged about 80% in 2024, tightening availability and upward price pressure. Multi-sourcing reduces supplier power, but rail/truck logistics and haul distances restrict rapid switching. Long-term supply agreements partially stabilize input cost volatility.
Arcosa’s manufacturing is energy‑intensive: U.S. industrial electricity averaged about 8¢/kWh in 2024, diesel roughly $3.50–4.00/gal and Henry Hub natural gas near $3/MMBtu, making utilities and fuel major cost drivers; volatile carrier fuel surcharges and utility pass‑throughs are uneven, hedging and efficiency cut but do not eliminate exposure, and FERC and clean‑energy regulatory shifts can quickly change supplier leverage.
Engineered structures depend on certified steel plate and fabricated parts from a narrow pool of qualified suppliers, concentrating leverage among a few mills; in 2024 mill lead times commonly stretched to 12+ weeks in tight markets. Strict quality specs and mill qualification/testing protocols raise switching friction and can delay sourcing. Vendor development reduces dependence but typically requires 6–18 months to certify new suppliers, sustaining supplier bargaining power.
Environmental and safety compliance narrows Arcosa s supplier pool to certified vendors, and ESG traceability (recycled content, emissions) concentrates spend with a smaller set of qualified suppliers, increasing their bargaining power; audits and scorecards partly rebalance leverage.
Arcosa faces elevated supplier power from regionally concentrated cement, aggregates and steel where US steel capacity utilization averaged ~80% in 2024 and mill lead times often 12+ weeks, limiting rapid switching. Energy and transport costs are material—industrial electricity ~8¢/kWh, diesel $3.50–4.00/gal (2024)—and rail/truck concentration (Class I rail ~40% ton‑miles, trucking >70% value) tightens leverage. Long‑term contracts, multi‑sourcing and vendor qualification (6–18 months) partially mitigate but do not eliminate supplier bargaining strength.
| Metric | 2024 Value |
|---|---|
| US steel capacity utilization | ~80% |
| Typical steel lead times | 12+ weeks |
| Industrial electricity | ~8¢/kWh |
| Diesel | $3.50–4.00/gal |
| Vendor qualification | 6–18 months |
 Detailed Word Document
Concise Porter's Five Forces analysis tailored for Arcosa, uncovering competitive rivalry, supplier and buyer power, entry barriers, substitutes, and disruptive threats with strategic commentary and editable Word format for investor materials, internal strategy decks, or academic use.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces for Arcosa—quickly highlights competitive pressures and strategic risks so teams can make faster, data-driven decisions.
Departments of Transportation, utilities, EPCs and OEMs procure at scale through competitive bids and multi-year framework agreements, leveraging the IIJA's roughly 550 billion dollars of new infrastructure funding to time purchases and pressure pricing. Prequalification narrows the vendor pool, intensifying price competition among approved suppliers. Contractual penalties and strict SLAs shift additional negotiating power to buyers, often reducing supplier margins.
Construction and energy capex cycles concentrate buyer price sensitivity during downturns, with US construction spending around $1.8 trillion in 2023 (US Census Bureau), prompting stronger demands for discounts, indexation, and pass-through clauses. When demand softens, switching threats rise as buyers leverage alternative suppliers and lower-cost materials. Strong backlogs and public infrastructure funding can temporarily blunt buyer leverage.
Engineered products tied to codes and project specs create significant switching costs, since vendor changes typically require requalification and testing that can add 90–180 days and material schedule risk. Buyers therefore have limited day-to-day bargaining power despite competitive bids. Arcosa’s demonstrated project performance and industry certifications further insulate pricing and margins.
On-time delivery for time-critical projects often equals price in buyer priorities; reliable delivery secures repeat awards while delays trigger contract penalties and lost future orders.
Buyers quickly punish missed deadlines, amplifying their bargaining power, whereas strong logistics, dedicated field support and rapid troubleshooting can offset price pressure and preserve margins.
Poor service instantly increases buyer leverage, accelerating shift to alternative suppliers and shortening contract tenures.
Consolidation among utilities, EPCs and aggregates distributors has concentrated purchasing power, with large national contracts and bundled buys increasingly dictating terms in 2024. National agreements and volume discounts raise buyer leverage, though Arcosa's multi-segment offerings and cross-selling dilute pure price pressure. Depth of relationship and proven on-time performance remain decisive in retention and margin protection.
DOTs, utilities, EPCs and OEMs leverage IIJA's ~550 billion USD to push competitive, multi-year bids; 2023 US construction spend ~1.8 trillion USD amplifies price sensitivity. 2024 buyer consolidation raises national-contract leverage, but Arcosa's certifications, on-time delivery and cross-selling blunt margin erosion.
| Metric | Value |
|---|---|
| IIJA funding | ~550B USD |
| US construction 2023 | ~1.8T USD |
| Typical requalification | 90–180 days |
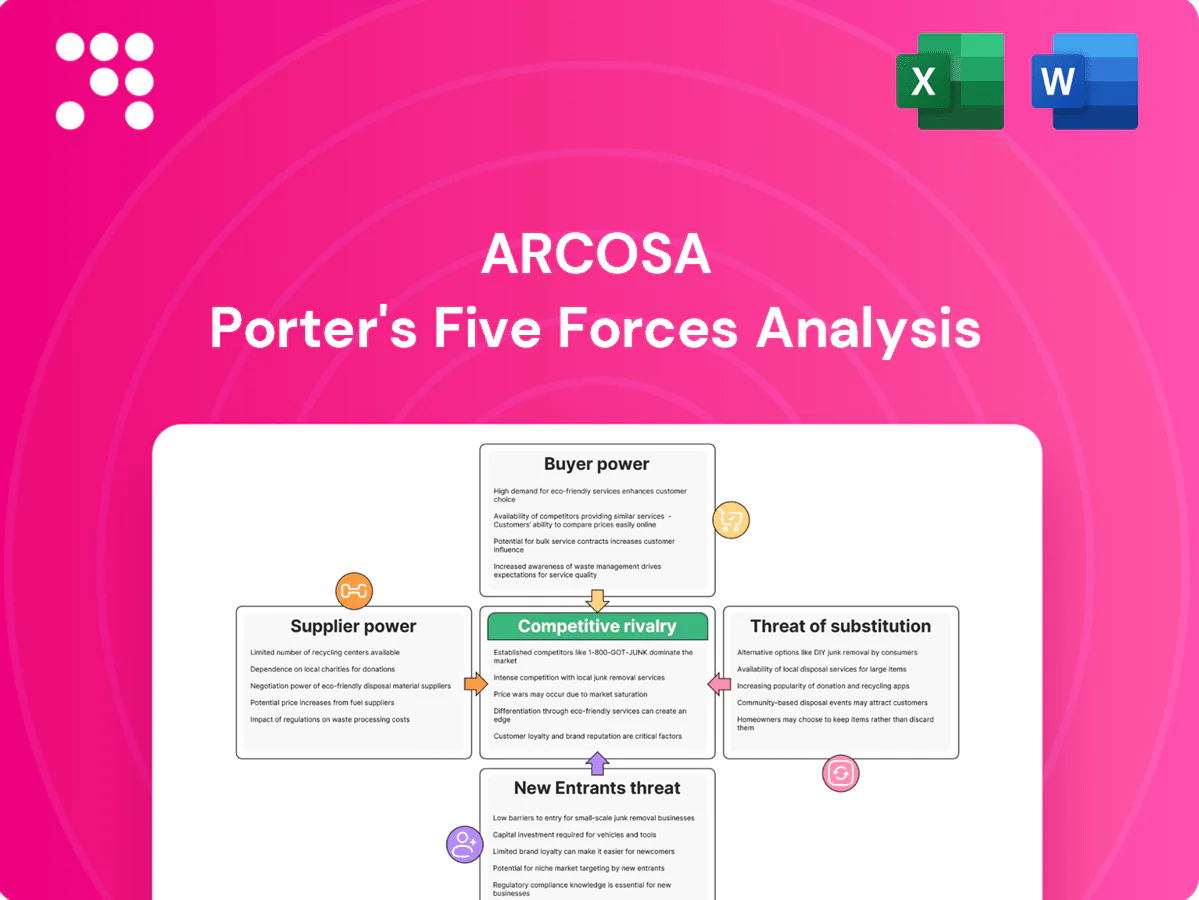
This preview shows the exact Arcosa Porter’s Five Forces analysis you'll receive immediately after purchase—no placeholders or mockups. The file is fully formatted and ready to download and use the moment you buy. You're looking at the final deliverable with professional sourcing and actionable insights.
Construction aggregates face intense local rivalry because freight economics typically limit profitable haul to roughly 20–40 miles, making proximity and quarry control decisive for share and pricing. Regional players use tactical pricing and service differentiation—rush delivery, blending—to protect margins. Large project pipelines can swing regional market share by 5–10% in a year, raising short-term pricing volatility.
Engineered-structures peers for Arcosa—wind towers, utility structures and related fabrications—face intense competition from capable domestic and international firms; U.S. wind additions in 2024 (~12.5 GW) increased supplier pressure. Capacity additions have triggered price compression when demand softens, with certification and lead-time reliability emerging as decisive differentiators. Backlog visibility (12+ month order books) directly shapes bargaining power.
Public and utility projects—bolstered by the IIJA’s $1.2 trillion infrastructure package—use competitive tenders with transparent price scoring, driving aggressive bids. Small specification differences frequently decide awards, compressing margins and prompting widespread value engineering and alternate bids. Pre-bid alliances and early vendor involvement are increasingly used to temper bidding intensity and de-risk schedules.
Rivalry intensifies when mills and plants run below optimal utilization; 2024 US manufacturing capacity utilization averaged about 77.5%, pressuring fixed-cost absorption and driving competitors to chase volume, which erodes margins. Conversely, tight regional capacity and maintenance outages create short-term pricing power and discipline; bottlenecks in bridge and structural steel segments lifted spot premiums in parts of 2024.
Competitors differentiate through lower-carbon materials, recycling programs and digital project integration, and in 2024 ESG-linked procurement made up an estimated 30% of major U.S. infrastructure awards, raising contract premiums and award probability for high-ESG firms. Rapid adopters reported margin improvements up to ~200 basis points and gained share, while laggards compete on price, intensifying rivalry and compressing industry margins.
Local quarry economics (haul 20–40 mi) create fierce regional rivalry; 2024 US capacity utilization ~77.5% drove volume chasing and margin pressure. Engineered-structures saw supplier compression after 2024 US wind additions ≈12.5 GW; backlog (12+ months) and certification now key differentiators. IIJA ($1.2T) tenders and ESG (≈30% of major awards in 2024) amplify competitive bidding and value engineering.
| Metric | 2024 |
|---|---|
| US utilization | ~77.5% |
| Wind additions | ~12.5 GW |
| IIJA | $1.2T |
| ESG awards | ~30% |
Composite poles, laminated timber and advanced plastics increasingly displace steel and concrete in niche infrastructure; the engineered wood market reached about $27 billion in 2024, signaling demand shifts. Recycled aggregates and cement substitutes (fly ash, slag) cut traditional mixes' volume by mid-single digits in many regions in 2024. Ultimate adoption hinges on performance and lifecycle costs, while building codes and utility standards continue to moderate substitution pace.
Structural redesigns can cut material intensity and shift products into lighter classes, with lighter/modular systems replacing heavy components and delivering weight reductions often cited up to 40% and material waste cuts from 3D printing as high as 60% in pilot projects. 3D printing and precast alternatives have grown (3D printing construction market expanding rapidly into multi‑digit annual growth by 2024), but wider adoption hinges on certification pathways and contractor familiarity.
Modal shifts between barge/rail and trucking—trucks account for about 72% of U.S. freight value transported by mode per BTS 2022—can change Arcosa demand for specialized rail/barge components versus truck-oriented products and services.
Undergrounding of distribution lines, which is more capital-intensive, can substitute away from overhead steel structures, while design-build/EPC adoption, which rose to roughly 40% of U.S. projects by 2023, favors integrated suppliers.
Infrastructure policy, including the $110 billion in roads and bridges from the Bipartisan Infrastructure Law, steers modal investment and delivery method choices that can materially alter Arcosa’s addressable market.
Coatings, liners and retrofits can defer replacement cycles, substituting repair for new pipe and infrastructure demand; asset management tools now prioritize rehabilitation over new builds, with EPA-estimated US water infrastructure needs of about 744 billion dollars over coming decades driving life-extension choices in 2024.
Sensors and predictive analytics can optimize load planning and reduce overbuild, with 2024 studies showing predictive maintenance cuts unplanned downtime up to 50% and maintenance costs 10–40%, delaying demand for replacements. Smart monitoring improves utilization and extends life, acting complementary yet substituting near-term product volumes; ongoing standardization (open protocols, APIs) will widen impact.
Engineered wood ($27B market in 2024), advanced plastics and composites, plus recycled cement substitutes, are eroding steel/concrete niches; 3D printing and precast grew at multi‑digit rates in 2024 but face certification barriers. Modal shifts (trucks 72% of US freight value) and undergrounding reduce overhead steel demand, while repairs, coatings and sensors (predictive maintenance cuts downtime up to 50%) defer replacements.
| Substitute | 2024 metric | Impact |
|---|---|---|
| Engineered wood | $27B market | Displaces steel/concrete |
| 3D printing/precast | Multi‑digit growth | Lower material intensity |
| Sensors/repairs | Downtime ↓50% | Defers CAPEX |
Quarries, heavy fabrication plants and specialized tooling demand capital often in the tens to hundreds of millions, creating a high entry barrier; industry capex profiles typically span initial outlays of tens of millions for a quarry and multiple tens of millions for heavy fabrication. Economies of scale in sourcing and logistics—reflected in lower per‑ton freight and bulk procurement—favor incumbents and deter small entrants. Oversize transport adds significant cost and complexity, with single oversized loads commonly incurring permits, escorts and specialised equipment costs ranging from tens to several hundred thousand dollars per shipment. Long payback periods, commonly 5–12 years in heavy materials projects, make returns highly sensitive to commodity cycles and construction demand swings.
Environmental permits for quarries and plants routinely exceed 2 years and are frequently contested, creating material entry delays; safety, quality, and ESG compliance have pushed fixed-cost thresholds higher, often requiring multi-million-dollar investments before production. Community and regulatory scrutiny slow greenfield entries, while incumbents benefit from grandfathered assets and existing permit portfolios that deter new entrants.
As of 2024 utilities and state DOTs demand rigorous vendor qualifications and audited QMS, with prequalification and safety audits commonly taking 3–12 months before bidders can compete. New entrants therefore face time-consuming approvals that delay revenue and ramp-up. Contract failures carry heavy penalties, including liquidated damages and fines that can total millions, deterring inexperienced firms. Established track records thus act as a strong moat for incumbents.
Securing reliable steel, aggregates and certified welders/fabricators constrains new entrants; 2024 BLS data shows roughly 460,000 welders/fabricators in the US, keeping skilled labor tight and certification ramp-up slow. Long-term vendor agreements and volume rebates favor incumbents like Arcosa, while nationwide logistics and rail/port networks take years to replicate, raising initial capex and lead times.
Incumbents can deter entrants through targeted pricing, bundling of materials and services, and rapid capacity shifts; Arcosa has historically used acquisitions to expand niche positions and integrate vertically. Fragmented segments in infrastructure materials are frequently consolidated via M&A, shrinking room for stand-alone entrants to scale. Strong customer loyalty and multi-year supply contracts further raise entry hurdles.
High capital (quarry/fab capex tens–hundreds $M) and long paybacks (5–12 yrs) plus >2‑yr permitting create strong entry barriers; economies of scale and oversize transport costs deter small entrants. Vendor prequalification (3–12 months) and skilled labor tightness (welders ~460,000, BLS 2024) raise ramp costs. Incumbent M&A, contracts and volume rebates further limit new entrants.
| Barrier | Metric | 2024 |
|---|---|---|
| Capex | Quarry/fab | tens–hundreds $M |
| Permits | Time | >2 yrs |
| Labor | Welders | ~460,000 |


