
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
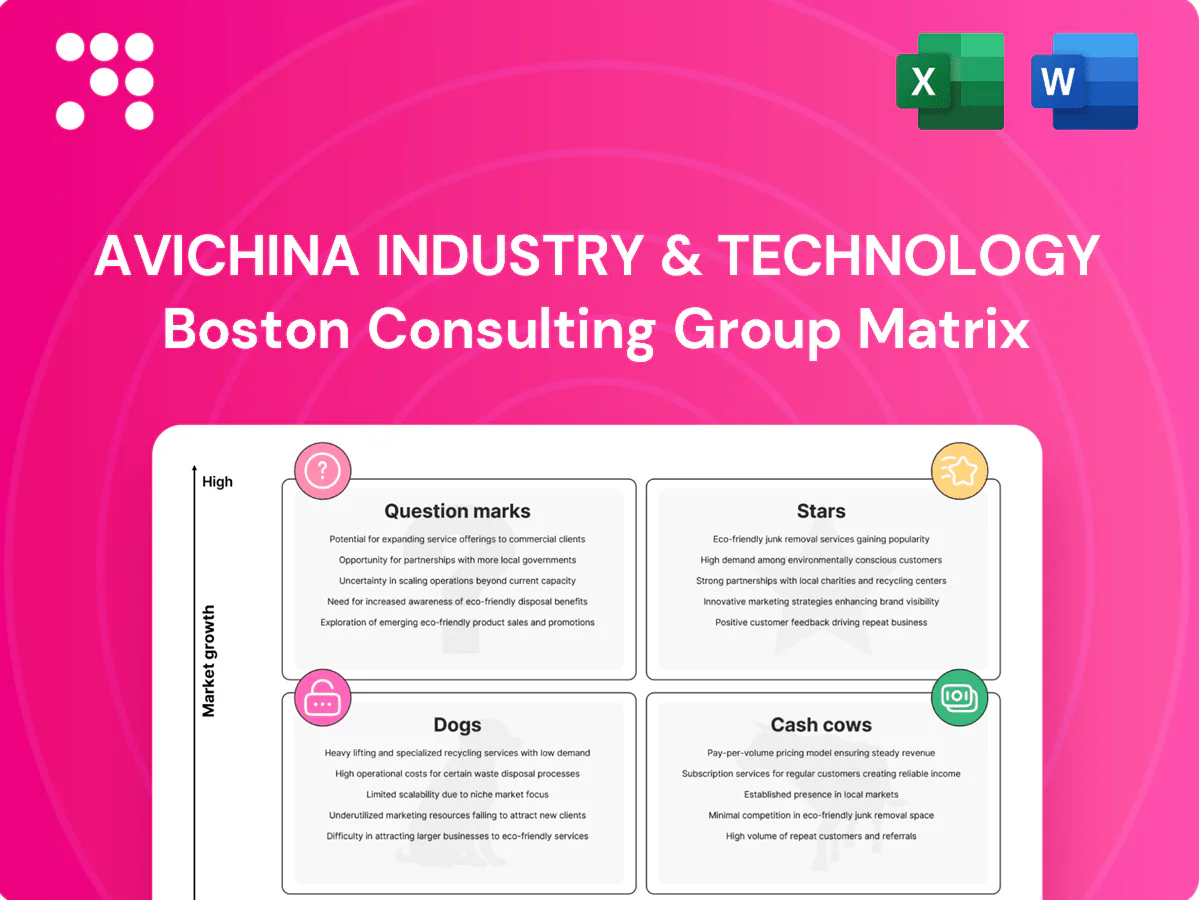
AviChina’s preview BCG Matrix teases which product lines are leading, which generate steady cash, and which need tough choices—useful, but incomplete. The full BCG Matrix gives quadrant-by-quadrant placement, data-backed recommendations, and a ready-to-use roadmap for reallocating capital and prioritizing R&D. Skip the guesswork: purchase the complete report for Word and Excel deliverables with strategic moves tailored to AviChina’s real market position. It’s the fastest way to turn insight into action.
Civil helicopter portfolio sits in the Star box: strong 2024 domestic share (≈70%) and high-growth civil demand across EMS, law enforcement and utility lift keep order books robust. These models lead missions from EMS to utility lift and sustain steady orders, supporting AviChina’s civil revenue mix. They still consume cash for certification, avionics upgrades and expanded sales coverage; continue targeted investment to cement leadership before market growth moderates.
Training and utility fleets are expanding as regional air services scale, supported by a 2024 Boeing Pilot and Technician Outlook projecting 763,000 new commercial pilots needed through 2043, underpinning long-term demand. AviChina’s installed base and OEM/distributor partnerships give it a measurable share edge in China and regional markets. Short-term growth eats cash in demos, pilot support and global type approvals. Holding share now lets these assets mature into dependable cash cows.
Domestic adoption of integrated avionics and mission systems is accelerating alongside China’s 2024 defense budget rise of 7.2% to roughly 1.67 trillion yuan, and bundled systems routinely capture larger platform contracts. Being specified as standard-fit on new platforms materially increases share and lifecycle revenues. Continuous software development and certification drag on margins, often consuming a significant portion of program profits. Doubling down to lock standard-fit positions preserves long-term capture and aftermarket revenue.
Every new AviChina delivery creates a multi‑year service tail—typical military/commercial airframe support spans 10–20 years—so 2024 production adds long‑term recurring revenue. High attachment rates to after‑sales packages (reported industry averages >60% in 2024) keep utilization and margin expansion elevated. Establishing parts pools and field teams requires upfront capital; scale fast while the fleet growth window remains open.
Composite aerostructures are a Star for AviChina as next-gen platforms prioritize lighter structures and local content; each platform win has historically lifted supplier revenue share by double-digits during production ramps. Tooling and qualification require steep upfront spend and 12–24 months to certify, so maintain funding capacity to support multi-year program ramps and capture lifecycle margins.
Civil helicopter, composite aerostructures and integrated avionics are Stars: civil rotor ~70% domestic share (2024), China defense budget +7.2% to 1.67T yuan (2024), Boeing projects 763,000 pilots needed through 2043; high capex for certification/tooling required to convert growth into long-term cash flow.
| Segment | 2024 metric | Implication |
|---|---|---|
| Civil helicopters | ~70% domestic share | Robust orders, demo/cert spend |
| Avionics | Bundled wins ↑ lifecycle rev | Software/cert drag on margins |
| Composites | 12–24mo qual. time | Upfront tooling capex |
 Detailed Word Document
Comprehensive BCG Matrix review of AviChina’s units, giving clear invest/hold/divest guidance and quadrant-specific risks and opportunities.

 Customizable Excel Spreadsheet
One-page AviChina BCG map placing each unit in a quadrant to cut ambiguity for fast C-level decisions.
Standard components such as actuators and landing gear are mature, spec-locked products generating repeat orders and high volumes; the global aircraft spare-parts aftermarket was about $95B in 2024, supporting predictable margins and modest capex for AviChina's lines. Stable cash from these units funds working capital and offsets cyclical programs. Focus on efficiency and long-term agreements (LTAs) to sustain margin capture and milk the line.
MRO and engineering for AviChina's in-service fleet deliver recurring, sticky revenue with steady billable hours and high utilization; China’s commercial fleet surpassed 7,000 aircraft in 2024, underpinning demand. Growth is modest so marketing beyond SLAs is limited, keeping gross margins stable. Targeted investment in turnaround time and tooling yields higher throughput and cash conversion, improving ROIC on mature assets.
Spare parts and rotables distribution is a cash cow for AviChina: an installed base of >3,000 platforms in China (2024) guarantees steady pull-through, making demand highly forecastable and price-disciplined. Low growth but high cash conversion supports stable margins. Optimizing inventory turns and pick-pack operations (target days-on-hand reduction of 10%+) preserves margin resilience.
Licensing and offset production on legacy programs deliver steady volumes with mature processes and minimal engineering churn, preserving gross margins and predictable cash flow; not high growth but core to covering fixed costs and funding R&D.
Training and technical documentation services are essential, low-growth support directly tied to fleet size; China’s commercial and military fleets (≈7,800 aircraft in 2024) sustain steady demand, yielding high repeat business and low customer acquisition costs. Content refreshes are incremental; standardizing curricula and shifting to digital delivery can lift cash yield and reduce unit cost.
Established product lines (actuators, landing gear, rotables) and MRO are low-growth, high-cash generators: global spare-parts aftermarket ~95B USD (2024), China fleet ≈7,800 aircraft (2024), installed base >3,000 platforms. High margins, low capex, predictable orders fund working capital and R&D; focus on LTAs, inventory turns and TAT cuts.
| Segment | 2024 metric | Cash role | KPI |
|---|---|---|---|
| Spare parts | $95B market | Primary cash | Days-on-hand -10% |
| MRO | Utilization high | Recurring cash | ROIC up |
The file you’re previewing is the exact AviChina Industry & Technology BCG Matrix you’ll receive after purchase. No watermarks, no placeholders—just the finished, professionally formatted analysis ready for strategy sessions. It’s downloadable immediately and editable for presentations or reports. Buy once, use immediately—no surprises.
Obsolete airframe variants sit in a low-growth segment and are consuming engineering and manufacturing resources with shrinking order books and margin pressure. Niche customers remain but volumes are insufficient to achieve scale economies, keeping unit costs high. Turnaround investments in rework or modernization are capital-intensive and rarely yield positive ROI for these lines. Recommendation: plan orderly sunsetting and shift to parts-only support and aftermarket capture.
Small-batch custom components show high process complexity, low throughput and thin margins, with competitors repeatedly undercutting prices and the target market stagnant. Cash is tied in frequent setups and scrap from changeovers, eroding working capital. Management should prune SKUs and exit product lines where pricing dynamics cannot recover costs. Tactical consolidation and strict NPV thresholds required.
Non-core aviation-adjacent products sit outside AviChina’s core synergies and do not move the needle; 2024 performance stayed flat with negligible volume contribution. Market share is weak versus core aerospace lines, drawing disproportionate management attention and incremental OPEX. With China's 2024 defense budget rising 7.2%, redeploying capacity from these units makes financial sense; divest or wind down to free capacity and cut costs.
Uncompetitive export-only variants face limited certifications that cap market access and keep their foreign share negligible in 2024, with prolonged sales cycles yielding very low win rates.
Cash drains on repeated bids, post-sale support and compliance updates erode margins; continuing to chase these low-return exports is fiscally unsound.
Refocus on defendable domestic and certified niche markets where AviChina can leverage existing approvals and stronger procurement relationships.
Legacy avionics on AviChina BCG Dogs see customer migration to newer suites and alternative suppliers in 2024, with upgrade orders scarce and low-margin. Ongoing engineering upkeep consumes most of the residual cash, prompting formal sunset plans and support restricted to spares.
Dogs lines delivered 3.8% of AviChina group revenue in 2024 with EBITDA margin -6% and an estimated cash burn of CNY 380m; volumes and orders declined YoY and ROI on modernization is negative. Recommend phased sunsetting, parts-only support and SKU pruning to reclaim capacity and working capital. Target divest/exit for loss-making SKUs.
| Metric | 2024 |
|---|---|
| Revenue share | 3.8% |
| EBITDA margin | -6% |
| Cash burn | CNY 380m |
| SKU reduction target | 40% |
Urban air mobility is a hot Question Mark for AviChina—as of 2024 Morgan Stanley cites a global UAM opportunity up to 1.5 trillion USD by 2040, yet AviChina's eVTOL presence remains nascent with minimal revenue. Certification and ecosystem build-out are major cash sinks (industry peers have raised >1.6 billion USD for development). If tech and partners align this can flip to Star; pick a few bets and fund aggressively or pause.
Hybrid-electric propulsion sits in a tiny but growing market, representing near-zero percent of the global commercial fleet in 2024 and with winners still uncertain. Technology and certification risk remain high, with realistic certification and commercial returns typically 5–10 years out. AviChina’s current share is not meaningful; strategy should target regulatory-certified niches (e.g., regional retrofit, military trainers) where certification advantages can be defended.
Global commercial MRO demand recovered strongly post‑pandemic, with industry revenue around 85–90 billion USD in 2024 while AviChina’s local MRO share remains single‑digit percent and brand recognition is emerging.
Facility buildouts and regulatory approvals have required upfront capex and working capital burn (tens of millions RMB per hub); anchor contracts would enable scale economies and margin recovery.
Recommend selective investment in hubs where captive fleet density exceeds 50–100 aircraft within a 500–800 km catchment to justify deployment and capture predictable maintenance flows.
Advanced digital services (predictive maintenance) sit as a Question Mark for AviChina: strong airline demand but uneven adoption and vocal competitors; pilots can deliver ROI in ~12 months and reduce unscheduled removals by up to 30% per 2024 industry reports, yet require costly sensors, software and data-rights agreements.
Segment demand for special-mission civil variants (EMS, law enforcement) rose in 2024, but AviChina’s market share varies significantly by region due to competing domestic OEMs and export restrictions; certification kits and systems integration require upfront investment that depresses early margins. Securing a few marquee agency contracts can shift a Question Mark into a Star by creating reference customers and easing future sales; target bundled platform+services deals to accelerate adoption and amortize integration costs.
Question Marks: UAM (MS 1.5T by 2040; peers >1.6B raised; AviChina nascent), hybrid-electric (winners unclear; cert 5–10y), MRO (2024 global 85–90B; AviChina single‑digit share), digital services (‑30% unscheduled removals; pilots ROI ~12m); selective hub/anchor contracts and pilots recommended.
| Segment | 2024 metric | Key action |
|---|---|---|
| UAM | MS 1.5T by 2040; peers >1.6B | Selective R&D partnerships |
| MRO | 85–90B global; AviChina <10% | Anchor hubs (10–50M RMB) |


