
Digital download
Access the files immediately after checkout.
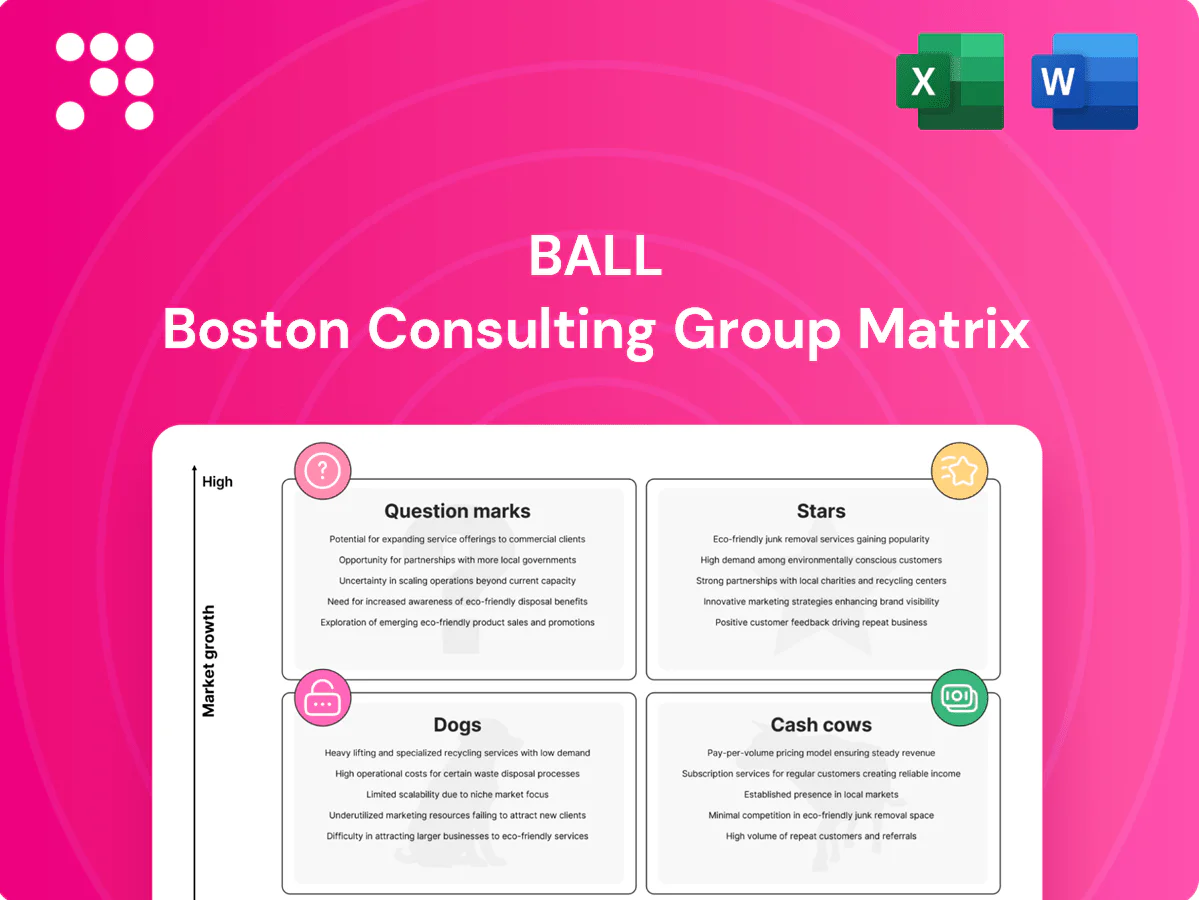
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
You’ve seen the preview — now see the whole picture. Buy the full BCG Matrix to get quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus an Excel summary so you can present and act fast. Skip the guesswork; get clarity and a clear plan for where to invest next.
Energy, functional drinks and RTD alcohol remain high-growth Stars—global energy/RTD segments showing mid-to-high single-digit to double-digit growth in 2024—so Ball leverages 60+ beverage plants and broad CPG relationships to keep major brands close. Prioritize capacity investment where SKUs spike and accelerate speed-to-market to defend share; doing this keeps aluminum cans front-of-shelf and captures premium ASPs.
Lighter gauges deliver same performance with margin uplift and sustainability gains, with Ball holding about one-third of global beverage can capacity in 2024, enabling scale benefits. Retailers increasingly demand footprint cuts without volume risk, driving adoption of light-weighting that can reduce aluminium per can by up to 8% and lower scope 3 emissions. Ball’s process IP and deep tooling network create high replication barriers, preserving pricing power through continued innovation.
Premium specialty cans ride the better-for-you and premiumization wave, with the slim/sleek segment outpacing overall can growth—≈8% CAGR 2019–2024—and commanding price premiums of 10–20%. Ball’s format range and quality control underpin contracts with 60+ global beverage brands and support its scale advantage. As brands expand SKUs, allocation favors suppliers who can deliver—Ball’s service and speed protect this star position.
Regulators favor infinitely recyclable aluminum; mandates and EPR targets in EU and US boost demand and recycling saves up to 95% energy versus primary aluminum. Consumers understand cans—EU beverage-can recycling ~72% and US ~50%—and brands market cans, converting glass and plastic spends into can runs. Ball is shorthand for aluminum, keeping share sticky; push recycled content and closed-loop deals to lock it in.
Stars: Aerospace instruments and mission systems — demand for earth observation, defense and comms is ramping; the global space economy reached about 469 billion in 2023 and NASA’s FY2024 budget was roughly 27.2 billion, reinforcing program pipelines where Ball’s heritage builds trust. Mission-critical payloads command higher margins and long multi-year backlogs; incremental wins drive follow-on work, so invest in capacity and talent to capture the updraft.
Stars: Beverage cans (energy/RTD/premium) and Aerospace mission systems—beverage cans growth mid-to-high single digits to double digits in 2024; Ball holds ~33% global can capacity (2024) and 60+ plants. Space: global space economy USD 469B (2023); NASA FY2024 USD 27.2B backlog supports high-margin awards.
| Metric | Value | Year |
|---|---|---|
| Can capacity share | ~33% | 2024 |
| Global space economy | USD 469B | 2023 |
 Detailed Word Document
Concise overview of Stars, Cash Cows, Question Marks and Dogs with strategic recommendations to invest, hold or divest.

 Customizable Excel Spreadsheet
One-page Ball BCG Matrix highlighting pain points and priorities for swift portfolio decisions
Core SKUs in North America and Europe still print cash; volumes were broadly steady year-over-year in 2024, keeping utilization high. Capex for line conversions is largely behind management, so incremental OEE gains drop straight to margin. Long-term supply contracts with major brewers smooth revenue visibility. Milk it: focus on uptime and avoid over-building capacity.
Aerosol aluminum containers are a mature category with stable demand and high customer stickiness in personal care and household segments. Quality control and regulatory compliance create high switching costs, keeping churn low. Incremental automation and scrap reduction programs have widened margins, so maintain service levels with minimal promotional spend.
Ends and tabs manufacturing is a high-volume, repeatable business with classic scale economics—once qualified, Ball typically remains on the bill of materials and secures multi-year supply streams. Incremental tooling upgrades and line optimizations raise throughput and lower unit costs, turning modest CAPEX into durable margin expansion. This cash generator funds Ball’s growth bets across R&D and capacity investments.
Recycling and re-melt partnerships give Ball predictable feedstock, lowering aluminum input cost volatility and leveraging up to 95% energy savings versus primary metal; closed-loop ties with key customers cut logistics and waste, trimming COGS. It’s not flashy, but steady remelt capacity stabilizes margins; optimize long-term contracts to harvest predictable cash flows and reduce working-capital swings.
Long-term supply agreements with global beverage brands act as Ball cash cows: volume commitments and index-linked pricing protect downside while service-level metrics keep renegotiations cooperative; Ball reported roughly $16.3bn in 2024 net sales, underscoring scale. These contracts deliver low growth but high stickiness—maintain SLAs and convert excess margin into free cash flow.
Core beverage SKUs, ends/tabs and recycled re-melt act as Ball cash cows: steady volumes, high utilization and low incremental capex drove strong free cash flow in 2024. Long-term contracts and feedstock partnerships cut input volatility and protect margins. Convert excess margin to cash; prioritize uptime and contract optimization.
| Metric | 2024 | Note |
|---|---|---|
| Net sales | $16.3bn | Reported 2024 |
| FCF conversion | High | Low incremental capex |
The file you're previewing here is the exact BCG Matrix report you'll receive after purchase—no watermarks, no placeholders, just the finished, fully formatted document. It's crafted by strategy pros for clarity and action, ready to drop straight into your planning, pitch decks, or client deliverables. After buying you'll get the same editable file for immediate download and use—no surprises, no extra steps. Simple, professional, and built to work for you right away.
Tiny batches tie up lines, spike changeovers (2024 surveys report average changeover windows of 45–120 minutes), and erode yield and OEE. Customers value the flexibility; the P&L often does not—untargeted micro-runs bleed margin unless priced to pain. Left unchecked, SKU proliferation drains cash flow and capacity. Prune SKUs or migrate volumes to dedicated micro-capacity cells.
Flat-to-down demand for legacy soda SKUs in oversupplied regions saw mid-single-digit volume declines in mature markets in 2024, with too many lines chasing shrinking sales. Intense price competition compressed gross margins by roughly 150–250 basis points as producers cut prices to defend share. Exiting is costly and complex; Ball must rationalize capacity and redeploy aluminum can lines to growth SKUs like RTD and craft beverages.
Small regional accounts with frequent art changes drive high artwork churn and approvals—industry benchmarks in 2024 show short-run digital jobs carry a 20–50% per-unit cost premium and approvals add 3–5 business days, while artwork rework can inflate ops overhead by 10–25%. These rarely scale into strategic volume, are relationship drivers not return generators, and should be bundled into larger orders or sunset.
Dogs are underutilized assets after demand shifts: fixed costs persist and US industrial capacity utilization averaged about 77% in 2024 (Federal Reserve), so idle hours quietly erode P&L and lower margins. Turnarounds for these lines are typically expensive and slow, often taking months and capital that exceeds short-term recovery value. Better to consolidate or divest than hope for a rapid market rebound.
Non-core specialty metal containers are niche lines where Ball isn’t the first call; in 2024 Ball reported $15.7 billion in net sales, yet these SKUs contribute a low-single-digit share of packaging revenue and lag core beverage cans in volume and margin. Competitors can undercut pricing or offer bespoke customization faster, leaving cash tied up in low-visibility assets. Exit or seek partners rather than incremental tinkering.
Dogs: legacy, low-growth SKUs draining capacity and cash—US industrial utilization was ~77% in 2024 (Fed), and Ball’s can portfolio saw mid-single-digit volume declines in mature markets. Small-batch runs raise per-unit costs 20–50% (2024 benchmarks). Recommend consolidate/divest; turnarounds cost more than redeployment.
| Metric | 2024 |
|---|---|
| US capacity utilization | 77% |
| Volume trend (mature markets) | -3% to -7% |
| Short-run cost premium | 20–50% |
Consumers and brands are converging on aluminum bottles for personal care and household: demand for plastic-free formats and shelf pop is driving adoption while market analysts estimated aluminum packaging growth near 6% CAGR through 2029 (2024 baseline). Ball’s proprietary forming tech improves cost and weight economics, but Ball’s share in this nascent segment is still building and dependent on anchor-customer commitments. Investment should follow confirmed long-term offtake deals; otherwise exit.
Direct-to-can digital printing is a killer for test runs and hyper-local SKUs, enabling rapid SKU variation and on-demand branding. Today it remains capex-heavy and niche within Ball’s portfolio, suited for pilots and brand incubators. If throughput and press efficiency improve, unit margins could materially outperform offset/roll-fed methods. Bet selectively near incubators where short-run value and speed drive premium pricing.
New adjacencies—RTD coffee, protein beverages and mocktails—are high-growth question marks, with the RTD coffee segment alone showing ~8% CAGR through 2024 and the combined addressable market near $20B in 2024. Packaging is shifting to aluminum as cans gain share for sustainability and on‑premise cold formats; Ball can win if it nails barrier performance and format fit. Market share is not locked; pilot with category leaders and scale only after repeat order cadence confirms demand.
Question Marks: Circularity services face strong policy tailwinds—EU measures like the Ecodesign for Sustainable Products agenda advanced in 2024—while customers increasingly demand traceable proof of reuse and recycling; managed return/sorting/closed-loop deals can lock multi-year volumes and pricing, but operations are complex and margin profiles remain unproven, so prioritize builds where regulation subsidizes returns.
Next-gen aerospace programs (smallsat constellations, sensors) face surging demand—smallsat deployments exceeded 1,000 units in 2023–2024—while competition and capex intensity rise; qualification wins can flip a question mark into a star, but failed validation burns cash and dilutes margins. Talent scarcity and strained supply chains determine who scales; allocate capital to winnable pursuits and trim marginal programs.
Question Marks: prioritize pilots in aluminum personal-care (packaging growth ~6% CAGR to 2029) and RTD coffee (~8% CAGR to 2024) and circularity (ESPR 2024); high capex and validation risk—de-risk with anchor offtake, pilots and regulated markets, scale only after repeat orders.
| Item | 2024 metric | Action |
|---|---|---|
| Aluminum PC | ~6% CAGR to 2029 | Pilot, secure anchor |
| RTD coffee | ~8% CAGR to 2024 | Qualify w/ leaders |
| Circularity | ESPR progress 2024 | Deploy where subsidized |


