
Digital download
Access the files immediately after checkout.
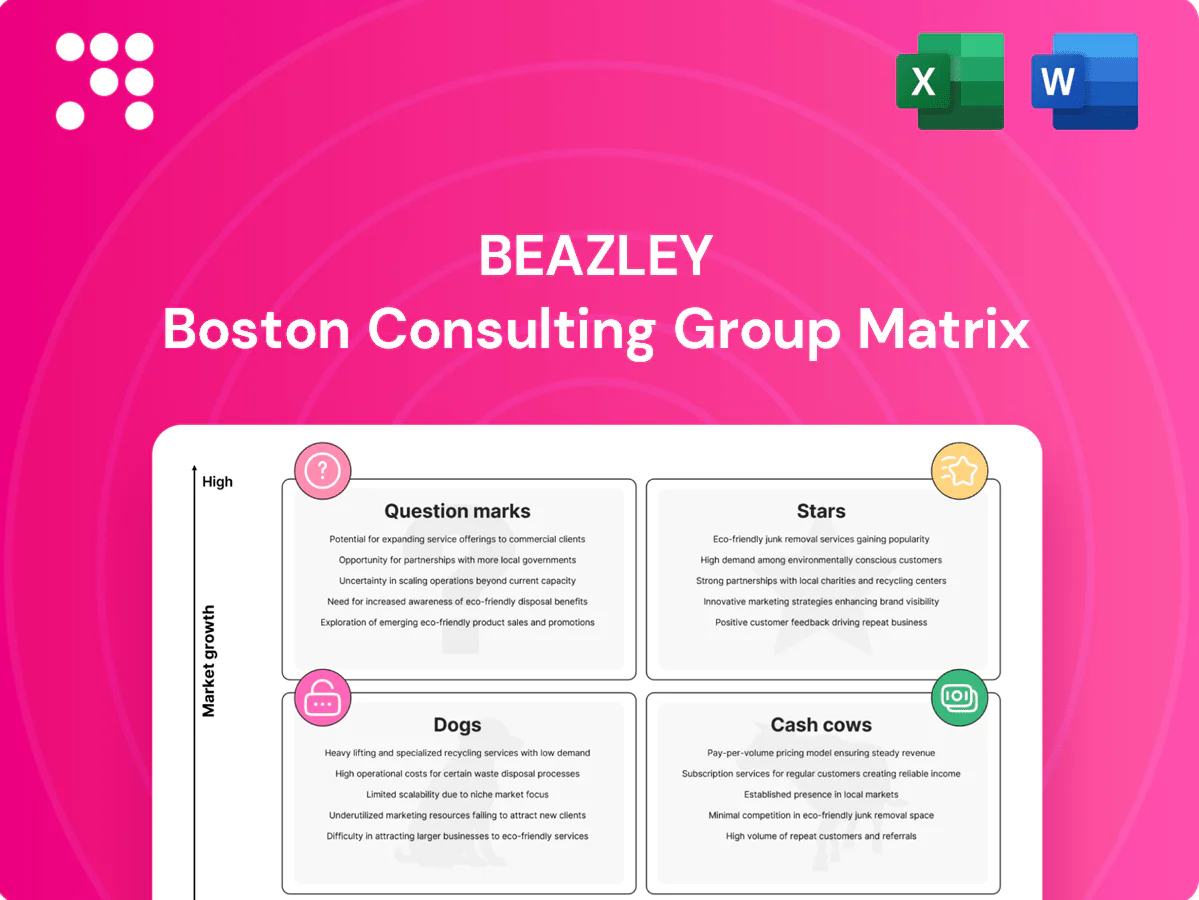
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Beazley’s products sit—Stars, Cash Cows, Dogs or Question Marks? This snapshot points you in the right direction, but the full Beazley BCG Matrix gives quadrant-by-quadrant clarity, data-backed recommendations, and actionable moves you can implement now. Buy the complete report for a ready-to-present Word analysis plus a high-level Excel summary that saves you hours of work and sharpens investment decisions. Purchase now for instant access and strategic certainty.
Beazley’s breach response ecosystem—legal, forensics, PR—turns policy coverage into a hands-on solution that buyers notice, supporting reported cyber renewal rates around 85% in 2024 and strong customer stickiness. The service-led model is capital- and talent-intensive but defensible, keeping retention high in a market where global cyber premiums reached roughly $15.4bn in 2024. Growth plus retention qualifies it as a Star in the BCG matrix. Over time the response engine should convert growth into steadier margins.
Mid-market cyber packages with pre-configured limits, clear wordings and fast-bind workflows are driving rapid adoption; global cyber insurance premiums surged about 30% in 2024, fueling demand. Beazley’s underwriting playbooks and proprietary data give them an edge at scale, enabling rapid binding and loss selection. High distribution velocity creates elevated cash needs but typically yields payback within months. Keep the flywheel spinning and it graduates to Cash Cow territory.
Global Lloyd’s access gives Beazley direct placement into complex cyber risks across geographies and industries, sustaining elevated premium pipelines and rapid incident learning loops. Leadership in a Lloyd’s-centric channel rewards technical expertise and underwriting speed, converting technical edge into pricing power and retention. As cyber markets mature, this compounding distribution advantage solidifies Beazley’s Stars positioning.
Cyber risk services add‑ons sit as Stars in Beazley’s BCG matrix: pre‑loss services — training, vulnerability scanning and vendor hardening — improve outcomes, cut loss ratios and helped keep cyber market share high as clients increasingly buy measurable outcomes over policy wording.
Capital‑light but operations‑heavy today, scaling these services (per industry data showing cyber premiums growth ~15% y/y to 2024) should drive margin accretion as fixed costs spread and loss ratios fall.
Beazley is a Star in cyber: double-digit cyber premium growth in 2024, ~85% renewal rates and exposure to a $15.4bn global cyber market. Service-led breach response and Lloyd’s distribution drive retention and pricing power. Pre-loss services scale margins as premiums surged ~30% in 2024.
| Metric | 2024 |
|---|---|
| Global cyber premiums | $15.4bn |
| Beazley cyber growth | Double-digit |
| Renewal rate | ~85% |
| Premium surge | ~30% |
 Detailed Word Document
Targeted BCG analysis of Beazley's products, advising which units to grow, sustain, or divest with market trend context

 Customizable Excel Spreadsheet
One-page Beazley BCG Matrix highlights portfolio pain spots, enabling quick C-suite decisions.
Professional indemnity for lawyers, accountants and consultants remains a cash cow for Beazley; in 2024 the firm continued to show strong retention and stable margins in these mature segments. Pricing is rational, competition steady, and distribution channels are well‑established, producing robust renewal income with manageable volatility. Focus: milk it, sustain service levels and tighten loss control to protect underwriting profitability.
Marine specialty (hull, cargo and related niches) delivers low single-digit growth with underwriting expertise driving margins; Beazley’s strict underwriting discipline and deep broker relationships secure a stable share in these technical classes. Investment and capital needs are minimal, with incremental data and process tweaks improving combined operating efficiency. The unit reliably generates cash flow to fund higher-growth strategic bets.
Miscellaneous E&O in mature markets delivers repeatable premiums for Beazley thanks to refined wordings, known claims patterns and efficient operations; not flashy but predictably profitable. These cash cow premiums supported Beazley’s growth and funding for innovation, helping underwrite its R&D and expanding cyber capability. In 2024 Beazley reported gross premiums written of about $2.2bn, underscoring scale and capital generation.
Beazley’s political-risk core accounts sit as cash cows: marquee, well-structured portfolios focused on stable sovereign and large-obligor cover rather than volatile fringe business.
Long-standing client relationships and selective country/obligor underwriting—drawing on Beazley’s 1986-founded platform (38 years by 2024) and London-based specialist teams—drive steady, predictable earnings.
Growth is muted but high know-how barriers protect share; when group risk appetite is calibrated, these lines generate solid cash contribution to the portfolio.
Beazley cash cows—professional indemnity, marine specialty, misc E&O, property facultative and political risk—delivered stable margins, low-single-digit premium growth and predictable renewals in 2024; retention and underwriting discipline kept volatility manageable and funded higher-growth initiatives. Focus: sustain service, tighten loss control and harvest cash for strategic investment.
| Line | 2024 GWP | Growth | Role |
|---|---|---|---|
| Cash cows aggregate | $2.2bn | Low-single-digit | Reliable cash generator |
The Beazley BCG Matrix you're previewing is the exact file you'll receive after purchase—no placeholders, no watermarks. It’s a fully formatted, ready-to-use strategic report built for clarity and quick decision-making. Once bought, the same document is yours to download, edit, print, and present to stakeholders. Designed by strategy pros, it slots straight into planning or investor decks with zero surprises.
Commoditized small property faces industry over-capacity and buyer behavior that is price-first in 2024, leaving little room for product differentiation and causing margins to be persistently squeezed.
Retention yields high volatility with limited payoff; multi-year turnaround efforts historically drain management time and often fail to restore meaningful profitability.
Best action is to exit or sharply prune exposure, redeploy capital to higher-return lines, or set strict minimum pricing and underwriting gates to avoid margin erosion.
Outside Beazley’s specialist DNA, non-core personal lines show low share and low growth in 2024, with brand traction limited and persistent price pressure. Cash allocated to these lines delivers thin returns and sits idle relative to specialty divisions. Recommend disciplined divestment or run-off to redeploy capital into higher-return specialist classes.
Legacy binder programs have dated wordings and mixed performance that dilute focus; 2024 industry reviews show these books often post loss ratios near 100–120% and higher volatility. Administrative lift is high, with commissions typically 15–25% of premium and admin costs consuming over 20% of GWP, squeezing margins. Rework rarely justifies the cost; winding down can free 10–30% of underwriting hours for redeployment.
Dogs: Cat-heavy property treaties combine peak catastrophe exposure with commodity-linked pricing, a risky mix given 2023 global insured catastrophe losses of about 120 billion USD and 2024 property reinsurance rate increases near 20% at January renewals. Volatility spikes commonly erase slim technical gains and trap capital for limited payoff. Step back unless a clear proprietary underwriting edge exists.
Dogs:
Dogs: commoditized small property and subscale aviation show low share, flat/negative growth and high loss volatility; 2023 insured catastrophe losses ~120bn USD and 2024 reinsurance repricing ~+20% (Jan). Loss ratios often 100–120%, commissions 15–25%, admin >20% GWP; recommend exit or run-off unless clear proprietary edge.
| metric | value |
|---|---|
| 2023 insured cat losses | ~120bn USD |
| 2024 reinsurance repricing | ~+20% (Jan) |
| loss ratios | 100–120% |
| commissions | 15–25% |
| admin costs | >20% GWP |
Question Marks:
Bundling embedded SME cyber with SaaS, MSPs or fintech rails taps a massive channel: there are about 33 million US small businesses and IBM found the average breach cost was $4.45 million in 2023, making protection a clear upsell. Distribution exists but Beazley’s share remains limited; scaling requires open APIs, frictionless underwriting and tight vendor-risk controls tied into partner stacks. Move aggressively or risk ceding SME distribution to fast-moving insurtechs.
Digital health liability sits as a Question Mark: telemedicine now represents roughly 10–15% of US outpatient visits in 2024, AI diagnostics see over 500 FDA-cleared devices by 2024, and cross-border care volumes are rising as regulators and platforms evolve. Exposure is new and market demand is hot; market share is nascent and wordings change monthly. Underwrite cautiously, learn fast, scale with data; upside is material if claims remain tame.
Launch cadence and LEO constellations are expanding—UCS reported about 7,600 operational satellites in 2024—yet Beazley is not a dominant name in space insurance; technical barriers and specialist engineering needs keep premiums elevated, with global satellite insurance premiums near $700m annually in 2023. A few targeted partnerships with OEMs or launch providers could unlock scale; adopt test-and-learn pilots before committing large capital.
Boardrooms demand directors and professional indemnity cover for evolving ESG and transition risks as regulatory and litigation landscapes shift; Sabin Center tracked over 2,000 climate-related cases globally by 2024, keeping definitions and case law in flux so pricing is uncertain. Early-mover insurers can capture market share if products are well-crafted; run pilots now and scale as legal signals firm up.
Question Marks: parametric covers, SME cyber bundles, digital health liability, LEO/space and D&O ESG cover show high demand in 2024 but low Beazley share; convert via data partnerships, APIs, pilots and targeted underwriting to win scale.
| Segment | 2024 metric | Action |
|---|---|---|
| Parametrics | double-digit demand↑ | data+triggers |
| SME cyber | 33M SMB; $4.45M breach (2023) | embed+APIs |
| LEO | 7,600 sats (UCS 2024) | pilots |


