
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
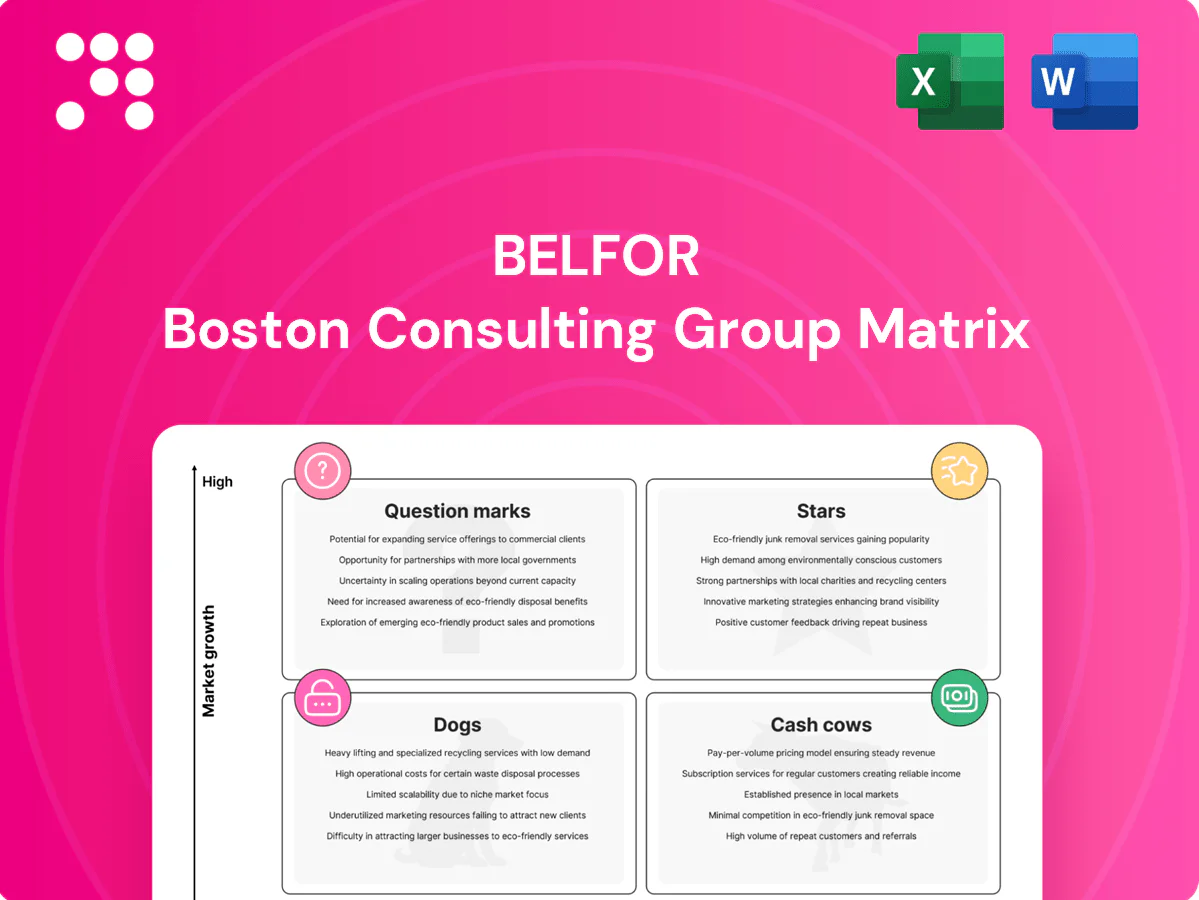
The Belfor BCG Matrix snapshot shows where its services and product lines sit—Stars driving growth, Cash Cows funding stability, Question Marks that need bets, and Dogs tying up resources. This quick look highlights the biggest opportunities and risks but skips the granular data you need to act. Purchase the full BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus an Excel summary to present and execute your strategy. Get it now and cut straight to confident decisions.
Large-loss commercial restoration sits in Stars: climate-driven extreme weather and aging infrastructure sustain high demand, and BELFOR holds a leading national share with coast-to-coast operations. Projects are large, complex and cash-hungry — heavy mobilization, expensive equipment and specialist crews drive working capital needs. Continue investing in rapid-deployment assets and key-account coverage to defend share; sustain pace and it converts to Cash Cow as growth moderates.
Catastrophe response sits in BELFORs BCG high-growth, high-visibility quadrant: when hurricanes, floods and freezes strike the network in over 30 countries turns speed, logistics and scale into market share gains. Upfront staging of crews and equipment is capital‑intensive but recoups via high-volume contracts and surge pricing. Continue investing in pre-positioning and carrier coordination to remain first call.
Water-related events are rising—NOAA recorded 28 billion-dollar weather and climate disasters in 2023 totaling about $61.2B—driving demand for mitigation. BELFOR, a recognized leader in multi-site losses, wins through advanced drying tech, 24/7 response and rapid documentation, but those capabilities demand constant reinvestment. Marketing and insurer programs keep the funnel hot; maintaining share now secures long-run cash flow.
Fire & Smoke Damage Restoration is a complex, regulated, high-ticket Stars segment for BELFOR, underpinning leadership in urban and industrial zones with reported company revenue ~ $2.6B (2023) and double-digit demand growth in 2024 in major metros; specialized cleaning tech and trained crews drive capacity but create high cash burn during surge events, while brand trust and deep technical IP preserve market share—fund certification, contents labs, and tight project controls are essential.
Reconstruction after mitigation is a Star: strong 2024 tailwinds as clients prefer one vendor from demolition through rebuild, and BELFOR (≈$2.5B revenue in 2023) wins on continuity. The work ties up labor, materials and subcontractors—capital intense but increasingly defensible at scale. Margins improve with tight scheduling and centralized procurement, and leaning into design‑build closes the loop on large claims.
BELFOR Stars: climate-driven disasters and aging infrastructure keep high growth; nationwide scale and brand convert surge wins into durable share. 2023 revenue ~ $2.6B; 2024 demand in major metros showing double-digit growth. Continued capex in rapid-deploy, contents labs and pre-positioning preserves transition to Cash Cow.
| Segment | 2023 rev | 2024 growth | Capex |
|---|---|---|---|
| Stars (cat, water, fire, recon) | $2.6B | 10%+ | pre‑positioning, labs, equipment |
 Detailed Word Document
BCG Matrix review of Belfor's units, outlining Stars, Cash Cows, Question Marks, Dogs with strategic invest/hold/divest guidance.

 Customizable Excel Spreadsheet
One-page BCG matrix that instantly spots cash cows and pain points for faster strategic fixes
Insurance Carrier Program Work (Preferred Vendor) delivers steady volumes, mature relationships, and repeatable workflows that form a classic cash engine for Belfor; the company operates across more than 30 countries and maintains multibillion-dollar annual revenue, making on-panel placement highly leveraged in 2024.
Low incremental marketing cost once on-panel means incremental margin expansion is driven by optimizing SLAs, documentation, and cycle time; improving cycle time by even 10% typically widens service margins materially in restoration markets.
Focus on milking predictable cash flows while preserving service quality to avoid churn—preferred-vendor retention and repeat work underpin stable EBITDA contribution in carrier programs.
Residential water and minor fire jobs are classic cash cows for Belfor, delivering high market share in a mature, predictable segment—Belfor reported roughly $1.5B revenue in 2023 with steady residential work underpinning margins. Jobs are small but constant, with tight playbooks and low acquisition cost; average dispatches are high-frequency, low-ticket. Crew utilization is the primary lever—keeping trucks busy preserves profits. Light investment in local presence and routing tech (GPS/dispatch software) sustains strong yields.
Mold remediation is a regulated, steady cash cow for BELFOR, leveraging IICRC S520 certification and documented processes (IICRC S520 remains the primary industry standard in 2024) to drive credibility and contract wins.
Market growth is modest but margins remain healthy when scopes are tightly defined and priced; BELFOR’s standardized protocols preserve unit economics.
Cross-sell from water-loss jobs delivers very low incremental CAC due to high conversion of mitigation-to-mold work; standardized testing, containment, and reporting keep revenue predictable and cash flow consistent.
Board-Up, Tarping, and Securing are first-in services with high share and low growth that feed larger remediation jobs; in 2024 they remained primary callouts driving downstream work. Low marketing needs and SLA-driven speed/coverage are decisive; efficiency and strict safety protocols preserve margins. Treat as a feeder and stable profit center in Belfor’s BCG matrix.
Contents Cleaning & Pack-Out is a dependable cash cow for Belfor: established labs and standardized processes yield consistent throughput and service quality, with mitigation referrals supplying a low cost-to-win pipeline. Profitability is driven by throughput and tight inventory control; keep equipment current to sustain margins, otherwise accept print-only returns.
Insurance carrier programs, residential water/minor fire, mold remediation, board-up and contents cleaning are Belfor cash cows: low CAC, high volume, predictable margins; on-panel leverage and SLA optimization expand margin. Belfor reported ~ $1.5B revenue in 2023 and operates in 30+ countries; IICRC S520 remains 2024 standard.
| Service | Role | Margin levers | Note |
|---|---|---|---|
| Carrier Programs | Primary cash engine | SLAs, cycle time | On-panel leverage |
| Residential Water/Fire | High-frequency | Crew utilization | Low CAC |
The file you’re previewing is the exact Belfor BCG Matrix report you’ll receive after purchase. No watermarks, no demo text—just the finished, fully formatted analysis ready for use. It’s crafted by strategy pros and formatted for clarity, editable and presentable straight away. After payment you’ll get the full download in your inbox—no surprises, no revisions needed.
Standalone Remodeling (Non-loss) is low-growth for BELFOR, crowded with local specialists and a weak strategic fit; BELFOR reported roughly $2.2B revenue in 2023 with insurance-triggered work forming the core. Non-insurance remodeling has low share and ties up crews and capital for modest returns (EBIT margins often mid-single digits). This activity is prime for selective exit or only taken to backfill capacity.
General handyman/minor repairs are highly fragmented, price-sensitive, and largely undifferentiated; market data shows single-digit growth and negligible brand-led share gains. For Belfor this subsegment represents minimal revenue contribution and low strategic value, with estimated CAGR around 2% in 2024 and thin net margins below typical corporate thresholds. Admin overhead and dispatch costs can erase margins, so limit involvement to warranty closeouts or not at all.
Niche document restoration is a specialized, lumpy-demand Dogs segment for BELFOR, with many clients shifting to digital workflows by 2024, thinning BELFOR’s share except for large archive wins. High capex for specialized equipment and continuous climate control creates cash-trap risk and long payback cycles. Recommend divestiture or partnership unless work bundles with large-loss remediation packages.
Asbestos abatement is a mature, regulatory-heavy niche dominated by entrenched regional specialists; compliance with OSHA, EPA and state rules drives high capital and administrative burden. BELFOR holds a low share (<5%) where the service is non-core and often run at a loss. High project risk, slow receivables and thin margins make standalone abatement a drag; do it only bundled into integrated restoration projects.
Small standalone biohazard cleanup is dominated by local specialists who frequently undercut price, leaving Belfor with low market share and little scalable growth in this segment. The service carries reputation risk and offers limited margin upside compared with core remediation lines. Maintain only when bundled with carrier contracts or key accounts to protect margins and brand.
Standalone remodeling, handyman, document restoration, asbestos abatement and small biohazard cleanup are low-growth, low-share Dogs for BELFOR: margins mid-single-digits or negative, share typically <5-10%, high capex/compliance and slow receivables; recommend divest, bundle, or selective exit.
| Segment | Share | CAGR 2023-24 | EBIT | Action |
|---|---|---|---|---|
| Remodeling | <5-10% | ~2% | ~mid-ss | Exit/bundle |
| Handyman | <5% | ~1-3% | low | Exit |
| Doc restore | <5% | 0-1% | negative | Divest/partner |
| Asbestos | <5% | 0% | thin/neg | Only bundled |
| Biohazard | <5% | ~2% | thin | Bundle w/contracts |
Rising insurer and property-owner demand for climate hardening is driven by escalating losses—NOAA reports 22 US billion-dollar disasters in 2023 costing $92.9B—yet BELFOR’s market share in Climate Resilience & Hardening remains early. Combining advisory with install (floodproofing, wildfire mitigation) could scale quickly if BELFOR builds new GTM channels and partnerships. Recommend testing pilots, investing in technician training and supply chains, and landing flagship municipal or insurer-backed wins to prove capability.
IoT leak detection and monitoring is a high-growth segment, with the global market projected at a roughly 16% CAGR through 2030 per 2024 industry reports as carriers shift to prevention; BELFOR’s share remains nascent. A hardware + monitoring + rapid-response bundle can lock in lifetime value via recurring monitoring fees and remediation margins. Success requires upfront capital, a scalable data stack, and channel deals with insurers and property managers. Run pilots now and, if conversion rates meet targets, scale quickly; if not, cut losses fast.
Owners demand downtime reduction and the predictive-maintenance category is heating up; 2024 market estimates exceeded $10B and studies report up to 50% downtime reduction. BELFOR’s restoration DNA is an asset but current market share remains single-digit. Productization and analytics talent are gating factors; invest selectively with anchor clients to prove ROI and scale.
Green/recycled restoration is a Question Mark: ESG assets exceeded 41 trillion USD in 2024, so client willingness to pay for verified green options exists but adoption is early and share is small. Supply-chain complexity and recycled-material price volatility can compress margins by several percent, so pilot SKUs and measure loss ratios before scaling. Differentiation in bids can win enterprise accounts if cost-to-serve is controlled.
Question Marks: Wildfire hardening and post-soot cleaning face a Western market surge with estimated market CAGR ~10% to 2028; BELFOR’s dedicated program is nascent but can capture share by deploying targeted crews and specialized equipment, securing certifications and aligning with insurers to meet underwriting requirements, and proving speed-to-restore regionally to convert into a Star.
Question Marks: prioritize pilots in climate hardening, IoT monitoring (16% CAGR to 2030), predictive maintenance (2024 market >$10B) and green options (ESG assets $41T in 2024); focus on insurer/channel pilots, training, supply-chain tests, and time-to-restore KPI to convert to Stars.
| Segment | 2024 data | Key action | KPI |
|---|---|---|---|
| Climate hardening | NOAA: 22 US B-dollar events 2023 $92.9B | Insurer pilots, crews | Conversion rate |
| IoT monitoring | ~16% CAGR to 2030 | Bundle HW+monitoring | ARR/retention |
| Predictive PM | >$10B market 2024 | Anchor clients, analytics | Downtime % reduction |
| Green restoration | ESG assets $41T 2024 | Pilot SKUs, price test | Margin impact |


