
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
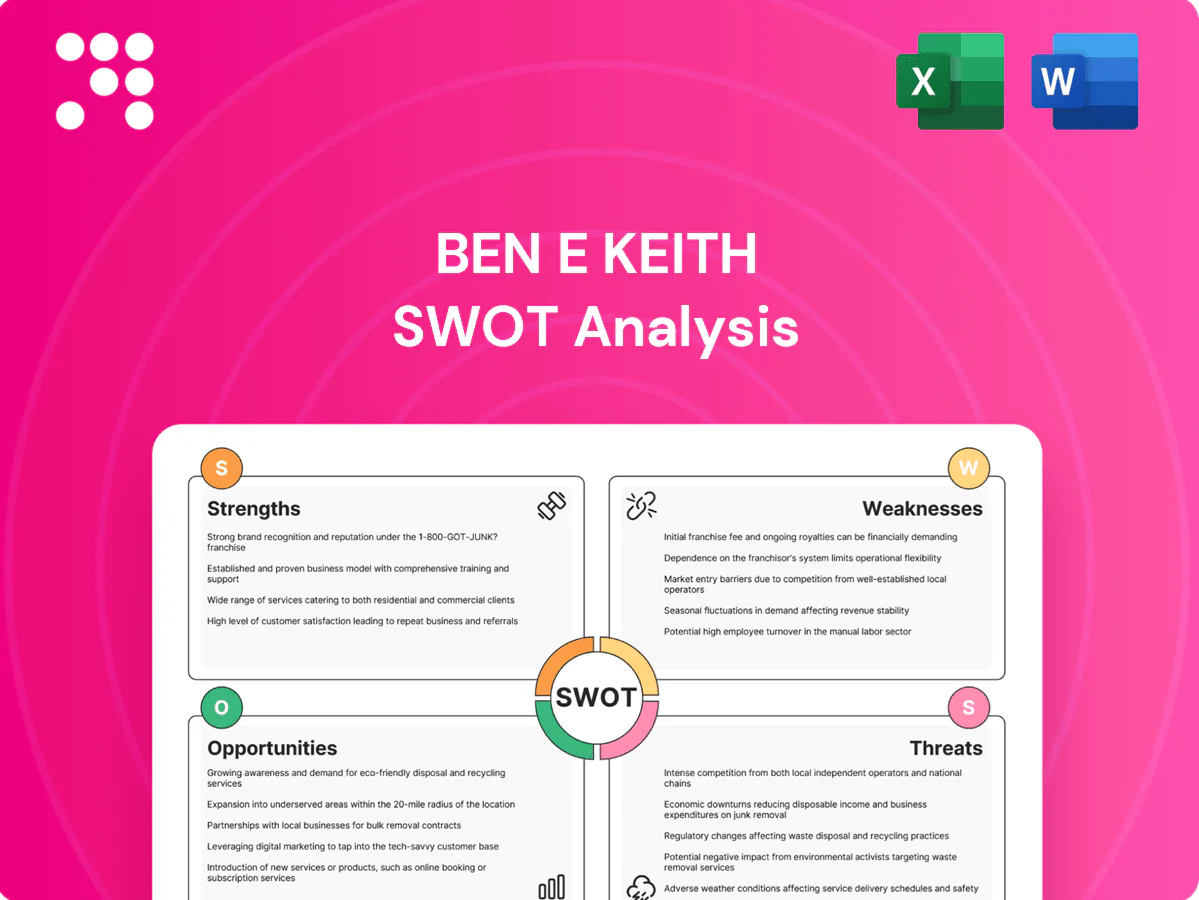
Ben E Keith's SWOT analysis highlights its robust distribution network, diverse product portfolio, and operational resilience, while flagging margin pressures, regional competition, and sensitivity to foodservice demand. Discover the full picture with our complete SWOT analysis—actionable insights, financial context, and editable deliverables to support strategy and investment decisions. Purchase now for the investor-ready Word and Excel package.
Operating both Foods and Beverages since its founding in 1906, Ben E. Keith captures cross-selling opportunities and shared logistics efficiencies across product lines.
Overlapping customers raise route density, lowering delivery cost per stop and improving margins for the distributor model.
Broad portfolio increases account stickiness and switching costs while smoothing demand cycles between on-premise beverages and broadline foodservice.
Exclusive/primary distribution of Anheuser-Busch InBev brands anchors volume and shelf access—AB InBev holds about 30% of global beer market share—while Ben E. Keith’s longstanding ties with major food manufacturers secure reliable supply and promotional support; preferred status often yields better terms and allocation during tight markets, reinforcing credibility with operators across its roughly 100,000 customer accounts.
Ben E. Keith, founded in 1906, offers proteins, produce, domestic, craft and import beers and spirits, covering most operator needs. One-stop purchasing streamlines procurement and invoicing for operators. Broad catalogs enable tailored menus and beverage programs, supporting larger average order values and deeper multi-category penetration.
Ben E. Keith’s established distribution centers, cold chain infrastructure, and route networks underpin consistently high service levels for foodservice and retail customers. Its scale enables competitive pricing, strong inventory turns, and elevated fill rates, while investments in WMS, TMS, and telematics have measurably improved accuracy and on-time delivery metrics. Reliable execution fosters deep trust with restaurants, venues, and retailers across its operating territory.
Ben E. Keith, founded in 1906 and based in Fort Worth, TX, leverages deep regional roots across the South and Southwest to build strong local customer relationships and high account retention.
Intimate market familiarity supports more accurate demand forecasting and localized assortments tailored to regional tastes and seasonality.
Visible community presence and a regional logistics footprint produce faster service responsiveness and steady referral-driven growth versus national competitors.
Ben E. Keith leverages a 1906 legacy to offer one-stop procurement across food and beverage, boosting AOV and cross-sell across ~100,000 customer accounts. Scale and cold-chain DCs plus WMS/TMS drive high fill rates, inventory turns, and reliable OTIF, supporting regional dominance in the South/Southwest. Exclusive AB InBev distribution (AB ~30% global beer share) anchors volume and shelf access, improving margins and supplier leverage.
| Metric | Fact |
|---|---|
| Founded | 1906 |
| Customer accounts | ~100,000 |
| Key supplier | AB InBev (~30% global beer share) |
| Region | South & Southwest US |
 Detailed Word Document
Delivers a strategic overview of Ben E. Keith’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to analyze its competitive position and future risks.

 Customizable Excel Spreadsheet
Provides a concise, industry-tailored SWOT matrix for Ben E. Keith to fast-track strategic alignment and relieve analysis bottlenecks for executives and strategy teams.
Ben E. Keith is privately held and headquartered in Fort Worth, Texas, with a heavy operational footprint in Texas and the Southwest, leaving it more exposed regionally than national peers. Regional downturns, severe weather, or demographic shifts can therefore disproportionately affect sales and inventory flows. Limited presence in fast-growth coastal and Sun Belt markets slows diversification and weakens negotiating leverage with national retail and chain accounts.
Heavy reliance on AB InBev and a few large food manufacturers concentrates risk: AB InBev holds roughly 28% of the global beer market and the top three brewers control about 60% globally, so contract shifts or portfolio realignments by these suppliers could meaningfully cut volumes and margins, skewing negotiating leverage toward mega-suppliers and making rapid pivots difficult if a brand underperforms.
Foodservice and beer distribution operate on low single-digit operating margins, so small cost shocks in fuel, labor, or shrink can quickly compress profitability; industry data shows many distributors run margins under 5%. Price competition from national broadliners limits pricing power, making it difficult to sustain service levels while protecting already-thin margins.
Ben E. Keith faces continual capital demands for warehouses, fleet, refrigeration and automation, keeping fixed-cost intensity high and raising breakeven during volume dips; technology upgrades add ongoing depreciation and integration risk, and capital constraints can slow geographic or category expansion.
Driver, selector and merchandiser roles are critical and hard to replace; ATA reports truck driver turnover hit 87% in 2023 and BLS annual unemployment averaged about 3.7% in 2024, tightening labor supply. Tight markets drive wage inflation and higher turnover costs (SHRM: replacement ≈6–9 months' salary), which can degrade service quality when understaffed and raise training and safety compliance complexity.
Ben E. Keith’s heavy TX/SW footprint and supplier concentration raise regional and counterparty risk. Low distributor margins and high capex intensity limit flexibility. Tight labor markets and 87% driver turnover raise costs and service risk.
| Metric | Value |
|---|---|
| AB InBev global share | 28% |
| Distributor margins | <5% |
| Driver turnover (ATA 2023) | 87% |
| BLS unemployment 2024 | 3.7% |
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get, including strengths, weaknesses, opportunities, and threats tailored to Ben E. Keith. Buy now to unlock the complete, editable version for immediate download.
Entering adjacent states and metros can unlock new accounts and improve route density, tapping into nearly 1 million U.S. foodservice outlets (2024, National Restaurant Association). Greenfield DCs or tuck-in acquisitions accelerate scale and lower per-unit distribution costs. Broader geographic coverage attracts regional and national chains seeking unified service. Diversification reduces concentration risk from local demand shocks.
Developing owned food brands can boost margins and differentiation, aligning with private-label penetration near 18% of U.S. grocery sales in 2023 (NielsenIQ). Chef services, menu engineering and beverage program design increase customer stickiness and repeat business. Premium mixers, N/A options and specialty SKUs target high-margin niches while value-added services deepen share of wallet.
Enhanced e-commerce portals and mobile apps streamline reordering, with mobile orders now exceeding 40% of foodservice transactions in many U.S. channels (2024 industry reports), shortening order cycles and boosting repeat purchases. Data-driven insights enable personalization that McKinsey found can lift revenues 10–15%, allowing Ben E. Keith to tailor assortments and promotions. Predictive demand planning has cut waste and stockouts by up to 30% in implemented pilots, lowering costs and improving fill rates. Integrated digital tools raise switching costs and lift customer satisfaction by simplifying ordering and enabling loyalty features.
Warehouse automation and voice-pick can boost accuracy and throughput—voice picking cuts errors up to 50% and automation raises pick rates 20–40%. Telematics and IoT temperature monitoring improve compliance and can cut fuel/energy use 8–12% while reducing cold‑chain spoilage ~20–30%. Electrification and alternative fuels can lower fuel and maintenance costs 30–50% over vehicle life, strengthening reliability and compliance.
Expanding craft, imports, RTD, spirits and better-for-you beverages taps high-growth segments—global RTD spirits grew ~18% in 2023 (IWSR) while non-alcoholic beverage sales rose ~10% (NielsenIQ, 2023), letting Ben E. Keith capture premium margins. Complementary non-alcoholic lines meet shifting preferences; curated assortments for emerging cuisines attract new operators, and a broader mix reduces dependence on any single category.
Expand regionally to reach ~1M US foodservice outlets (2024 NRA), enabling density and lower per-unit costs. Launch owned brands and high-growth beverage lines (RTD +18% 2023, non-alc +10% 2023) to lift margins. Scale digital, automation and telematics to cut waste/stockouts ~20–30% and fuel 8–12%.
| Opportunity | Impact | Key stat |
|---|---|---|
| Geographic expansion | Density, new accounts | ~1M outlets (2024) |
| Private brands & RTD | Higher margins | RTD +18% (2023) |
| Digital & automation | Cost/waste reduction | Waste -20–30% |
Alcohol distribution remains exposed to shifting state and local laws given the three-tier system in all 50 states and 17 control states; changes to franchise protections, pricing rules or route-to-market statutes can materially alter distributor economics. Increased licensing and reporting requirements have raised compliance complexity and administrative costs for regional distributors like Ben E. Keith. Litigation or policy shifts over franchise territory or direct-to-consumer sales could upend long-held territorial rights and margins.
Large beverage and food manufacturers such as Coca-Cola and PepsiCo wield strong bargaining leverage over distributors, tightening terms, marketing fund requirements, and product allocations. Consolidation among suppliers enables reassigning brands during portfolio realignments, potentially diverting accounts to competing distributors. Ben E. Keith’s dependence on major upstream partners increases vulnerability to strategic supplier moves.
Rivals range from national broadliners like Sysco (FY2024 sales ~79B) and US Foods (FY2024 sales ~32B) to regional distributors and specialty houses, intensifying price competition and rebate-driven margin pressure. National footprints can capture multi-state chain contracts, while craft-only and DSD players steadily erode category share in beer, deli, and specialty segments.
Driver and warehouse labor scarcity undermines Ben E. Keith’s service reliability, with 2024 industry surveys noting continued tightness in driver supply and warehouse staffing. Higher injury risk from material handling raises insurance premiums and downtime—OSHA data show warehousing remains a high-injury sector. Compliance lapses can trigger fines or operational halts, while persistent shortages drive up overtime and recruiting costs in 2024–2025.
Regulatory shifts in the three‑tier alcohol system, franchise law changes and DTC policy risk can erode distribution economics and territorial protections. Supplier consolidation and bargaining power from Coca‑Cola/Pepsi and large brands risk unfavorable terms or reassignment of accounts. Input cost volatility (fuel, freight, energy) and labor shortages (drivers/warehouse) amplify margin and service risks.
| Metric | Value (2024) |
|---|---|
| Diesel | $4.00/gal |
| Sysco sales | $79B |
| US Foods sales | $32B |
| Container rate swing | >50% |
| Food‑at‑home inflation | 3–4% YoY |


