
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
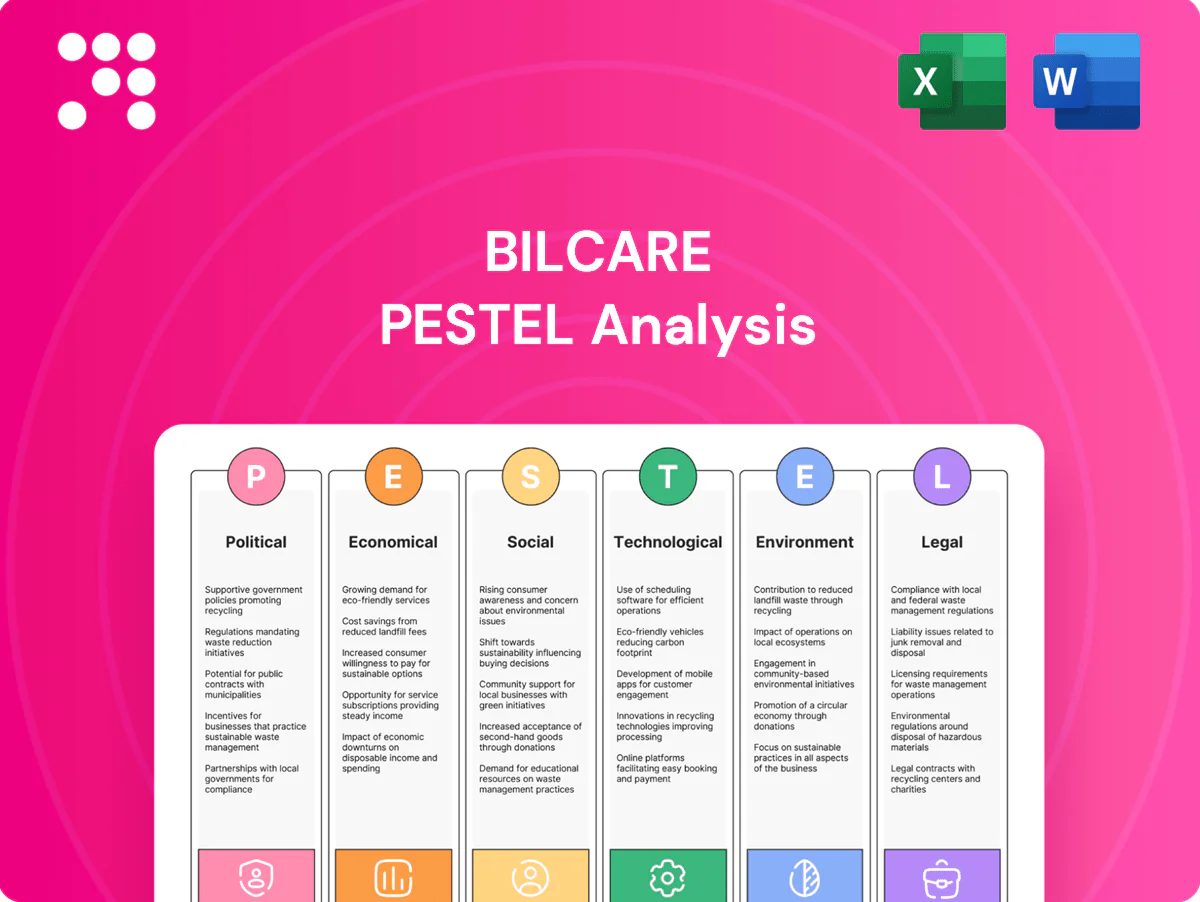
Gain a strategic edge with our PESTLE analysis tailored to Bilcare. Explore how political, economic, social, technological, legal and environmental forces shape its prospects and risks. Purchase the full report for actionable insights and downloadable, board-ready deliverables.
India’s emphasis on affordable medicines and supply security—within a pharma market ~US$45 billion in 2024—tightens packaging specs and procurement norms, favoring compliant blister and foil formats. Government incentives such as the Rs 15,000 crore PLI for pharmaceuticals boost domestic manufacturing and can shift contracts toward local packaging partners. Public programs like Ayushman Bharat (covering ~500 million beneficiaries) and essential-drug tenders create stable baseline demand if Bilcare aligns products to priority therapies and tender requirements.
Duties on aluminum foils, specialty polymers and additives can raise Bilcare’s input costs by roughly 5–15%, squeezing margins on pharma packaging; changes in FTAs or anti-dumping measures have historically swung competitiveness versus foreign converters by 10–20%. Hedging foreign-exchange exposure and dual-sourcing reduced procurement volatility in comparable firms by ~30–40%. Targeted localization of key inputs can cut import dependence towards sub-20% for critical lines, mitigating geopolitical and tariff risk.
Make-in-India and PLI schemes (combined outlay INR 1.97 lakh crore) extend manufacturing-linked incentives to pharma and medical devices, creating spillovers for packaging ecosystems and potential capex support and priority procurement. PLI for bulk drugs (approx. INR 6,940 crore) and device-focused plans boost eligibility when firms show technology upgrades and job creation. Strategic clustering near PLI beneficiaries cuts logistics costs and lead times, improving competitiveness.
Stronger enforcement against counterfeit medicines boosts demand for track-and-trace and security features; the global pharmaceutical serialization market was about USD 2.4B in 2023 and WHO estimates 10.5% of medicines in low/middle-income countries may be substandard or falsified. Variability in state-level enforcement fragments adoption timelines, while Bilcare’s anti-counterfeit portfolio aligns with central patient-safety drives and advocacy/pilot programs can accelerate standards uptake.
Stable governance supports long-horizon investments in plants and validation cycles (often 18–24 months). Public health program expansions, notably Ayushman Bharat covering ~500 million beneficiaries, drive steady orders but require competitive pricing and strict compliance. Payment cycles in government channels, commonly 60–120 days, affect working capital, while transparent e-tendering and vendor-rating systems reward quality and reliability.
India’s ~US$45B pharma market (2024) and Ayushman Bharat (~500M beneficiaries) drive steady demand for compliant blister/foil formats. PLI schemes (Rs15,000cr; total INR1.97L cr) and device/drug PLIs (e.g., INR6,940cr) favor local packagers. Tariffs can raise input costs ~5–15%, while serialization market ~USD2.4B (2023) boosts anti-counterfeit demand; govt payment cycles 60–120 days affect working capital.
| Metric | Value |
|---|---|
| Pharma market (2024) | ~US$45B |
| Ayushman Bharat | ~500M |
| PLI outlay | INR1.97L cr |
| Serialization market (2023) | USD2.4B |
| Input tariff impact | +5–15% |
 Detailed Word Document
Explores how macro-environmental forces uniquely impact Bilcare across Political, Economic, Social, Technological, Environmental and Legal dimensions, with data-backed trends and region/industry-specific examples; designed for executives and investors to identify risks, opportunities and forward-looking scenarios ready for inclusion in plans, decks or reports.

 Customizable Excel Spreadsheet
A concise, visually segmented PESTLE summary for Bilcare that’s easy to drop into presentations, share across teams, and editable with notes for local market or business-line context—ideal for aligning strategy discussions and highlighting external risks quickly.
Aluminum foil and polymer resin costs are cyclical and FX-sensitive, with LME aluminum averaging about $2,300/ton in 2024 and common resin grades near $1,400/ton that year, amplifying input-cost swings for Bilcare. INR weakness — around 82–84/USD in 2024–25 — raises imported input and specialized-capex bills. Pricing formulas with pass-through clauses preserve margins, while proactive hedging and tighter inventory turns smooth earnings volatility.
Given prior stress, cost of capital and lender confidence are pivotal with RBI repo at 6.5% (June 2025) and typical corporate lending spreads ~250–400 bps; a phased revival focused on niche, higher‑margin SKUs (packaging industry EBITDA ~15% in 2024) can improve cash conversion; asset‑light collaborations/tolling cut upfront capex by ~30–50% and credible turnaround KPIs restore supplier and customer trust.
Essential medicines and generics, which account for roughly 80% of prescriptions by volume, provide defensive end-market demand supporting Bilcare's blister and barrier films; India’s pharma market was about $50 billion in 2024. Strong domestic formulations growth and exports—Indian pharma exports near $25 billion in FY2024—sustain packaging volumes. Recovery in clinical trial activity can revive contract-supply services, while diversification into nutraceuticals and diagnostics buffers cyclical risk.
Export market access to regulated markets (US/EU) gives Bilcare pricing power but raises compliance costs and certification timelines; regulatory overheads in pharma packaging can increase time-to-market and cost basis materially. Currency advantages—INR near 82–84/USD in 2024—improve competitiveness into Africa, LATAM and SE Asia. Volatile freight: container rates fell ~50% from 2021 peaks to 2024 averages, yet logistics still drive landed-cost risk; local warehousing or converter partnerships raise service levels and reduce lead times.
High-barrier laminates, cold-form foils and specialty polymers deliver materially higher margins than commodity films, with serialization and security solutions shifting revenue toward recurring, fee-based streams; 2024 industry data show serialization adoption above 70% in regulated markets. Value-engineering for downgauging preserves customer economics while maintaining performance, and aftermarket services increase stickiness and lifetime value.
Aluminum/resin price swings (LME Al ~$2,300/t, resins ~$1,400/t in 2024) and INR ~82–84/USD (2024–25) drive input-cost volatility but contract pass-throughs and hedging cushion margins. Higher cost of capital (RBI repo 6.5% Jun 2025; lending spreads ~250–400 bps) pressures capex; asset-light tolling can cut upfront capex 30–50%. Strong pharma demand (India $50B, exports ~$25B in 2024) supports packaging volumes.
| Metric | Value |
|---|---|
| LME Al | $2,300/t (2024) |
| Resin | $1,400/t (2024) |
| INR | 82–84/USD (2024–25) |
| RBI repo | 6.5% (Jun 2025) |
The preview shown here is the exact Bilcare PESTLE Analysis you’ll receive after purchase—fully formatted, comprehensive, and ready to use. The content, structure, and insights visible in this sample are the final deliverable with no placeholders or surprises. Download the finished file instantly after checkout.
Rising patient awareness of drug authenticity—WHO estimates up to 10% of medical products in low- and middle-income countries may be substandard or falsified—elevates packaging’s role in safety. Tamper-evident and anti-counterfeit features increasingly drive trust, and EU FMD (2019) plus US DSCSA implementation timelines (through 2023) push serialization. Hospitals and pharmacies report growing preference for serialized packs, and targeted education with regulators, buyers and clinicians accelerates adoption of premium safety features.
Aging populations and rising chronic disease burden—UN: 1 billion people aged 60+ in 2020, heading toward 2.1 billion by 2050—drive higher prescription volumes and expanded adherence programs; WHO reports noncommunicable diseases account for 74% of global deaths. Blister designs that improve dosing clarity and readability demonstrably support adherence outcomes. Unit-dose formats fit hospital and elder-care workflows, shifting demand toward high moisture/oxygen barrier packaging solutions.
Price sensitivity in emerging markets forces Bilcare to cut packaging costs as pharma packaging demand in Asia grew ~6% in 2024; cost-effective, regulatory-compliant substrates win share in government programs like India’s Jan Aushadhi (≈9,000 outlets by 2024). Pack-size optimization can cut waste up to 30% and lower unit cost, while clear multilingual labeling improves adherence by ~15–20% in diverse populations.
Brand reputation recovery after past financial setbacks requires proactive communication on reliability and compliance; demonstrating sustained OTIF delivery to pharma clients rebuilds credibility and reduces churn. Maintaining current certifications and audit readiness signals operational robustness to regulators and partners, while visible customer co-development projects showcase technical capability and deepen client trust.
Rising patient awareness (WHO: ~10% substandard meds in LMICs) boosts demand for tamper-evident, serialized packs (EU FMD, US DSCSA). Aging populations (UN: 1B aged 60+ in 2020; 2.1B by 2050) and NCD burden increase unit-dose and adherence-focused formats. Price sensitivity in EMs (Asia packaging growth ~6% in 2024) favors low-cost compliant substrates; automation (~40% lines in 2024) drives reskilling needs.
| Factor | Key stat |
|---|---|
| Counterfeits | ~10% (WHO) |
| Aging | 1B (2020) → 2.1B (2050) |
| Market | USD 61B (2023) |
| Automation | ~40% (2024) |
Advances in PVdC alternatives, Aclar films and multilayer laminates improve barrier performance and shelf life, while material science forces trade-offs between barrier, cost and recyclability that steer design choices; Bilcare's in-house formulation IP can differentiate niche pharma uses, and client qualification cycles of 12–24 months create meaningful switching costs for substitutes.
Compliance with GS1 standards—used by over 2 million companies across 100+ countries—plus global aggregation mandates (eg DSCSA milestones reached in Nov 2023) is driving uptake of serialization. Integrating visible codes, covert features and centralized databases targets WHO-estimated ~10% global prevalence of falsified/substandard medicines. Cloud platforms and APIs provide real-time supply-chain visibility, while end-to-end kits boost customer stickiness and lifetime value.
RFID/NFC, invisible taggants and smartphone verification raise on-pack security for pharma, addressing a WHO estimate that 10.5% of medicines in low- and middle-income countries are substandard or falsified. Scan analytics feed market intelligence and diversion detection dashboards, enabling rapid recall or route-to-market adjustments. Low-cost, scalable features are essential for generics; partnering with specialist tech vendors shortens time-to-market and reduces capex.
Modern extrusion, calendaring and slitting lines improve yield and consistency for pharma packaging, while inline inspection and machine vision significantly cut defect escape and rework. MES and QMS integration ensure data integrity and support 21 CFR Part 11 compliance across production records. Retrofitting legacy assets extends operational life with lower capex versus full replacement.
Bilcare's push for mono-material and fully recyclable structures aligns with client ESG mandates and EU packaging rules; solvent-free coatings can cut VOC emissions by >90% and downgauging reduces material use and CO2 intensity, supporting cost and compliance goals. Trials with bio-based polymers (global bioplastics production ~2.2 Mt in 2023) open substitution paths, and LCA-backed claims enable customers to report verified Scope 3 benefits.
Modern barrier films, mono-material designs and solvent-free coatings cut VOCs >90% and lower CO2 intensity; bioplastics (2.2 Mt in 2023) enable substitution. Serialization (GS1: >2M companies) and DSCSA (Nov 2023) drive digital traceability; RFID/NFC and taggants reduce falsified meds (~10.5% WHO). MES/QMS and inline vision boost yield, compliance and shorten qualification cycles (12–24 months).
| Metric | Value |
|---|---|
| GS1 reach | >2M firms |
| DSCSA | Milestones Nov 2023 |
| Falsified meds | ~10.5% WHO |
| Bioplastics | 2.2 Mt (2023) |
| VOC reduction | >90% |
Compliance with CDSCO (Schedule M), US FDA (21 CFR parts 210/211) and EMA (EudraLex Vol. 4) is non-negotiable for Bilcare, shaping facility design and release criteria.
Change controls and validation protocols strictly govern material modifications, with documented risk assessments and validation master plans required for any change.
Data integrity and full traceability are audit focal points, emphasizing ALCOA+ principles and electronic batch records.
Regular internal audits and corrective action trends serve to pre-empt regulatory observations and support continuous compliance.
Mandates for barcoding and serialization have tightened globally, notably the US DSCSA full unit-level traceability deadline of November 27, 2023 and the EU Falsified Medicines Directive in force since 2019. Legal standards for tamper-evidence vary by market, while WHO estimates up to 10% of medicines in low- and middle-income countries are substandard or falsified. Offering compliant security features reduces client liability and market risk, and robust documentation and efficacy proofs support faster adoption.
Protecting proprietary polymers and security features sustains Bilcare's competitive edge in a global pharmaceutical packaging market valued at about USD 75.5 billion in 2023 and growing ~6.5% CAGR to 2030. Licensing or JV models can monetize technology while sharing development and market risk. Freedom-to-operate analyses mitigate infringement exposure. Robust NDAs and supplier contracts secure critical know-how.
Environment and EPR compliance: Plastic Waste Management Rules and EPR frameworks require traceability and producer take-back; hazardous waste and solvent emissions must meet CPCB/MoEF limits. Non-compliance risks fines, production stoppages and permit suspension. Early alignment with certified recyclers and take-back partners streamlines reporting and reduces operational and financial risk.
Restructuring and creditor obligations constrain Bilcare’s operational flexibility as legacy liabilities and any formal insolvency processes dictate cash flow prioritization, asset dispositions and rehiring limits. Transparent settlements and clear creditor agreements boost vendor and customer confidence, aiding supply continuity and contract performance. Revival efforts often require contract novations and consent from secured creditors; proactive legal risk management preserves business continuity and protects manufacturing licenses.
Regulatory compliance (CDSCO/US FDA/EMA) and serialization mandates (US DSCSA unit-level from 27‑Nov‑2023) set facility, validation and release requirements. Data integrity (ALCOA+) and traceability audits drive EBRs and supplier controls. EPR/plastic rules and CPCB limits raise disposal liabilities; non-compliance risks fines, stoppages. Strong IP, NDAs and FTO analyses protect polymers and enable licensing revenue.
| Item | Metric (2023/2025) | Impact |
|---|---|---|
| Pharma packaging market | USD 75.5bn (2023), ~6.5% CAGR | Growth opportunity |
| DSCSA | Unit-level live 27‑Nov‑2023 | Supply compliance cost |
| Substandard meds | WHO ≤10% in LMICs | Security demand |
Policy and customer pressure increasingly require recyclable or reusable pharmaceutical packaging, with global plastic recycling rates still low at around 9% prompting urgent redesign. The market is shifting toward mono-material blisters and separable PE/PET streams to improve recyclability and collection economics. Design-for-recycling must balance drug barrier and shelf-life requirements, while clear on-pack labeling improves downstream sorting and recovery rates.
Extrusion and foil processes at Bilcare are energy-intensive, with packaging extrusion often among the highest industrial energy users; transition to onsite renewable power and waste-heat recovery can cut energy use by up to 30% and materially lower Scope 2 emissions. Pharma clients increasingly request carbon reporting—over 20,000 companies now disclose to CDP—so efficiency projects deliver both cost savings and measurable ESG benefits.
Coating and printing at Bilcare involve solvents that emit VOCs subject to EU Industrial Emissions Directive and national air-quality rules; non-compliance risks enforcement actions and supply-chain disruption. Adoption of solventless and water-based chemistries can cut VOCs often by more than 80%, lowering compliance costs and lifecycle emissions. Continuous ambient VOC monitoring and public reporting—used by many pharma-packaging peers—strengthens regulator and customer trust.
Yield losses in slitting and forming in pharma-grade foil/film operations typically drive 2–5% scrap rates, increasing material costs and CO2 footprint; Bilcare’s closed-loop regrind and buyback programs have been shown industry-wide to recover up to 80–90% of scrap, cutting virgin resin purchases and waste disposal costs. Process analytics (IIoT/vision) target loss hotspots and can reduce scrap by 10–25%, while tighter supplier specs and incoming QC stabilize run quality and lower variability.
Extreme weather increasingly disrupts utilities and transport, with climate events driving supply-chain delays and local outages that can spike costs and downtime for Bilcare’s packaging operations.
Site hardening, backup power and contingency plans protect uptime; diversified suppliers and regional hubs cut single‑point risk, while temperature‑controlled logistics preserve product integrity, reducing spoilage by ~25–30% in pharma cold chains.
Regulatory and customer pressure push recyclable mono-material blisters as global plastic recycling remains ~9%, forcing redesigns that balance barrier and shelf-life. Energy-intensive extrusion/foil can cut energy use ~30% via onsite renewables and waste-heat recovery, lowering Scope 2 and meeting growing carbon reporting (20,000+ firms report to CDP). Solventless coatings reduce VOCs >80%, scrap 2–5% recovered 80–90% via regrind and analytics.
| Metric | Value |
|---|---|
| Global plastic recycling rate | ~9% |
| Energy cut from renewables/WHR | ~30% |
| VOC reduction (solventless) | >80% |
| Typical scrap | 2–5% |
| Regrind recovery | 80–90% |


