
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
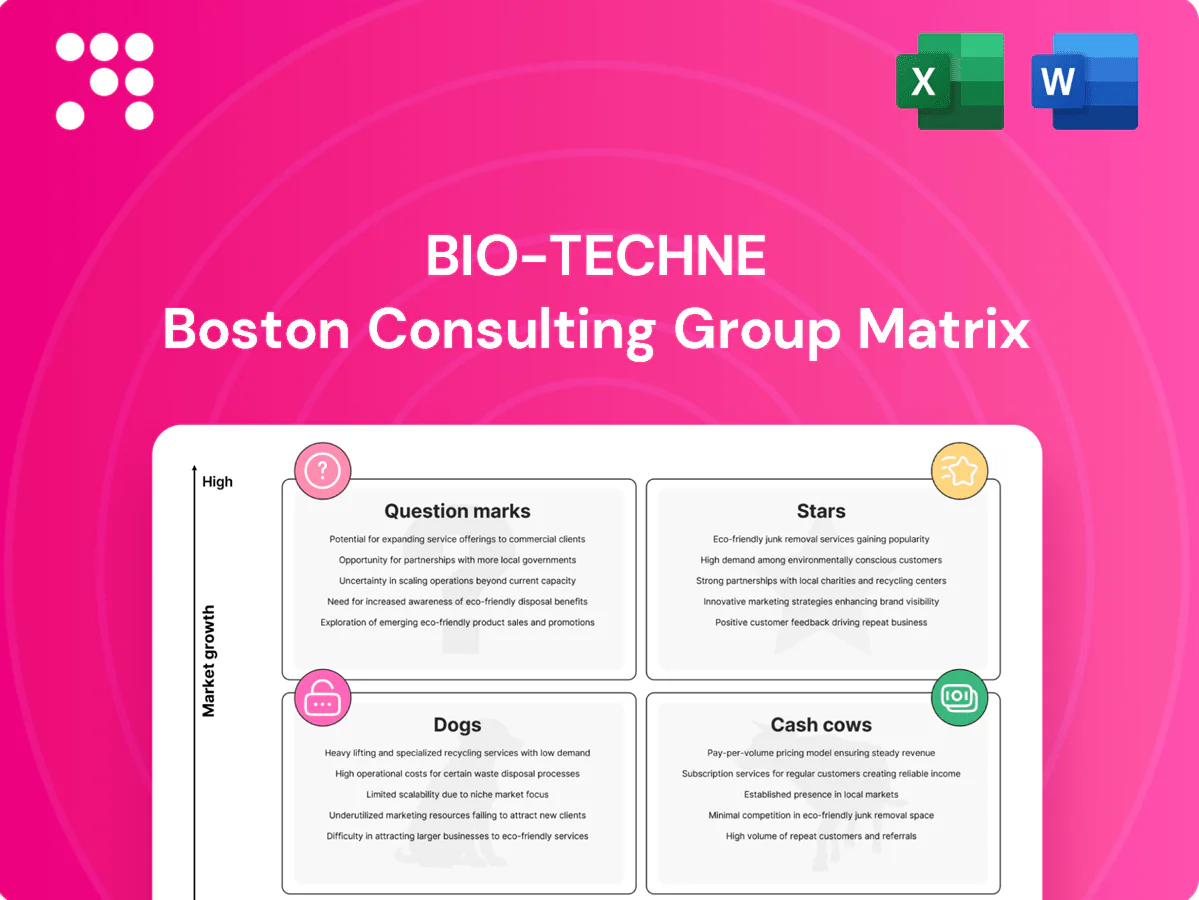
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Bio-Techne’s product lines sit—Stars, Cash Cows, Dogs, or Question Marks? This snapshot teases the shape of their portfolio; the full BCG Matrix gives you quadrant-by-quadrant clarity, data-backed recommendations, and a ready-to-use strategic plan. Buy the full report for a detailed Word write-up plus an Excel summary you can plug into presentations and board decks. Save time, cut through the noise, and make confident investment decisions—purchase now for instant access.
High growth demand from translational and pharma users puts spatial biology in the fast lane, with Bio-Techne expanding footprint via instruments and assays that map proteins and RNA in tissue. Bio-Techne reported fiscal 2024 revenue of approximately $1.12 billion while spatial share is rising and workflows lock in consumables. Keep fueling placements and field support to cement leadership before the market settles.
RNAscope has become a go-to for sensitive RNA detection in tissue across research and clinical studies, cited in over 20,000 publications as of 2024 and driving strong demand in oncology and neuroscience workflows. Adoption curves are still climbing, with Bio-Techne reporting 2024 revenues of roughly $1.34 billion that support scale-up. Strong brand equity and sticky protocols drive repeat reagent and instrument spend. Continued investment in applications, automation, and KOL training will defend the lead and widen the moat.
Automated immunoassay systems like Simple Western and Ella streamline protein workflows, driving instrument base growth of ~15% in 2024 and supporting Bio-Techne’s FY2024 revenue of roughly $1.18B; installed base exceeds ~6,000 labs. High-margin consumables (~68% gross margin in 2024) compound recurring revenue. Competitors exist, but validated datasets and switching costs preserve share; pushing placements into biopharma QC and top-tier academia will amplify network effects.
GMP cell and gene therapy reagents: clinical manufacturing requires consistent, compliant cytokines and media components as programs scale; with over 2,000 cell and gene therapy programs in clinic in 2024, demand is accelerating. Bio-Techne’s quality and reliability position it to win preferred-vendor status; scaling QC and technical support is critical to secure long-term supply agreements.
Proteomic workflow integrations are accelerating as end-to-end kits and reagents that link sample prep to readout gained momentum in 2024, with kit bundle demand rising ~25% year-over-year and Bio-Techne reporting proteomics segment growth near 12% Y/Y. Bundles improve outcomes and simplify purchasing, nudging market share up as standardized lab workflows make preferred solutions default choices. Keep building compatibility and enriched data packages to cement category leadership.
High-growth Stars: spatial biology, RNAscope, automated immunoassays and GMP reagents drive rapid adoption and recurring consumables revenue; Bio-Techne reported FY2024 revenues ~ $1.12–1.34B across segments with >6,000 installed instruments. Consumables gross margin ~68% and kit bundle demand +25% Y/Y; >2,000 cell & gene programs in clinic bolster long-term supply contracts.
| Metric | 2024 |
|---|---|
| Company revenue (segment range) | $1.12–1.34B |
| Installed instruments | >6,000 labs |
| Consumables gross margin | ~68% |
| Kit bundle demand growth | +25% Y/Y |
| Cell & gene programs | >2,000 |
 Detailed Word Document
In-depth BCG analysis of Bio-Techne's portfolio, outlining Stars, Cash Cows, Question Marks and Dogs with investment guidance.

 Customizable Excel Spreadsheet
One-page Bio-Techne BCG Matrix placing each unit in a quadrant to simplify decisions and spotlight priorities.
Recombinant proteins and cytokines remain a cash cow for Bio-Techne, with core catalog proteins used by thousands of labs worldwide and supporting Bio-Techne’s FY2024 revenue of about $1.06 billion. Market growth is modest (low-single-digit CAGR) but high volume and strong margins sustain cash flow. Brand trust and lot-to-lot consistency defend share; optimize manufacturing and inventory turns to maintain steady operating cash.
Antibodies and ELISA kits are mature, widely cited tools embedded in SOPs and academic methods, driving sticky demand despite price pressure; Bio-Techne reported fiscal 2024 revenue near $1.35B with reagents/consumables forming the backbone of recurring sales. Recurring consumables yield predictable cash flow and high retention; scale, validation datasets and technical support sustain premium positioning. Prioritize SKU rationalization and launch verified premium panels to protect margins and lift ASPs.
Tocris small molecules are an established discovery toolset within Bio-Techne, with a catalog of over 16,000 validated compounds and a decades-long citation record that drives low switching costs among researchers. Growth is steady rather than rapid, yet the portfolio delivers reliable gross profit and high repeat purchase behavior. Management focuses on maintaining quality and streamlining long-tail SKUs to improve operating efficiency and margin contribution.
ProteinSimple consumables act as cash cows: installed base drives recurring purchases and high attachment rates after instrument placement, underpinning predictable revenue; Bio-Techne reported fiscal 2024 revenue of approximately $1.34 billion, with consumables and reagents a major recurring component.
Market segments are mature and usage is habitual, so strong service, on-time delivery and warranty responsiveness sustain loyalty; leaning into service contracts and auto-replenish programs lifts customer lifetime value and reduces churn.
Diagnostics quality controls are a cash cow for Bio-Techne: dependable, recurring purchases from clinical labs mean predictable volumes and low growth but attractive margins when operations are tight; Bio-Techne reported FY2024 revenue near $1.18B, with diagnostics contributing a stable, high-margin annuity.
Recombinant proteins/cytokines, antibodies/ELISA, Tocris small molecules, ProteinSimple consumables and diagnostics QC form Bio-Techne cash cows: high-repeat consumables, strong margins, low-single-digit growth and high customer stickiness; prioritize manufacturing efficiency, SKU rationalization, service contracts and auto-replenish to protect cash flow.
| Bio-Techne FY2024 Revenue | $1.34B |
|---|---|
| Segments | Characteristics / Growth |
| Recombinant proteins & cytokines | High margin, low-single-digit CAGR |
| Antibodies & ELISA | Sticky demand, predictable consumables |
| Tocris | Stable repeat purchases |
| ProteinSimple consumables | Installed-base annuity |
| Diagnostics QC | Clinical stickiness, low growth |
The file you're previewing is the exact Bio‑Techne BCG Matrix you'll receive after purchase. No watermarks or demo content—just the polished, fully formatted report built for strategic clarity. It's ready to download, edit, print, or present straight away. Market-informed and professionally designed, no surprises, no extra steps.
Legacy low-throughput benchtop systems sit in saturated niches with minimal upgrades and low utilization, tying up field service and spare-parts resources while contributing little to growth. Price cuts rarely boost demand meaningfully and often compress margins. Prioritize formal sunset plans, reallocate service capacity and spare inventory to higher-velocity platforms to improve ROI and support revenue growth.
Highly interchangeable basic reagents face relentless price competition, compressing unit economics even as Bio-Techne reported $1.44B revenue in FY2024 and ~66% gross margin for the company overall. Differentiation is thin so brand rarely commands a premium in distributor channels. Margins erode as distributors push the lowest-cost SKUs, driving downward pricing pressure. Trim SKUs and exit the long tail where share is minimal to protect core margins.
Niche custom projects consume specialist time and don’t scale: they often account for under 5% of revenue while tying up more than 15% of expert R&D hours, rarely converting into catalog products or lasting contracts; cash impact is neutral at best after overhead, with margin erosion of ~10–20% versus catalog SKUs. Reduce acceptance or reprice to reflect true cost-to-serve.
Dogs:
Non-core accessories dilute strategic focus: in FY2024 Bio-Techne reported ~$1.2B revenue while accessory lines account for under 3% of sales, with share remaining low and market demand roughly flat year-over-year, trapping working capital and lowering margins; divest or bundle selectively only when they demonstrably lift core reagent/instrument sales.
Dogs: obsolete assay formats and non-core accessories generate negligible growth with market ~0% and negative product margins; Bio-Techne FY2024 revenue $1.44B, company gross margin ~66%, accessories <3% of sales, >$10M working capital tied. Prioritize phase-out/divest, migrate users to current platforms, reallocate service and spare parts to high-velocity lines.
| Metric | Value |
|---|---|
| FY2024 revenue | $1.44B |
| Gross margin | ~66% |
| Accessory sales | <3% |
| Market growth (dogs) | ~0% |
| Working capital tied | >$10M |
Combining protein, RNA, and DNA in one spatial run is a hot frontier in 2024, with market reports projecting roughly a 20% CAGR for spatial biology through 2030 and intense activity from rivals 10x Genomics, NanoString, and Akoya. Growth is explosive but standards remain unsettled and interoperability is weak. Bio-Techne can win by simplifying workflows and making data analysis painless. Heavy investment now could flip this into a Star.
Exosome-based liquid biopsy shows strong promise in urology and oncology, with the broader liquid biopsy market estimated at about US$6 billion in 2024 and projected double-digit CAGR. Clinical adoption remains uneven and reimbursement pathways are still forming, limiting near-term revenue. If demonstrated utility and payer coverage expand, scale can accelerate rapidly. Decision: double down on clinical evidence generation or partner with payers/diagnostic labs to accelerate access.
Single-cell proteomics is a 2024 question mark for Bio-Techne: researchers demand protein-level resolution at single-cell scale and the space is expanding rapidly but remains fragmented across evolving platforms. Bio-Techne’s protein-reagent heritage and supply-chain scale position it to translate assays if reagent-platform compatibility is broad. Rapid share gains are feasible by co-developing kits with top platform partners to become ecosystem-standard reagents.
Automated, closed sample prep addresses critical manufacturing bottlenecks in cell and gene therapy as demand scales with over 2,000 active CGT trials globally in 2024; commercial adoption remains early but accelerating. Early GMP-validated automation pilots can convert interest into multi-year contracts and significant share if validated at scale. Invest in GMP-grade workflows and regulatory validations now to capture rising trial-driven demand.
AI-driven assay analysis software sits as a Question Mark for Bio-Techne: labs are drowning in complex imaging and multiplex data and smart analytics could become the sticky layer that drives consumables pull-through; Bio-Techne reported FY2024 revenue of about $1.37B, giving capacity to invest; market is nascent and crowded with startups, so partner, test with KOL labs, and package with instruments to see if it sticks.
Spatial biology (~20% CAGR to 2030), exosome liquid biopsy (market ≈ US$6B in 2024), single-cell proteomics, CGT automation (>2,000 active CGT trials in 2024) and AI assay software (Bio-Techne FY2024 revenue ≈ US$1.37B) are Question Marks: high growth but uncertain adoption—prioritize partnerships, GMP/clinical validation, and instrument-software bundling to convert to Stars.
| Segment | 2024 Signal | Priority |
|---|---|---|
| Spatial biology | ~20% CAGR to 2030 | Workflow simplification |
| Exosome LBx | Market ≈ US$6B | Evidence & payer strategy |
| CGT automation | >2,000 trials | GMP validation |
| AI software | FY2024 rev US$1.37B | KOL pilots/packaging |


