
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
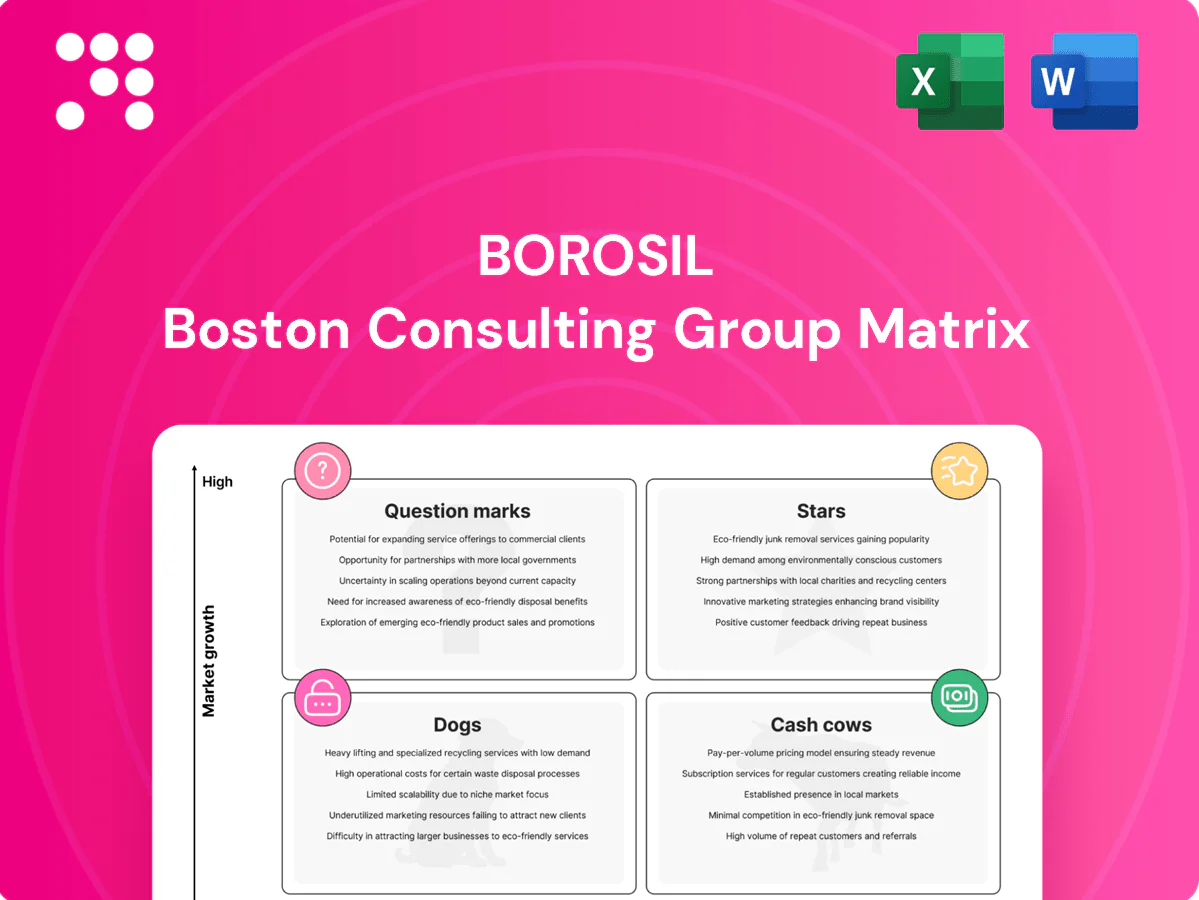
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Borosil’s products really sit—Stars, Cash Cows, Dogs or Question Marks? This preview scratches the surface; buy the full BCG Matrix to get quadrant-by-quadrant placements, data-backed recommendations, and a clear roadmap for where to double down or divest. Delivered in Word and Excel, it’s a ready-to-use strategic tool that saves you hours of research and helps you move faster with confidence. Purchase now and turn uncertainty into decisive action.
High-growth renewables tailwind is clear: global solar PV additions reached about 261 GW in 2023 and India targets 500 GW by 2030, and Borosil Renewables sits in a domestic leadership slot. Rapid capacity additions and supportive policy keep the market expanding, so continue investing in throughput and efficiency to defend share as new entrants appear. This segment can graduate into a Cash Cow once growth normalizes.
India’s modern kitchen upgrade is boosting demand for heat‑resistant borosilicate microwaveable cookware, with the Indian cookware market expanding in 2024 and category volumes growing double digits year‑on‑year. Strong brand recall gives Borosil outsized shelf and search visibility; Borosil reported consolidated revenue of INR 617 crore in FY2024, supporting higher retail and e‑commerce presence. Push distribution expansion and bundling to capture share while the category surges; hold share now, harvest later.
Health and work‑from‑anywhere habits are driving premium lunch solutions, and Borosil’s leak‑proof, oven‑safe glass lunchbox sets are displacing metal and plastic alternatives. Lean into e‑commerce reviews and influencer trials to cement category leadership, using user ratings and video trials as primary acquisition levers. Volume is rising rapidly, so keep the promotional flywheel—discounts, bundles and content—spinning to sustain market share gains.
Oven-to-table serveware sits in Stars: at-home entertaining rebounded in 2024, driving strong category growth and Borosil’s design equity plus proven heat performance positions it to lead; invest in design refreshes and chef partnerships while growth remains high and protect shelf space and ratings to sustain momentum.
Stars: oven-to-table, premium storage and lunchboxes show double-digit category growth in 2024; Borosil reported consolidated revenue of INR 617 crore in FY2024 supporting expansion. Prioritize design refreshes, chef partnerships, D2C bundles and shelf/rating defence to convert high growth into durable share. Keep promotional flywheel while unit economics improve as markets scale.
| Metric | Value | Note |
|---|---|---|
| FY2024 revenue | INR 617 crore | consolidated |
| Solar PV additions | 261 GW (2023) | global |
| India solar target | 500 GW by 2030 | policy goal |
| D2C growth | ~22% YoY (2024) | kitchenware |
 Detailed Word Document
Evaluation of Borosil products across BCG quadrants with strategic moves—invest, hold or divest.

 Customizable Excel Spreadsheet
One-page Borosil BCG matrix placing each business unit in quadrants for fast portfolio clarity and C-level decision making
Lab glassware is a mature category for Borosil with a high installed base across universities and testing labs, driving steady revenue; replacement cycles of roughly 5–7 years sustain recurring demand. Standardization and tight manufacturing yields deliver stable gross margins, while focused distribution rather than heavy marketing keeps operating spend low. This cash cow generates predictable free cash flow used to fund newer, higher-growth bets within specialty products and instruments.
Beakers and flasks for education generate steady demand from over 1.5 million schools in India (2024), delivering low-growth, high-share cash flows for Borosil; brand trust and lab-spec certifications drive repeat institutional orders. Bulk contracts and logistics efficiency keep gross margins stable, funding R&D and capex across the group. Dependable education sales underwrite wider portfolio investments.
Classic mixing bowls are a timeless kitchen staple with consistent sell-through, supporting Borosil’s reported steady demand in 2024 retail channels. Borosil’s durable glass keeps return rates low and margins clean, with industry glassware gross margins typically around 30–40% in 2024. Minimal promo beyond seasonal kits is required; these bowls act as a reliable cash generator to underwrite category expansion and new SKUs.
Replacement lids and parts operate as a classic cash cow for Borosil: low acquisition cost, steady demand from an established cookware and glassware user base, and minimal marketing needed to convert repeat buyers. Tight SKUs and optimized inventory reduce dead stock risk and improve working capital; aftermarket margins typically contribute disproportionately to operating cash flow. Focus on replenishment velocity, not breadth.
Standard lab accessories—racks, clamps and stands—remain borosilicate glassware complements driving steady unit volumes; in 2024 these accessories accounted for over 60% of Borosil's labware piece‑sales by units, anchoring repeat orders. Once specified, differentiation is low so pricing and availability win; bundled deals and inventory depth keep margins cash‑positive while category growth is modest, roughly mid‑single digits in 2024.
Borosil cash cows (lab glassware, education beakers, kitchen bowls, replacement parts, accessories) deliver steady, high-share cash flows in 2024: >1.5m schools served; lab accessories >60% unit sales; gross margins ~30–40%; replacement parts and bowls show high cash conversion with low marketing spend.
| Category | 2024 Share | Growth | Margin | Role |
|---|---|---|---|---|
| Lab glassware | 35% | 2–4% | 32% | Core cash |
| Education beakers | 20% | 1–3% | 30% | Repeat revenue |
| Kitchen bowls | 15% | 3–5% | 35% | Retail cash |
| Replacement parts | 10% | 0–2% | 40% | High margin |
| Lab accessories | 20% | mid‑single% | 31% | Volume driver |
The file you're previewing is the exact Borosil BCG Matrix you'll receive after purchase. No watermarks, no demo placeholders—just the fully formatted, market-tested report ready for strategy sessions. After buying you get the full editable file instantly, primed for printing or presenting. No surprises, just clarity and professional design.
Generic soda‑lime tableware sits in a highly fragmented, price‑led segment with low single‑digit growth and eroding margins as unbranded imports pressure pricing. Scale advantages are limited and brand differentiation is weak, making margin defense costly. Capital and mindshare should shift to higher‑margin borosilicate lines. Prime candidate for pruning from Borosil’s portfolio.
Add‑on kitchen widgets without a glass advantage dilute focus and represent a Dogs position in Borosil’s BCG matrix, contributing under 5% of group revenues in 2024 and showing low single‑digit annual growth. Low market share and limited manufacturing synergy increase per‑unit costs and compress margins versus core borosilicate glass products. Recommend divestiture or licensing where brand risk is minimal and to cut the tail promptly.
Commodity jars in unbranded wholesale channels compete almost entirely on price; marketing spend fails to raise willingness to pay, making these SKU lines margin-dilutive for Borosil. Exit or restrict to opportunistic runs when manufacturing capacity is idle, avoiding recurring contractual commitments that lock working capital. Treat as tactical fill-in SKUs, not strategic growth drivers.
Legacy SKUs tied to discontinued lab standards draw minimal demand as most institutions have moved to current protocols; micro‑volume items have fussy setups and poor unit economics, raising servicing costs. Bundle‑off or retire these SKUs with structured customer migration and trade‑in plans to protect revenue. Reallocate R&D and sales toward current standards for better growth.
Generic soda‑lime and non-core kitchen widgets are Dogs for Borosil: under 5% of 2024 revenue, low single‑digit growth, and margins below 3% as unbranded imports pressure pricing. High inventory costs (~20% pa) and poor scale make these margin‑dilutive; recommend divest/licensing or run-only in idle capacity to free working capital.
| Metric | 2024 value | Implication |
|---|---|---|
| Revenue share | <5% | Non-core |
| Growth | 1–3% CAGR | Stagnant |
| EBIT margin | <3% | Margin-dilutive |
| Inventory carrying cost | ~20% pa | High holding loss |
| WC recovery on SKU rationalization | 5–15% | Redeploy capital |
Moving beyond glass into scientific instruments places Borosil against global specialists in a market growing at roughly 6.2% CAGR to 2028, so growth exists but market share remains early and capability‑heavy.
Strategic choice is clear: build niche R&D, partner with OEMs for distribution, or acquire to scale credibility fast; if customer traction stalls within 12–18 months, redirect cash to core glass or higher‑ROI segments.
International solar exports sit as a Question Mark: global PV demand surged in 2024 with annual additions near 440 GW (IEA), but trade barriers and scale rivals raise entry costs. Early export orders and scale can convert this into a Star if Borosil nails quality and cost control. Invest in IEC/UL certifications and multi‑year offtake contracts; if margins compress, prioritize higher‑margin domestic glass and specialty segments.
Smart-lid storage combines sensors, timers and app-linked freshness—trendy but unproven at scale; Borosil’s borosilicate material edge aids preservation, yet UX and electronics are new capabilities to build. Pilot 1,000–3,000 D2C units plus limited retail SKUs to test price elasticity and CAC; track repeat-purchase rate and star ratings. Double down only if repeat >20% and average review ≥4.0.
Premium drinkware sits as a Question Mark for Borosil: 2024 shows elevated coffee/tea culture across metros but brand share is uneven by city and channel, so design and insulation tech can win fast or face rapid crowding; use collabs and seasonal drops to probe demand, scale winners and cull laggards quickly.
Weekly portioning is a rising habit in India, but the meal‑prep systems category remains nascent; Borosil can stitch curated sets plus recipe/content tie‑ins to claim first‑mover advantages and drive trial through test bundles, subscriptions, and retailer exclusives.
Invest only if pilot retention and attach rates—measured over 3–6 months—justify shelf allocation and unit economics; prioritize flexible SKUs and low CAC subscription trials to prove LTV before scaling.
Question Marks: target high-growth adjacencies (scientific instruments CAGR ~6.2% to 2028) but low share—choose build, partner, or acquire with 12–18 month traction tests.
Solar exports: global PV additions ~440 GW in 2024 (IEA); convert to Star only with IEC/UL, multi‑year offtakes and margin resilience.
Pilot smart lids (1k–3k), premium drinkware drops and meal‑prep bundles; scale on repeat >20% and 3–6m retention.
| Segment | 2024 signal | KPI trigger |
|---|---|---|
| Solar exports | 440 GW additions | IEC/UL, offtake, margin hold |
| Smart‑lid | Pilot 1k–3k | Repeat >20%, review ≥4.0 |
| Meal‑prep | Nascent | 3–6m retention, LTV/CAC |


