
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
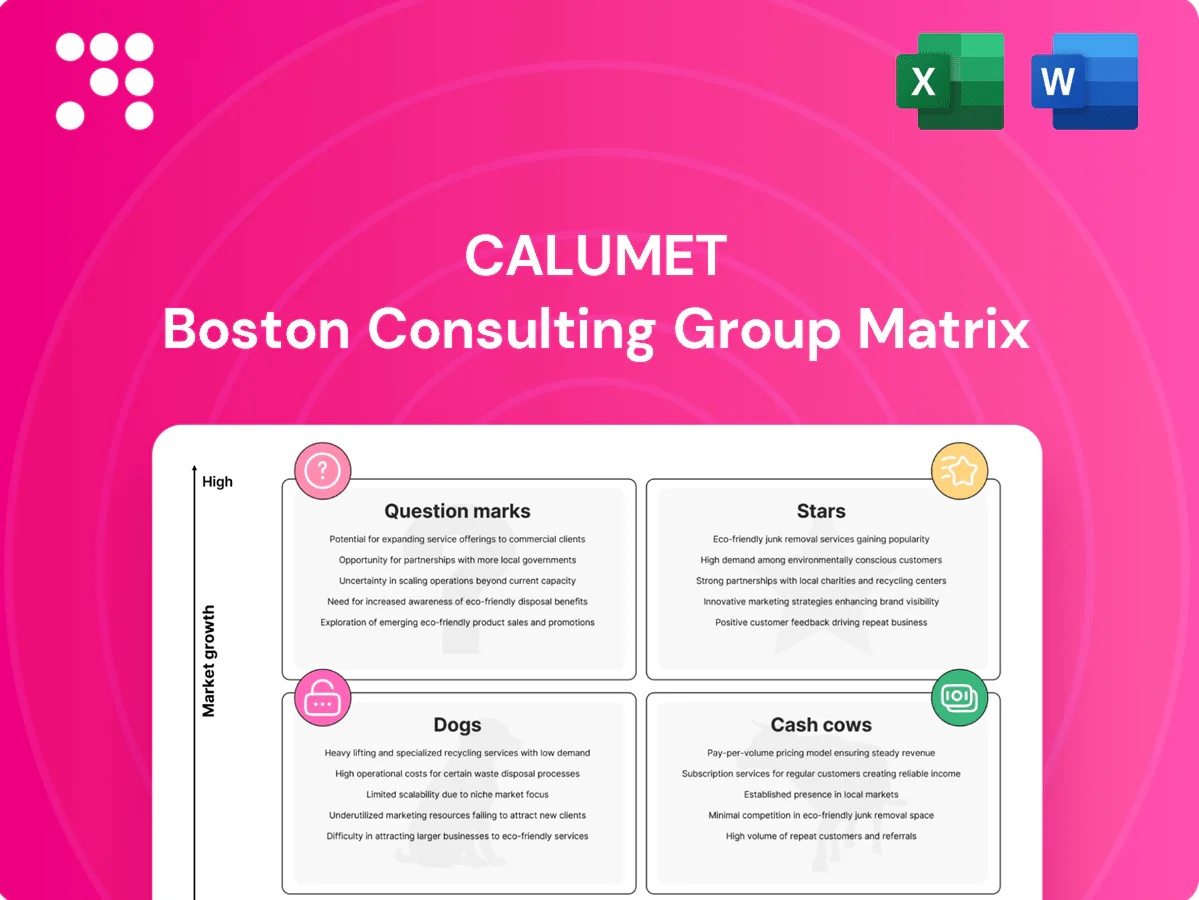
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Think of the Calumet BCG Matrix as a quick pulse-check on which products are winning, which fund the business, and which are costing you time and cash — but this is just the teaser. Buy the full BCG Matrix for a quadrant-by-quadrant breakdown, data-driven recommendations, and actionable moves you can implement now. You’ll get a polished Word report plus an editable Excel summary—skip the guesswork and make sharper, faster strategic calls.
Custom specialty lubricants hold high share in niche industrial segments while the global industrial lubricants market reached about $43 billion in 2024 as equipment specs tighten. These performance-leading blends win repeat contracts and support premium pricing, often 15-30% above commodity grades. Sustained technical marketing and application support remain essential; continued investment in labs and sales engineers is required to retain leadership and scale.
High‑purity solvents demand is rising with stricter purity specs in coatings, adhesives and select tech processes; qualification cycles in 2024 commonly run 6–18 months and consume multimillion‑dollar budgets. Calumet’s tailored specs and consistent supply chain reliability put it near the front of the pack. Heavy technical service spend weighs on cash flow but is strategic; stay invested to cement the lead.
Tailored waxes for packaging, pharma and niche consumer uses are Stars for Calumet as these end-markets grew mid-single digits in 2024 (industry estimates ~5% CAGR), where customization wins share; durable formulations plus reliable supply create meaningful switching costs. Close promotion with converters and brand owners remains critical to penetrate returnable contracts and specs. Aggressively defend share now to mature into a cash cow as markets stabilize.
Premium base oils and specialty fractions are Stars for Calumet, driven by rising demand in high-spec lubricants; the global lubricants market reached about $40 billion in 2024, with premium segments outpacing bulk volumes. Quality consistency and logistics reliability give Calumet pricing leverage and customer stickiness. These streams require steady capex and close customer development to defend margins, so keep investing to widen the moat.
Selective jet and aviation-grade segments with tighter specifications are rebounding, and Calumet’s proven ability to meet narrow specs at scale is winning share in aftermarket and OEM channels; certification and relationship selling require sustained capital and commercial effort. Focus resources where premium margins and durable growth overlap to maximize return on certification spend.
Calumet Stars: custom lubricants, high‑purity solvents, tailored waxes and premium base oils drive above‑market growth (market ~$43B in 2024); premium pricing +15–30% and mid‑single‑digit CAGR in niches; sustain lab/capex and technical sales to convert growth into durable margins and cash flow.
| Segment | 2024 Market | Premium |
|---|---|---|
| Custom lubricants | $43B | 15–30% |
 Detailed Word Document
Concise Calumet BCG Matrix overview: quadrant insights, investment priorities, and risks for each unit.

 Customizable Excel Spreadsheet
One-page Calumet BCG Matrix that flags underperformers and growth bets, ready to export for exec decks.
Conventional gasoline streams sit in a mature market with stable demand—US gasoline consumption averaged about 8.9 million barrels per day in 2023 (EIA), and Calumet holds a high share where it operates due to entrenched distribution. Margins are decent when units run efficiently, making operational excellence the primary lever rather than promotion spend. Low marketing intensity keeps cash conversion high. These streams are the milk that funds specialty growth.
ULSD and standard diesel blends are cash cows for Calumet: US distillate demand averaged 3.6 million b/d in 2024 (EIA), driven by steady freight and industrial use, not spikes. High channel share and predictable off‑take prioritize yield, reliability and cost; marketing spend is minimal. Surplus cash funds R&D and covers operating bills.
Legacy industrial lube lines are well-known SKUs with loyal accounts in mature segments, delivering steady volumes and low service costs for Calumet in 2024. Incremental debottlenecking has historically boosted margins materially, supporting cash generation without heavy capex. Maintain quality, avoid price wars, and harvest cash to fund higher-return projects.
Core solvent portfolio (commodity grades) delivers dependable cash: established specs and repeat buyers drive stable volumes, efficient runs and tight inventory produced steady margins in 2024 while market growth remained flat (≈0–1%), and Calumet retained strong share in key North American channels.
Bulk wax contracts are long-term take-or-pay relationships serving mature uses with low churn (under 3% in 2024), predictable planning and SG&A around 5% of revenue; minor process improvements in 2024 drove EBITDA uplifts of roughly 250–350 basis points. Continue to milk volumes while rigorously guarding service levels and fulfillment performance.
Conventional gasoline, ULSD/diesel and legacy lubes generate steady cash for Calumet via high channel share, low promo spend and efficient runs; US gasoline ~8.9 mbd (2023) and distillates ~3.6 mbd (2024). Commodity solvents and bulk wax add predictable cash with low churn and ~5% SG&A; incremental tweaks lifted EBITDA 250–350 bps in 2024.
| Product | 2024 vol / metric | Market growth | EBITDA uplift | Churn |
|---|---|---|---|---|
| Gasoline | US 8.9 mbd (2023) | mature | — | <3% |
| Distillates | 3.6 mbd (2024) | stable | — | <3% |
| Lubricants/solvents/wax | stable SKUs | 0–1% | 250–350 bps | <3% |
The Calumet BCG Matrix file you’re previewing here is the exact document you’ll receive after purchase — no watermarks, no placeholders, just the finished report. Built for clarity and strategic use, it arrives formatted and ready to edit, print, or present. Once bought, you’ll get immediate access and can start using it with your team or clients right away.
Low‑margin spot fuel sales are highly competitive with little pricing power and no growth tailwind; industry spot margins in 2024 frequently fell below $0.05 per gallon, compressing returns. Cash and working capital remain tied up for thin or zero returns, and turnarounds rarely justify the effort given typical payback horizons exceeding 24 months. Prune exposure and redeploy capacity to higher‑margin segments to improve ROIC.
Tiny runs, high changeover, and complex scheduling materially erode margin on Calumet's fragmented micro-volume SKUs. Market share is low and shrinking in these niches; industry studies in 2024 show tail SKUs often represent 20–30% of total SKUs but contribute under 5% of sales, creating a disproportionate cash drag. Rationalize the tail to reclaim capacity and margin.
Undifferentiated commodity blends in Calumet’s BCG matrix have no clear technical edge and are treated by buyers as interchangeable, leading to low growth and low market share with persistent price pressure. Marketing cannot overcome this structural cost disadvantage. Strategic options are exit or assimilate volumes into higher-value, branded or specialty product lines to protect margins.
Dogs: Distant geographies with heavy logistics — Freight volatility and long haul transport erode service reliability and can consume double-digit percentage points of product margin according to 2024 industry analyses; Calumet lacks local scale or share to offset these costs, and capital-intensive fixes historically show poor ROI, making selective divestiture or targeted partnerships the preferred response.
End markets are moving on and volumes are slipping for Calumet legacy specs, leaving refinery throughput and inventory tied up with diminishing returns; turnaround plans continue to consume cash while showing minimal upside.
With demand secularly declining and maintenance cycles extending costs, sunset these assets quickly to free capacity and redeploy capital into higher-growth specialty segments.
Low‑margin spot fuel sales (<$0.05/gal typical in 2024) and tiny tail SKUs (20–30% of SKUs, <5% of sales) tie up cash and working capital; turnarounds show paybacks >24 months. Freight volatility can shave double‑digit points off margins and remote assets lack scale; divest or partner to redeploy capital into higher‑margin specialty lines.
| Metric | 2024 | Implication |
|---|---|---|
| Spot margin | <$0.05/gal | Low ROI |
| Tail SKUs | 20–30% SKUs; <5% sales | Rationalize |
| Turnaround payback | >24 months | Sunset assets |
Next‑gen specialty lubes face high growth as OEM specs tighten, with the segment forecast at roughly 6% CAGR from 2024 as EV and advanced powertrains drive demand, while Calumet’s share remains single‑digit. Qualification cycles typically run 12–24 months and cost several hundred thousand to low‑millions of dollars. If key OEM wins land, products convert to Stars quickly. Invest behind targeted OEM approvals—or exit fast to avoid sunk cost.
Segment shows strong growth while incumbents hold most share; entry demands rigorous validation and application support to win OEM confidence. Early pilots are promising but capital‑intensive, requiring sustained R&D and working capital. Invest aggressively where Calumet can demonstrate clear formulation differentiation and margin upside; discontinue pilots lacking fast scalability or technical defensibility.
Packaging reformulations are accelerating—sustainable packaging demand rose ~7% y/y in 2024 and regulatory pressure is increasing—Calumet is still early, with customer trials often taking 6–12 months and tying up ~5–8% of working capital. If adoption by 3–5 anchor customers scales, gross margins above ~20% should justify capex and commercialization.
Travel recovered to roughly 90–95% of 2019 levels in 2024, supporting niche business and private aviation growth, but access remains restricted; market share outside Calumet’s current lanes is still under single digits. Certifications and long-term supply guarantees require upfront CAPEX and working capital running into millions per hub, so invest selectively around high-utilization hubs with strong daily flight counts and load factors.
Retail and industrial partners offer material growth pathways for private‑label and co‑brand specialty lines, but Calumet’s current placement remains single‑digit share in partner assortments, needing packaging, branding, and dedicated service capabilities to win placements.
Private‑label can unlock scale with lower promotional spend versus national brands when assortments are optimized; recommend test, learn, and scale approach—pilot SKUs, measure velocity, then expand winners.
Next-gen lubes ~6%; packaging +7% y/y; travel 90-95%
Next‑gen specialty lubes ~6% CAGR from 2024; Calumet share single‑digit, OEM qual 12–24 months, cost $0.2–3M; win → Star conversion fast. Sustainable packaging demand +7% y/y (2024); trials 6–12 months, WC 5–8% sales. Travel recovery 90–95% of 2019 (2024); hub CAPEX/millions—invest where utilization >70%.
| Metric | 2024 |
|---|---|
| Specialty lubes CAGR | ~6% |
| Packaging demand | +7% y/y |
| Travel vs 2019 | 90–95% |
| OEM qual cost/time | $0.2–3M / 12–24m |


