
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
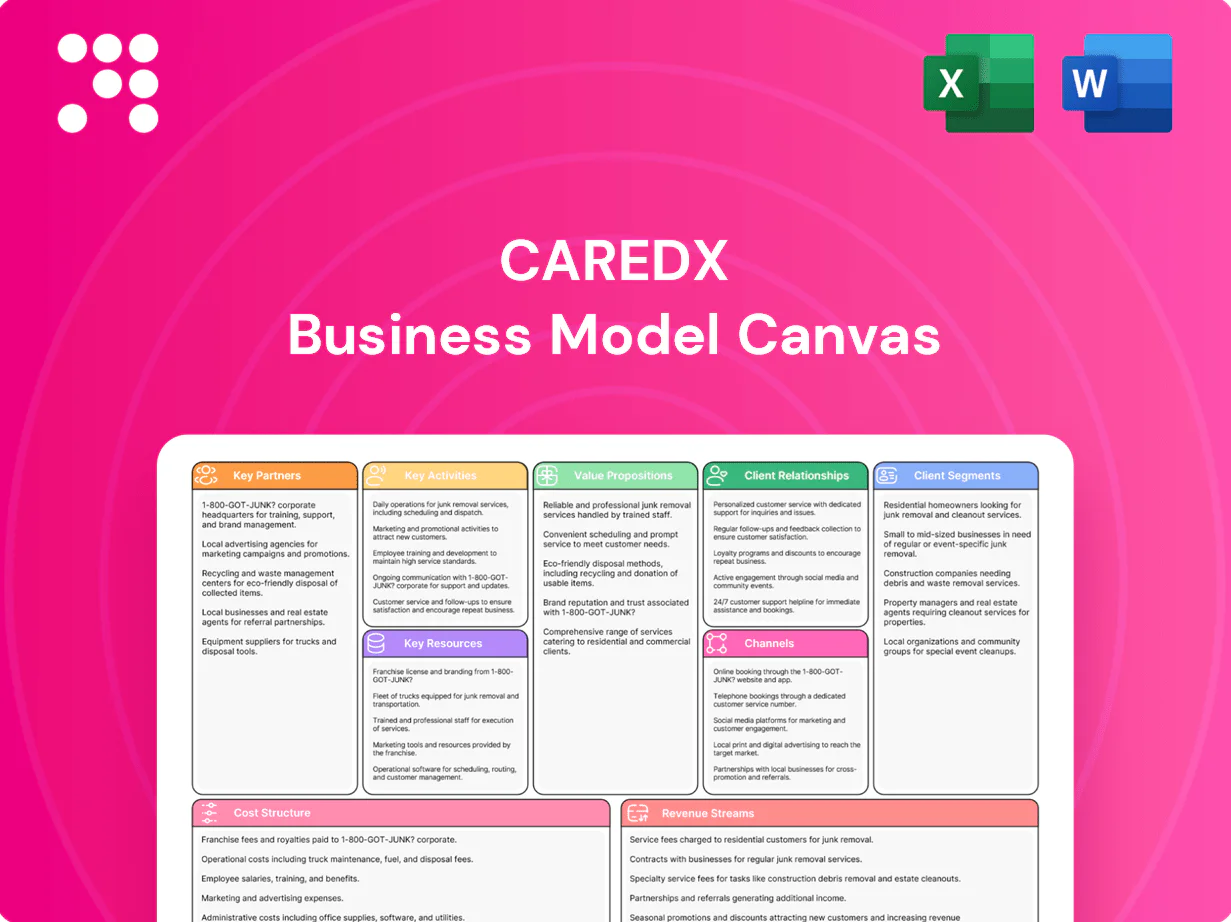
Unlock the full strategic blueprint behind CareDx with our Business Model Canvas—revealing customer segments, value propositions, key partners, and revenue levers in a concise, actionable format; perfect for investors, consultants, and entrepreneurs ready to benchmark, model growth, and download ready-to-use Word and Excel files for immediate strategy work.
Transplant centers and hospital systems—about 250 centers in the U.S.—are the primary clinical settings where diagnostics are ordered and acted upon. Deep partnerships enable test adoption, workflow integration, and clinician training across centers performing roughly 42,000 U.S. transplants annually (2024 OPTN). Joint quality-improvement initiatives quantify clinical and economic value. Multi-site collaborations drive real-world evidence generation.
Leading transplant researchers co-develop and validate assays with CareDx, publish results and shape clinical protocols; investigator-initiated studies have expanded real-world evidence across centers. KOL advocacy has accelerated guideline consideration and payer discussions for noninvasive monitoring. Advisory boards of clinicians guide pipeline priorities and study design, aligning products to the ~24,000 US kidney transplants performed annually.
Coverage and reimbursement hinge on payers and PBMs, where CareDx leveraged payer partnerships to support medical policies and prior authorization alignment; in 2024 the company reported annual revenue exceeding $500 million, underscoring commercial traction. Joint health-economic studies demonstrated meaningful cost offsets versus biopsy-driven care, with published analyses reporting biopsy reductions and net savings per patient in the thousands of dollars. Contracting focuses on consistent coding and prior auth criteria, while ongoing claims and outcome data exchange sustain value-based arrangements and shared-savings models.
Partnerships with organ procurement organizations and registries give CareDx access to donor-recipient data and outcomes, improving risk stratification and algorithm performance; registries’ longitudinal datasets enable external validation and recalibration. These alliances support early post-transplant monitoring pathways and shared initiatives that standardize data capture and reporting, enhancing interoperability and clinical utility.
Interfacing with EMR/LIS streamlines ordering, results delivery and documentation, leveraging >96% EMR adoption among US hospitals to reduce manual entry. Integration cuts clinician friction and errors, shortening decision loops. Logistics partners ensure reliable sample collection and cold-chain transport; the global cold-chain logistics market was about $20B in 2024, underpinning turn-around-time and scale.
CareDx partners with ~250 US transplant centers driving adoption across ~42,000 annual transplants, supports payer/PBM coverage tied to >$500M 2024 revenue, and co-develops evidence with registries/OPOs for AI recalibration. EMR/LIS integrations (>96% US hospitals) and cold-chain logistics (~$20B market 2024) secure TAT and scale.
| Partner | Role | 2024 metric |
|---|---|---|
| Transplant centers | Clinical adoption, trials | ~250 centers / 42,000 tx |
| Payers/PBMs | Coverage, value agreements | Supports >$500M revenue |
| Registries/OPOs | Data/validation | Longitudinal cohorts |
| EMR/Logistics | Integration, transport | >96% EMR, $20B cold-chain |
 Detailed Word Document
A concise, pre-built Business Model Canvas for CareDx detailing customer segments, channels, key activities and value propositions aligned with its transplant diagnostics and monitoring strategy. Ideal for investor decks, strategic planning, and SWOT-linked competitive analysis.

 Customizable Excel Spreadsheet
High-level view of CareDx's business model with editable cells to quickly surface how transplant diagnostics, monitoring services, and recurring revenue alleviate operational and clinical decision-making pain points.
Continuous R&D in cfDNA, gene expression, and NGS expands CareDx assay utility across organs, while analytical optimization steadily improves sensitivity, specificity and assay robustness. Pipeline efforts prioritize new indications and adjunct biomarkers to broaden clinical value. Prototyping and feasibility studies de-risk trials and accelerate regulatory pathways.
Prospective and retrospective studies in transplant cohorts (totaling >5,000 patients) have established AlloSure performance and clinical utility, with negative predictive value above 98% for ruling out rejection. Peer-reviewed publications and conference presentations (dozens through 2024) drive clinical awareness and payer credibility. Health-economic models demonstrate notable cost savings versus routine surveillance biopsy, and post-market surveillance continuously refines cutoffs and use-cases.
High-throughput CLIA/CAP lab operations deliver accurate, timely results, supporting scale seen across CAP’s network of more than 8,000 accredited laboratories and CLIA’s roughly 260,000 certified facilities. Rigid SOPs, proficiency testing and QA/QC uphold accreditation and traceability. Capacity planning absorbs demand surges and new launches without compromising TAT. Continuous improvement initiatives lower COGS and shorten turn-around-time.
Regulatory, coding, and reimbursement management drives CareDx market access: sustained 2024 engagement with regulators to clarify assay pathways, targeted coding strategy and payer dossiers to secure payment, continuous medical policy monitoring to adjust access tactics, and rigorous compliance to reduce audit and legal exposure.
Specialized sales and MSL teams drive adoption across 250+ US transplant centers, supporting uptake of CareDx assays. Training programs cover ordering, result interpretation, and care pathways; digital case-review and longitudinal tracking tools integrate with workflows. KOL programs and conferences expand reach amid ≈41,000 US transplants annually (2023–24).
Continuous R&D in cfDNA/NGS expands indications; >5,000-patient studies and dozens of 2024 publications support AlloSure with NPV >98%.
High-throughput CLIA/CAP ops (CAP network 8,000 labs; CLIA ~260,000) maintain TAT and lower COGS; capacity covers 250+ transplant centers.
2024 regulatory/coding efforts produced payer dossiers and active policy monitoring to secure access across ≈41,000 US transplants annually.
| Metric | 2024 Value |
|---|---|
| Study pts | >5,000 |
| AlloSure NPV | >98% |
| Centers covered | 250+ |
| US transplants/yr | ≈41,000 |
The document you're previewing is the exact CareDx Business Model Canvas you'll receive after purchase; it's not a mockup or teaser. When you buy, you'll download this same fully editable file, formatted and organized as shown, ready for presentation or analysis. No surprises—what you see is the complete deliverable.
Core cfDNA, gene-expression and NGS technologies form a durable competitive moat, supported by multi-year clinical datasets (typically 3–5 years) that underpin validated cutoffs and algorithms which are hard to replicate.
Patents, trade secrets and proprietary know-how lock in differentiation and limit generic entrants, while validated diagnostic thresholds require extensive clinical validation to reproduce.
Brand equity is directly tied to assay performance and clinical adoption, driving payer trust and referral patterns that amplify commercial defensibility.
CLIA/CAP-certified laboratories enable nationwide testing across all 50 states, supporting scalable transplant diagnostics. High-throughput automation and advanced instrumentation drive quality and throughput, processing tens of thousands of assays monthly. A geographically distributed footprint ensures logistics efficiency and redundancy, while CLIA/CAP accreditation underpins payer and provider trust and reimbursement acceptance.
As of 2024, bioinformatics pipelines convert raw sequencing into actionable clinical reports within 24–48 hours for transplant monitoring, enabling timely interventions. Machine learning models continuously refine sensitivity and specificity as the dataset grows, improving predictive performance over time. Secure, HIPAA- and SOC 2–aligned infrastructure enforces data governance and encryption. Interoperability enables bidirectional EMR and LIS integrations with major vendors to streamline clinical workflows.
Peer-reviewed studies and registry analyses demonstrate clinical utility of CareDx assays in detecting allograft injury and guiding management; longitudinal patient cohorts support development of validated risk models and predictive algorithms. Health-economic models published to 2024 show cost-effectiveness signals that aid payer discussions, and the cumulative evidence underpins consideration in clinical guidelines.
Established accounts at over 300 transplant centers in 2024 drive recurring biopsy and surveillance volume; payer contracts and positive coverage decisions underpin billable reimbursement and cash flow. KOL networks accelerate clinician education and advocacy, shortening adoption cycles. Dedicated customer success teams sustain retention and expand account-level utilization.
Core cfDNA/NGS tech, patents and 3–5 year clinical datasets create a durable competitive moat.
CLIA/CAP labs and automation process ~30,000 assays/month (2024) with 24–48h reporting.
Peer-reviewed evidence, >300 transplant centers (2024) and payer contracts drive adoption and reimbursement.
| Metric | 2024 |
|---|---|
| Assays/month | ~30,000 |
| Transplant centers | >300 |
Blood-based AlloSure cfDNA testing cuts the need for invasive biopsies by enabling rule-out of rejection with negative predictive value >95%, lowering procedural risk and improving patient comfort. Clinicians gain frequent, actionable surveillance data to guide immunosuppression. Health systems report higher protocol adherence, supporting earlier interventions and potential cost avoidance through reduced biopsy-related complications.
Sensitive biomarkers detect allograft injury before clinical deterioration, enabling interventions days to weeks earlier that can preserve graft function. Real-time alerts support timely immunosuppressive medication adjustments and reduce progression to severe rejection. Improved graft survival and fewer hospitalizations align with payer value through lower downstream costs and better long-term outcomes.
Clear scores, thresholds, and trend graphs present actionable insights that speed clinical decision-making and reduce interpretation time. Integrated comments link each result to recommended next steps, supporting consistent care pathways. Longitudinal views contextualize patient trajectories over months to years, aiding prognosis. EMR-ready formats export seamlessly into clinical workflows.
Lower total cost of care: CareDx noninvasive surveillance has been associated with up to 50% fewer biopsies and reduced hospital readmissions, optimizing immunosuppression to avoid over- and under-treatment; 2024 health-economic analyses report per-patient savings exceeding $10,000 and improved payer coverage, enabling providers to meet value-based care targets.
CareDx delivers an end-to-end transplant care pathway covering pre- and post-transplant across organs, with coordination tools that streamline multidisciplinary team communication, education and service programs that boost medication adherence, and population-level data feeds for oversight; over 100,000 people were on the US transplant waitlist in 2024, underscoring scale.
AlloSure cfDNA provides NPV >95% to rule out rejection, reducing invasive biopsies and patient risk. Enables earlier detection days–weeks sooner to preserve grafts, supporting up to 50% fewer biopsies and better adherence. Health-econ analyses (2024) report >$10,000 per-patient savings and broad payer uptake.
| Metric | Value | Year |
|---|---|---|
| NPV | >95% | 2024 |
| Biopsy reduction | Up to 50% | 2024 |
| Per-patient savings | >$10,000 | 2024 |
| US transplant waitlist | >100,000 | 2024 |
Account teams coordinate onboarding, training, and quarterly performance reviews to optimize ordering pathways and metrics. Regular business reviews align on outcomes targets across centers supporting over 40,000 transplants annually in the US. Clear escalation paths resolve issues quickly, reducing downtime and protecting revenue and patient continuity.
Clinical experts and MSLs at CareDx assist clinicians with case interpretation and best practices, supporting over 1,400 transplant centers in 2024 and helping integrate diagnostics into care pathways. Journal-club and CME-style sessions (regular regional programs) build clinician proficiency and adoption. Dedicated on-call support covers urgent post-transplant scenarios 24/7. Continuous feedback loops from clinicians drive product and workflow updates.
Sites participate in multicenter studies and registries, with CareDx engaging over 1,500 transplant centers globally to drive evidence generation. Joint publications from these collaborations elevate institutional profiles and have produced peer-reviewed outputs cited across transplant guidelines. Data-sharing agreements underpin quality-improvement initiatives and benchmarking, while custom analyses answer center-specific clinical and operational questions to support outcome improvement.
Navigation teams assist benefits verification and connect patients to financial aid programs, supporting access to CareDx services and reducing cost barriers; reminder systems have been shown in published studies to reduce missed blood-draws by up to 25%, improving sample capture for AlloSure and other assays.
Targeted educational materials increase adherence to recommended testing schedules; multilingual support expands reach to non-English speakers, aligning with industry moves to improve equity in transplant monitoring.
Digital portals consolidate orders, TAT, and results into a single interface used by 1,400+ transplant centers, enabling faster decisioning and centralized recordkeeping. Trend analytics provide cohort-level oversight for outcome tracking and resource allocation. Secure messaging streamlines multidisciplinary care coordination while immutable audit trails support HIPAA and 21 CFR Part 11 compliance.
Account teams, MSLs and 24/7 escalation support onboard and optimize workflows across 1,400+ transplant centers, supporting 40,000+ US transplants/year. Navigation and benefits verification plus reminders cut missed draws up to 25%, improving assay capture. Registries and portals enable cohort analytics and regulatory-compliant audit trails.
| Metric | Value |
|---|---|
| Transplant centers | 1,400+ |
| Transplants/year (US) | 40,000+ |
| Missed draw reduction | up to 25% |
| Registry sites | 1,500+ |
Field teams target transplant centers and affiliated clinics, focusing on relationship selling that aligns with clinical priorities and workflow. Onsite demos and pilots prove value, driving conversion after trials. Contracting typically follows successful pilots; CareDx reported 2024 revenue exceeding $600 million, reinforcing commercial traction.
Presence at transplant and nephrology/cardiology meetings (major meetings draw roughly 5,000–15,000 attendees) raises brand awareness; peer-reviewed abstracts and symposiums showcase clinical evidence and guideline-impacting data from 2024 programs; KOL forums enable peer-to-peer education and adoption; booth interactions at these events typically convert into qualified leads, often in the single-digit to low-double-digit percent range.
Embedded order sets reduce friction and errors by standardizing transplant testing workflows; as of 2024 CareDx supports integrations with major EHRs including Epic and Cerner, enabling results to flow automatically into the patient chart. Clinical decision support prompts appropriate use at the point of order, while tight IT integration increases customer stickiness and recurring revenue through seamless care-team workflows.
Alliances expand CareDx reach into markets where the company lacks direct commercial presence, letting local distributors access transplant centers and payers. Local partners navigate country-specific regulations and reimbursement pathways to accelerate coverage and ordering. Technology transfer and on-site training maintain assay quality and lab performance. Joint marketing campaigns with partners speed clinician adoption and sample referral volumes.
Field teams and pilots convert transplant centers; CareDx reported 2024 revenue >$600 million and served >1,700 transplant centers. Conferences (5,000–15,000 attendees) and KOL forums drive awareness; event-to-lead conversion typically single- to low-double-digit percent. EHR/API integrations (Epic, Cerner) and portals enable ordering/alerts and increase stickiness; alliances expand access and manage reimbursement.
| Channel | 2024 metric | Impact |
|---|---|---|
| Field teams/pilots | Conversion: single- to low-double-digit % | Direct revenue & contracts |
| Conferences/KOLs | 5,000–15,000 attendees | Awareness & leads |
| Digital/EHR/API | Integrations: Epic, Cerner; >1,700 centers | Workflow stickiness |
| Alliances | Local market access | Regulatory/reimbursement support |
Transplant centers and surgeons are the primary users overseeing post-transplant management, driving high testing volumes given over 40,000 organ transplants performed annually in the US (OPTN 2023). Institutional protocols and surveillance schedules heavily influence test demand. Clinicians require reliable, rapid results—typically within 24–48 hours—to guide immunosuppression adjustments. They place high value on clinical-grade data that supports actionable decisions.
Nephrologists and cardiologists manage ~26,000 kidney and ~3,000 heart transplants annually in the US (2023–24) and follow recipients longitudinally to prevent graft loss. They use repeatable, noninvasive monitoring to titrate immunosuppression and reduce rejection risk, aiming to improve ~5‑year graft survival rates. They require clear, actionable reports that integrate biomarker trends and threshold-based alerts for prompt clinical decisions.
Integrated delivery networks and hospitals prioritize outcomes, cost control and standardized care pathways to improve value-based metrics and reduce readmissions. IDNs account for roughly 60% of US hospital beds (2024) and manage programs like transplant centers that perform ~25,000 kidney transplants annually (2024). They drive formulary-like decisions for diagnostics, demand EMR integration and actionable reporting, and evaluate vendors on documented quality and economic impact.
Payers and health plans assess CareDx offerings on clinical and economic evidence, prioritizing tests that demonstrably lower costly complications; solid-organ transplant 30‑day readmission rates hover around 30% and drive high downstream costs. In 2024 Medicare Advantage covered about 52% of beneficiaries (≈30.7M), increasing payer focus on utilization management and value-based arrangements.
Transplant patients and caregivers benefit from fewer invasive biopsies and improved molecular monitoring; over 40,000 organ transplants occur annually in the U.S. (OPTN/UNOS, 2024). They require education, automated reminders, and financial support to access testing, since nonadherence affects roughly 20% of recipients and undermines test effectiveness. Patient and caregiver experience strongly influences provider adoption of surveillance programs.
Primary users are transplant centers/surgeons driving volume amid ~40,000 US transplants annually (OPTN/UNOS 2024). Nephrologists/cardiologists manage ~26,000 kidney and ~3,000 heart transplants (2023–24) needing repeatable noninvasive monitoring. IDNs (≈60% US beds, 2024) and payers (Medicare Advantage 52% enrollment, 2024) focus on outcomes/value to reduce ~30% 30‑day readmissions; patients face ~20% nonadherence.
| Segment | Key metric (2023–24/2024) |
|---|---|
| Transplant centers | ≈40,000 transplants/yr |
| Kidney/Heart clinicians | ≈26,000 kidney; ≈3,000 heart |
| IDNs | ≈60% hospital beds |
| Payers | MA 52% enrollment; 30% readmissions |
| Patients | ≈20% nonadherence |
R&D and clinical studies drive significant spend for CareDx, with annual development and validation costs exceeding $50 million. Multi-center trials, data analysis, and peer-reviewed publications are core ongoing expenses. Regulatory submissions to FDA, EMA and other agencies add substantial fees and consultancy costs. Continuous pipeline maintenance and lifecycle studies sustain recurring investment.
Reagents, consumables, and instruments typically account for roughly 40% of variable lab COGS in 2024; staffing, QA/QC, and maintenance contribute ~25–35% as fixed costs. Logistics and sample handling add another 10–15% and are critical to turnaround and chain-of-custody. Investments in automation in 2024 reduced per-sample costs by an estimated 15–25%, improving gross margins and scalability.
Accreditation, audits, and documentation demand dedicated staff, lab time, and external fees to maintain CAP/CLIA standards and ongoing third-party inspections. Privacy and security programs protect patient data—an average data breach cost was $4.45 million in 2024 (IBM). Legal and coding compliance reduce exposure to penalties (HIPAA civil monetary maximums can reach $1.5 million per violation category annually). Regular training keeps staff current and sustains operational standards.
Field teams, conferences, and education programs represent a sizable portion of CareDx s 2024 commercial spend, supporting market penetration and transplant center engagement; CareDx reported 2024 revenue of about $1.04 billion, underscoring investment scale.
MSL activities translate clinical evidence into practice, bolstering adoption of diagnostics and therapies across transplant centers.
Content and digital platforms extend reach efficiently while account management programs sustain customer retention and recurring testing volumes.
IT, data infrastructure, and integrations drive CareDx cost structure: cloud compute and storage for bioinformatics (cloud spend rising ~20% in 2024) plus analytics tooling to deliver actionable insights; EMR/LIS integrations require ongoing development and support; cybersecurity and availability targets of 99.99% and ~11% of IT budgets in 2024 are critical.
R&D/clinical trials >$50M annually; 2024 revenue ~$1.04B and automation cut per-sample COGS 15–25%. Reagents/consumables ~40% of variable COGS; staffing/QA 25–35%; logistics 10–15%. IT/cloud spend up ~20% in 2024; cybersecurity ~11% of IT; avg data breach cost $4.45M (2024).
| Cost Category | 2024 Metric |
|---|---|
| R&D/Trials | >$50M |
| Revenue | $1.04B |
| Reagents/COGS | ~40% |
| Staffing/QA | 25–35% |
| Logistics | 10–15% |
| Cloud/IT growth | ~+20% |
| Cybersecurity spend | ~11% of IT |
| Data breach cost | $4.45M |
Per-test diagnostic revenues are CareDx core income, driven by ordered assays at transplant centers and representing roughly 70% of 2024 revenue, with test volumes exceeding 200,000 in 2024. Tests are reimbursed via CPT and PLA codes where covered, with reimbursement rates varying by payer and setting. Revenue mix shifts by organ type and payer contract, and volumes scale directly with clinical protocol adoption and center uptake.
Bundled longitudinal testing and analytics sell as subscription and monitoring programs, packaging cohort-level AlloSure/AlloMap-style assays with continuous data insights. These contracts deliver predictable, recurring revenue for providers and health systems and reduce episodic billing volatility. Tiered pricing by volume or feature set enables scale-based margins and customer segmentation. Ongoing monitoring increases clinical stickiness through continuous engagement and care-path integration.
Pharma and clinical trial services include companion diagnostics, centralized sample testing, and RWE projects supporting drug development in transplant and immunology, with custom analytics and reporting to demonstrate endpoints and biomarker utility. Contracts often structure as milestone-based payments tied to assay development, validation, and regulatory delivery. These services drive partner retention and higher-margin recurring revenue.
Licensing dashboards, APIs, and proprietary algorithms provides CareDx recurring, high-margin revenue by converting analytics into subscription and royalty streams.
EMR-integrated decision support sold as an add-on increases stickiness and allows premium pricing for workflow-embedded insights.
White-labeled solutions for transplant centers and partners expand distribution while preserving licensing royalties and margin.
CareDx generates significant ex-US revenue via partners and local labs, combining test-services and kit sales to serve transplant markets outside the US; in 2024 total revenue was about $832 million with roughly 18% from international channels, reflecting partner-led growth.
Pricing is adapted to local reimbursement environments and co-marketing with distributors expands clinical penetration and lab adoption across Europe and APAC, driving recurring service volume and kit purchases.
Per-test diagnostics drive ~70% of 2024 revenue ($832M) with >200,000 tests; reimbursement varies by CPT/PLA and payer. Subscription monitoring, pharma services and licensing add recurring, higher-margin revenue; pharma contracts often milestone-based. International sales ~18% via partners; pricing aligned to local reimbursement and kit/service mix.
| Metric | 2024 |
|---|---|
| Total revenue | $832M |
| Per-test share | ~70% |
| Test volume | >200,000 |
| International | ~18% |


