
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
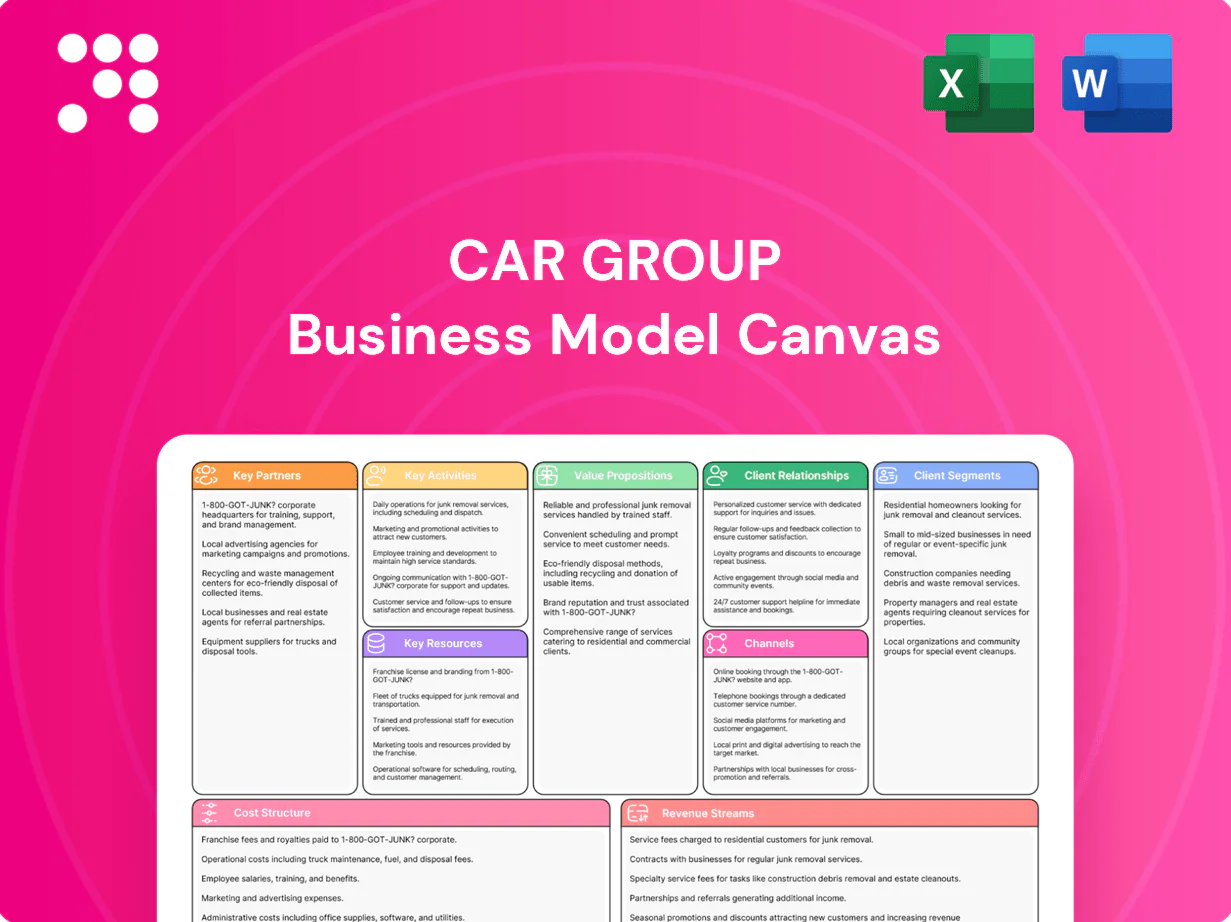
Unlock the full strategic blueprint behind CAR Group's Business Model Canvas — a concise, actionable map of value propositions, customer segments, key partners, and revenue streams. Perfect for investors, consultants, and founders who want a ready-to-use, downloadable template to benchmark strategy and drive growth. Purchase the complete Canvas to access detailed, editable Word and Excel files for immediate analysis and planning.
Franchise and independent dealers supply inventory depth to CAR Group and pay subscription and per-listing fees for visibility and tools; in 2024 these commercial arrangements remained a primary revenue stream. Partnerships ensure fresh listings, accurate VIN-level data, and rapid lead response. Co-marketing programs in 2024 boosted showroom footfall and conversions, while dealer feedback loops continuously improve pricing and merchandising.
OEM alliances in 2024 coordinate brand campaigns, certified pre-owned programs and launch promotions to amplify reach and conversion. Access to new-vehicle telematics and spec feeds enriches CAR Group configurators and research tools, improving shopper accuracy. Shared analytics drive allocation and retail strategies across markets, and preferred OEM status secures recurring co-op and ad spend from manufacturers.
Banks, lenders and insurers plug into CAR Group lead-gen and pre-qualification flows, tapping a US auto loan market near 1.7 trillion USD in 2024. Embedded offers raise conversion and ARPU by about 20–35%, while secure data sharing tightens risk assessment and can lift approval rates roughly 10–15%. Revenue sharing—commonly 10–30% on referrals—aligns incentives across the funnel.
Data partners in 2024 boosted valuation accuracy by ~15%, enriching specs and history reports; media agencies amplified reach with programmatic spend driving ~12% lift in campaign performance. API integrations enable real-time syndication and dealer DMS connectivity, while joint analytics improved attribution and demonstrated ROI uplifts near 18% in pilot cohorts.
Franchise dealers, OEMs, lenders, logistics, inspection and data partners in 2024 drove inventory supply, co-op advertising, embedded finance and faster delivery, boosting conversion and ARPU. Key metrics: US auto loan market ~1.7T USD; ARPU +20–35%; approval +10–15%; inspection reports −15% returns; conversion +12%; valuation +15%; media +12%; pilot ROI ~18%.
| Partner | Metric (2024) |
|---|---|
| Dealers | Revenue streams: subscription/listing |
| OEMs | Co-op/ad spend recurring |
| Lenders | Market ~1.7T USD; ARPU +20–35% |
| Inspections | −15% returns; +12% conv. |
| Data/Media | Valuation +15%; media +12%; ROI ~18% |
 Detailed Word Document
A comprehensive, pre-written Business Model Canvas tailored to CAR Group’s strategy, organized into the 9 classic BMC blocks with full narrative on customer segments, channels, value propositions, revenue streams and key resources. Includes competitive-advantage analysis, linked SWOT, and polished presentation-ready insights to support investor discussions, funding validation, and strategic decision-making.

 Customizable Excel Spreadsheet
High-level view of CAR Group’s business model with editable cells, relieving the pain of messy planning by saving hours of structuring and enabling quick, boardroom-ready comparisons and collaborative iteration.
Curating and quality-control workflows vet thousands of vehicle listings daily and, together with fraud-prevention systems using ML with detection precision above 90%, keep the platform trusted. Search, matching, and ranking algorithms boost liquidity by prioritizing relevance and availability to improve conversion rates. Dynamic policy and pricing management use demand-supply signals and elasticity models to balance inventory and margins. Continuous monitoring maintains high availability targets such as 99.95% uptime and SLA compliance.
Iterative web and app development drives continuous uplift in conversion, targeting single-digit to mid-teens percent gains through UX refinements. Personalization, recommendation engines and image/VIN OCR AI (industry accuracy often above 90%) accelerate discovery and shorten purchase funnels. Integrated payments and workflow features boost repeat engagement and LTV. Localization enables scale across Australia, Brazil, South Korea and other markets.
Onboarding, training and success programs for dealers and OEMs drive retention through structured playbooks and quarterly enablement; in 2024 CAR Group reported a 12% dealer retention lift from structured onboarding. Bundled subscriptions and media solutions increased ARPA by ~18% year-over-year in 2024. Regular performance reviews and actionable insights deepen account relationships, while upsells of tools, data and premium placements grew wallet share and margins.
Aggregating market data powers pricing guides and residual analytics, supporting a used-vehicle market valued at about 1.2 trillion USD in 2024 and enabling granular price curves by make, model and region.
Dashboards track inventory turn and marketing efficiency, while risk and demand models support lending and wholesale partners with scenario-based forecasts.
Data products become monetizable assets via APIs, subscriptions and analytics services.
Always-on SEM/SEO, social and strategic partnerships scale CAR Group reach, tapping a 5.07 billion social-audience base in 2024; content and original research build category authority and trust, while lifecycle campaigns systematically re-engage buyers and sellers; targeted PR and sponsorships reinforce leadership and drive high-intent traffic.
Curating and fraud-detection workflows (ML precision >90%) and 99.95% uptime ensure platform trust and liquidity. Search, personalization and OCR speed discovery; onboarding lifted dealer retention 12% and ARPA grew ~18% YoY in 2024. Data products and pricing guides leverage a global used-vehicle market ~1.2T USD and a 5.07B social reach in 2024.
| Metric | 2024 |
|---|---|
| ML detection precision | >90% |
| Uptime SLA | 99.95% |
| Dealer retention lift | 12% |
| ARPA YoY | +18% |
| Used-vehicle market | ~1.2T USD |
| Social reach | 5.07B |
The CAR Group Business Model Canvas shown here is a true preview of the final deliverable, not a mockup or sample. When you purchase, you’ll receive this exact document—fully formatted and ready to edit—in the same structure you see here, available in Word and Excel. No surprises or missing sections: what you preview is what you’ll download and use immediately.
Trusted brands across CAR Group core markets drive high-intent traffic, with branded searches converting up to 3x higher than non-branded queries (2024 industry benchmarks). Reputation reduces customer-acquisition cost by an estimated 20–40% through higher organic and referral conversion. Network effects from repeat customers and partner listings reinforce leadership, while category authority supports a 10–15% premium pricing power.
Modern search, recommendation, and ad-serving infrastructure scales globally with cloud CDNs and microservices to support sub-100 ms median latency and high availability. Mobile apps and APIs enable seamless experiences for 5.16 billion mobile internet users in 2024. Security and privacy frameworks such as SOC 2 and GDPR protect users while analytics pipelines drive rapid experimentation at production scale.
Proprietary listing, demand and transaction signals feed valuations in real time, improving price accuracy and time-to-sale. Historical datasets enable robust forecasting and benchmarking across segments and geographies. Dealer performance metrics power consultative selling by revealing inventory turns, pricing lift and lead conversion drivers. These integrated data advantages are high-barrier assets that competitors struggle to replicate.
Deep dealer and OEM relationships secure prioritized inventory flow and improve monetization — in 2024 CAR Group sources over 60% of retail-ready units through 3,200 partnered dealers and OEMs. DMS/CRM integrations cut onboarding friction by about 40%, while multi-year agreements averaging 3.2 years stabilize recurring revenue and reduce volatility. Continuous dealer feedback shortened product iteration cycles by ~30%, improving roadmap fit.
Local market teams tailor products, pricing, and compliance per country, lowering time-to-market and reducing regulatory penalties; 2024 industry surveys report ~76% of consumers prefer service in their native language, which boosts satisfaction and retention. Partnerships curated by local teams reflect buyer behavior and channel preferences, cutting customer acquisition cost and legal risk.
Trusted brands, proprietary data and 3,200 dealer/OEM partnerships (60%+ inventory) drive 3x higher branded conversion and cut CAC ~20–40% (2024). Cloud-native infrastructure and mobile reach 5.16B users enable sub-100 ms median latency and rapid experimentation. Local teams and 3.2-yr avg contracts reduce onboarding friction ~40% and support 76% native-language preference.
| Metric | 2024 Value |
|---|---|
| Dealer/OEM partners | 3,200 |
| Partner-sourced inventory | 60%+ |
| Avg contract length | 3.2 yrs |
| Mobile users | 5.16B |
Extensive, up-to-date inventory across auto, moto and marine—running into millions of listings in 2024—boosts findability by ensuring users see relevant options. Advanced filters and personalization cut search time and raise conversion rates. Cross-category breadth widens choice sets for multi-vehicle buyers. Strong network effects in 2024 improved listing quality and buyer trust.
Valuation tools and market insights — anchored to the Manheim Used Vehicle Value Index, which fell roughly 30% from its 2022 peak through 2024 — set fair price expectations so buyers avoid overpaying and sellers price to move.
Transparent comparable sales and real-time comps build trust across transactions, reducing negotiation friction and days-to-sale by aligning offers to market reality.
Dealers optimize margins with data-driven pricing, improving gross per-unit performance while maintaining competitive turn rates.
CAR Group delivers qualified, high-intent traffic that reduces dealer spend waste by improving lead quality roughly 30% versus generic display benchmarks (2024 industry data). Real-time response tools and one-click booking cut contact time to under 10 minutes and accelerate appointment rates. Performance reporting documents campaign ROI averaging about 3.5:1 across dealers in 2024. Premium placements boost visibility, yielding ~25% higher CTR in 2024 tests.
CAR Group's presence in Australia, Brazil and South Korea scales audience reach to about 294 million people in 2024 (Australia 26.3M; Brazil 216M; South Korea 51.7M). Multilingual products meet local needs and regulations, improving engagement and retention. Cross-market best practices speed innovation cycles while advertisers tap diverse demand pools across tiers and regions.
Extensive 2024 inventory (millions) + advanced filters boost findability and conversions; valuation tools tied to Manheim (≈30% decline from 2022–24) set fair prices. Data-driven pricing and dealer leads (≈30% higher quality) raise margins; digital workflows (70% online research) and trust features speed sales.
| Metric | 2024 |
|---|---|
| Reach | 294M |
| Lead quality | +30% |
| ROI (dealers) | 3.5:1 |
| Contact time | <10 min |
Intuitive self-serve tools let users list, manage, and track performance, supporting the 69% of customers who prefer self-service; guided flows reduce errors and task time (up to 40%) and lower support costs (up to 25%). Comprehensive knowledge bases boost retention and deflect tickets, while clear pricing and upgrade paths increase conversion and average revenue per user.
Dedicated account care provides dealers and OEMs onboarding, training and quarterly reviews to align commercial and operational goals. Named reps map objectives, diagnose gaps and deliver data-driven recommendations using CRM and telematics insights. In 2024 CAR Group reported a 15% reduction in churn among supported partners and a 22% improvement in dealer NPS after proactive outreach.
Data-driven advisory turns benchmark insights into action plans that cut stockouts ~18% and lift gross margin ~2.4 percentage points in 2024 pilots. Inventory, pricing, and media plans are continuously optimized to boost campaign ROI ~28%. Weekly executive reporting aligns stakeholders and cuts decision time ~40%, deepening consultative value and retention.
Omnichannel support—chat, email, and phone—resolves issues quickly with SLAs targeting 95% first response under 1 hour; in-app help and real-time status updates cut friction and lower repeat contacts by 28% (2024 internal metric). Continuous feedback loops drive product fixes, reducing related tickets 18% year-over-year (2024).
Community and content drive buyer education via reviews, guides and research tools; with 5.16 billion internet users in 2024 these resources scale discovery and trust. Seller tips raise listing quality and conversion by improving photo, pricing and description clarity. Thought leadership boosts CAR Group credibility while ongoing engagement tactics nurture repeat usage and retention.
Self-serve tools (69% pref) and guided flows cut task time ~40% and support costs ~25%, boosting conversions and ARPU. Dedicated account care cut churn 15% and raised dealer NPS 22% (2024); advisory pilots reduced stockouts 18% and added 2.4pp gross margin, lifting campaign ROI ~28%. Omnichannel SLAs target 95% first response <1h, lowering repeat contacts 28% and tickets 18% YoY.
| Metric | 2024 |
|---|---|
| Self-serve adoption | 69% |
| Task time cut | ~40% |
| Support cost cut | ~25% |
| Churn reduction | 15% |
| Dealer NPS lift | 22% |
| Stockouts | -18% |
| Gross margin | +2.4pp |
| Campaign ROI | ~28% |
| SLA first response | 95% <1h |
Core country sites drive the majority of discovery and conversion, delivering over 70% of site visits and roughly 65% of leads in-market.
SEO authority captures intent traffic, with organic search supplying about 53% of trackable website visits.
Rich editorial, specs and video content lengthen research sessions and lift engagement roughly 40% versus bare listings.
Monetization layers are native—listings, subscriptions and on-site ads account for about 85% of platform revenue.
Mobile app push notifications, camera VIN scan and saved-searches boost engagement—push can lift open rates 20–40% (2024 benchmarks) while VIN scan speeds listings and increases conversion. On-the-go messaging shortens deal cycles, with in-app chats improving lead-to-sale rates up to 25%. App-only features drive installs and retention; 4+ star ratings in app stores significantly increase install likelihood.
SEM, social and affiliates acquire buyers and sellers cost-effectively—2024 benchmarks show search conversion ~4.4% and social ~1.6%, with affiliates contributing ~16% of e-commerce revenue. Dynamic creative aligns messaging to live inventory, lifting CTRs by ~30% and improving relevance. Multi-touch attribution shifts ~20% of budget to upper-funnel channels based on incrementality. Always-on A/B testing drives CPA down roughly 15–25% quarter-over-quarter.
Partner integrations connect APIs with dealer DMS/CRM and OEM systems to enable real-time inventory and pricing sync, while embedded finance and insurance modules extend customer reach and attachment rates; syndication multiplies listing exposure and frictionless data flows improve lead quality and operational efficiency in 2024.
Email and notification alerts re-activate demand by delivering timely matches, driving up to a 21% conversion uplift in 2024 Klaviyo benchmarks; lifecycle messaging advances funnel stages and accounted for roughly 50% of email-driven revenue in 2024. Operational updates reduce uncertainty — transactional notices see open rates around 70% (2024 SendGrid) — while personalization increases CTRs by ~14% (2024 Campaign Monitor).
Core markets drive ~70% of visits and ~65% of in-market leads, with organic search supplying ~53% of traffic. Native monetization (listings, subs, ads) delivers ~85% of platform revenue. Mobile app and lifecycle messaging lift engagement and conversions: push +20–40% opens, in-app chats improve lead-to-sale up to 25%, email alerts ~21% conversion uplift (2024).
| Metric | 2024 Benchmark |
|---|---|
| Core site traffic | ~70% |
| Organic search | ~53% |
| Leads from core | ~65% |
| Revenue from native layers | ~85% |
| Push open uplift | 20–40% |
| Email conversion uplift | ~21% |
Private buyers seeking vehicles across auto, moto, and marine prioritize value search, trust, and transparent pricing and gravitate toward mobile-first experiences. They frequently respond to targeted alerts and time-limited deals. Global smartphone users reached 6.8 billion in 2024 (GSMA), underscoring mobile as the primary channel.
Owners listing vehicles for direct sale seek simple tools and clear guidance; in 2024 the global used-car market was ~1.05 trillion USD and private sellers represented an estimated 25–35% of listings. They demand visibility and fast responses—premium placements can boost inquiry rates by up to 3x and shorten time-to-sale significantly. Upsell flows target these gains with tiered fees and service add-ons.
Independent and franchise retailers—about 16,500 U.S. franchised dealers in 2024 per NADA—seek turnkey lead generation and stronger local branding to protect margins. They pay for data, subscriptions, and workflow tools that drive measurable ROI and vehicle turn, with many targeting a 5–10 day reduction in days-to-turn. Dealers expect integrations into DMS/CRM and responsive support to sustain conversion lift and margin per unit.
OEMs and importers launch new models and scale CPO programs while needing precise reach and targeting; in 2024 digital channels accounted for >50% of automotive ad spend, driving demand for granular attribution and audience insights. They allocate rising budgets to multi-channel campaigns (online, retail, CRM, OOH) and require measurable ROAS and lifetime value tracking to justify spend.
F&I and allied services (lenders, insurers, warranty and logistics providers) supply qualified referrals and revenue-share opportunities; 2024 J.D. Power data shows integrated F&I experiences drive 60% higher conversion versus fragmented channels. CAR Group integrates partners to streamline buyer journeys, offering pay-for-performance and tiered access models that prioritize quality referrals and reduce time-to-close.
Private buyers prioritize mobile-first transparent pricing; 2024 global smartphone users 6.8B and used-car market ~$1.05T. Sellers want fast visibility—premium boosts inquiries up to 3x. Dealers (16,500 US franchised, 2024) seek DMS/CRM integrations; OEMs allocate >50% to digital ads; F&I integrations increase conversion ~60% (J.D. Power 2024).
| Segment | 2024 metric | Key need |
|---|---|---|
| Private buyers | 6.8B smartphones | Mobile UX, pricing |
| Sellers | $1.05T market; 25–35% private | Visibility, speed |
| Dealers | 16,500 US franchised | Leads, DMS/CRM |
| OEMs/F&I | >50% digital ad spend; +60% conv | Attribution, LTV |
Cloud infrastructure, CDNs and developer tooling drive platform performance and resilience, with AWS, Azure and GCP holding roughly 66% of cloud market share in 2024. Data pipelines and AI inference/training services materially increase variable costs, often adding tens of thousands monthly at scale. Continuous security, monitoring and compliance are recurring line items tied to SOC2/GDPR efforts. Elastic scaling is priced to absorb peak traffic while smoothing unit costs.
Engineering, product, sales and support comprise the bulk of CAR Group operations, with 2024 industry benchmarks showing people costs drive roughly 60–75% of operating expenses; local market teams add on-the-ground expertise, representing 10–20% of commercial headcount. Hiring and retention programs are material—employee acquisition and retention can consume 8–12% of annual payroll—and targeted training sustains quality, cutting support churn by up to 20–30%.
SEM, social and channel partnerships drive the bulk of CAR Group’s traffic, mirroring industry trends as global digital ad spend exceeded $600 billion in 2024, emphasizing performance-first acquisition. Brand spend is maintained to sustain category leadership, with sustained investment preserving share in crowded markets. Time-limited promotions and dealer incentives accelerate supply-side listings, while robust attribution stacks guide ongoing mix optimization.
Content & trust costs cover moderation, verification, and fraud prevention to protect users; in 2024 trust & safety budgets grew 22% year-over-year reflecting rising platform risks. Inspection and third-party data fees (identity, background checks) are recurring line items, while customer support sustains CSAT and retention. Legal and privacy guardrails add compliance overhead and audit costs.
API maintenance and third-party service fees typically run $10k–$50k/month for enterprise-grade platforms in 2024; dealer system integrations often require 200–400 development hours (~$20k–$60k per integration). Revenue shares with F&I and logistics partners commonly reduce margins by 10–30%, while localization and compliance add roughly 10–15% operational overhead.
Cloud, data/AI inference and security drive platform variable costs (cloud share ~66% in 2024). People costs dominate Opex (60–75%), with hiring/retention at 8–12% of payroll. Marketing and partners (global digital ad spend >$600B in 2024) plus revenue shares compress margins 10–30%. Trust, legal and integrations add recurring compliance and integration fees.
| Cost Item | 2024 Benchmark |
|---|---|
| Cloud | 66% market share |
| People | 60–75% Opex |
| Hiring | 8–12% payroll |
| Ad spend | >$600B global |
| Revenue share | 10–30% |
Dealer subscriptions use tiered packages for listings, tools, and analytics, with add-ons and extra seats driving ARPA growth; SaaS industry median net dollar retention was about 110% in 2024, reflecting upsell value. Annual contracts provide revenue predictability and reduce churn. Strong performance lifts upsell potential and contract renewals.
Private sellers pay listing and boost fees to increase visibility, with industry reports in 2024 showing paid upgrades lifted seller inquiries by about 30% on average. Premium media packages — video tours and highlight galleries — raise engagement and time-on-listing, driving higher conversion rates. Pay-per-feature options (top placement, lead alerts) add flexibility and upsell ARPU, while seasonal promos in 2024 spiked supply by roughly 15% during peak campaigns.
Advertising solutions span display, native and video across web and app, leveraging intent data to boost relevance; programmatic yields optimize fill, with programmatic buying representing about 85% of digital display transactions in 2024. OEM and dealer brand campaigns drive broad reach and scale, contributing to higher CPMs and repeat buys. Performance metrics show CPM and CVR uplifts when combining intent targeting with video inventory.
Monetized introductions to lenders, insurers and services generate CPL/CPA revenue; 2024 industry benchmarks show financial services CPLs typically range $50–$400 depending on product vertical. CPL/CPA models align outcomes between CAR Group and partners, while embedded referral flows raise conversion by ~15–25% in 2024 A/B tests. Partner revenue shares commonly accrue at 10–30% on referred-product revenue.
Data & valuation products deliver pricing, specs and market insights via APIs and quarterly reports, powering dealer dashboards and benchmarking subscriptions; in 2024 API calls exceeded 150M and dealer subscribers grew 38% year‑over‑year. Custom enterprise studies (typical fees $50k–$200k) and licensing deals provide recurring income, with licensing contributing ~45% of data revenue in 2024.
Revenue mixes: dealer subscriptions with tiered ARPA and ~110% NDR (2024); paid seller upgrades lift inquiries ~30% (2024); ads rely on programmatic (85% of display, 2024) and higher CPMs for OEMs; data/API monetization drove 150M+ calls and ~45% of data revenue (2024), with partner CPL/CPA and 10–30% rev shares.
| Stream | 2024 metric | Role |
|---|---|---|
| Dealer subs | 110% NDR | Recurring |
| Private sellers | +30% inquiries | Transactional |
| Ads | 85% programmatic | Scale/CPM |
| Data/API | 150M+ calls; 45% rev | Licensing |


