
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Chick-fil-A’s Porter's Five Forces snapshot highlights high buyer loyalty, moderate supplier power, intense rivalry in quick‑service chicken, low threat of substitutes for core menu, and barriers limiting new entrants. Strategic strengths include real estate cachet and franchise efficiency, while risks stem from supply chain and regulatory pressures. This brief only scratches the surface—unlock the full Porter's Five Forces Analysis to explore force-by-force ratings, visuals, and actionable insights.
Chicken is the core input and US broiler production is relatively concentrated, with the top four processors controlling roughly 60% of supply, boosting supplier leverage. Large avian flu outbreaks in 2022–23 led to ~58 million birds culled and feed costs (≈70% of production cost) have spiked intermittently, tightening supply and raising prices. Chick‑fil‑A mitigates risk via multi‑sourcing and long‑term contracts and its scale (≈2,900 restaurants in 2024) provides countervailing negotiation power.
Chick-fil-A’s strict product specifications and food-safety standards narrow the pool of qualified vendors, increasing supplier leverage. Fewer approved suppliers raise switching costs and bargaining power, especially given scale across roughly 2,900 restaurants and estimated $18.5 billion systemwide sales in 2024. Standardization and predictable demand enable suppliers to plan capacity efficiently. Robust compliance and audit programs enforce consistency while mitigating supply risk.
Chick-fil-A’s proprietary sauces and certain branded inputs, produced by approved co-packers for its network of over 2,900 U.S. restaurants in 2024, can be single- or few-sourced, creating supplier dependency. This concentration raises supplier power when alternates are scarce, but dual-sourcing and strict supply contracts can curb that leverage. Strategic inventory buffers and co-manufacturing arrangements further reduce disruption impact.
Timely, temperature-controlled distribution is critical to Chick-fil-A’s service levels; in 2024 the chain’s about 3,000 restaurants generated volumes that justify dedicated refrigerated routes and lower per-unit freight, reducing supplier leverage in national lanes. Regional cold-chain partners can command leverage in constrained markets, but network optimization and multiple RDCs limit exposure to any one node.
Chick‑fil‑A’s limited, chicken‑centric menu reduces SKU complexity and supplier fragmentation, enabling deeper partnerships and improved terms; the chain operated about 2,900 U.S. restaurants in 2024 and leverages concentrated sourcing to support systemwide scale. Category concentration raises exposure if poultry markets tighten, so tight inventory control and commodity hedging are used to stabilize costs.
Chick‑fil‑A faces moderate supplier power: top-four US broiler processors ≈60% share and 2022–23 avian flu culled ~58M birds, raising prices; scale (~2,900–3,000 US restaurants, ~$18.5B systemwide sales 2024) and long-term contracts lower leverage. Strict specs and few approved co-packers increase switching costs; cold‑chain needs create regional bottlenecks. Hedging, multi‑sourcing and RDCs mitigate risk.
| Metric | Value |
|---|---|
| US restaurants (2024) | ~2,900–3,000 |
| Systemwide sales (2024) | $18.5B |
| Top-4 broiler share | ~60% |
| Birds culled (2022–23) | ~58M |
 Detailed Word Document
Provides a concise Porter’s Five Forces assessment of Chick-fil-A, revealing competitive intensity, supplier and buyer power, and the threat of substitutes and new entrants. Highlights strategic advantages, emerging threats, and implications for pricing, profitability, and market positioning.

 Customizable Excel Spreadsheet
A clear, one-sheet Porter's Five Forces analysis tailored to Chick‑fil‑A—visualizes competitive pressures, supplier/buyer leverage, and threat of entrants/substitutes to simplify strategic decisions and drop directly into pitch decks.
Fast-food customers face low switching costs and can shift to rivals for price, taste, or convenience, constraining Chick-fil-As pricing power and forcing tight operational consistency. Competitor promotions and value menus can quickly divert traffic, evident in 2024 when Chick-fil-A operated over 2,900 U.S. locations and still saw market share contests from national chains. Chick-fil-A leans on superior service quality and perceived value to retain loyalty.
High customer satisfaction and a consistent experience at Chick-fil-A—with over 3,000 restaurants as of 2024—substantially reduce effective buyer power, as loyal guests tolerate modest price increases and limited menu variety. Community engagement and a rewards program with millions of members deepen stickiness, while fast service and signature hospitality reinforce repeat visits and high visit frequency.
Value seekers at Chick-fil-A respond strongly to combo pricing and limited-time offers, while affluent and convenience-focused customers prioritize time savings over modest price differences; Chick-fil-A’s average unit volume remains above $5M, reflecting pricing power. Delivery markups, often $3–5 per order in 2024, can test willingness to pay. Tiered offerings (value combos vs premium items) help manage differing elasticity across segments.
Mobile, curbside and delivery channels increase transparency on price and wait times, strengthening buyer bargaining as cross-app comparisons rise; Chick-fil-A’s fast digital throughput and 2024 industry digital penetration near 30% help preserve perceived value. Personalization and rewards in Chick-fil-A’s app create switching friction, while operational throughput offsets digital scrutiny by maintaining short waits.
Health, animal welfare, and diet trends in 2024 (roughly 9% of US adults identifying as vegetarian/vegan) can shift demand away from fried chicken; negative publicity can rapidly change customer choice and visit frequency. Grilled sandwiches and salads, which made up an increasing share of menu mix in 2024, partially offset sensitivity. Clear sourcing and nutrition communication reduce perception risk and support retention.
Loyalty offsets price transparency — AUV >$5M, >3,000 US units, ~30% digital
Low switching costs and price transparency constrain Chick-fil-A’s pricing, yet high satisfaction, app rewards and signature service create strong loyalty and allow modest price power; AUV remains above $5M with over 3,000 U.S. locations (2024). Delivery markups ($3–5) and ~30% digital penetration raise buyer bargaining via cross-app comparison, while menu diversification limits churn.
| Metric | 2024 |
|---|---|
| U.S. locations | >3,000 |
| Average unit volume | >$5M |
| Digital penetration | ~30% |
| Delivery markup | $3–5 |
| Vegetarian US | ~9% |
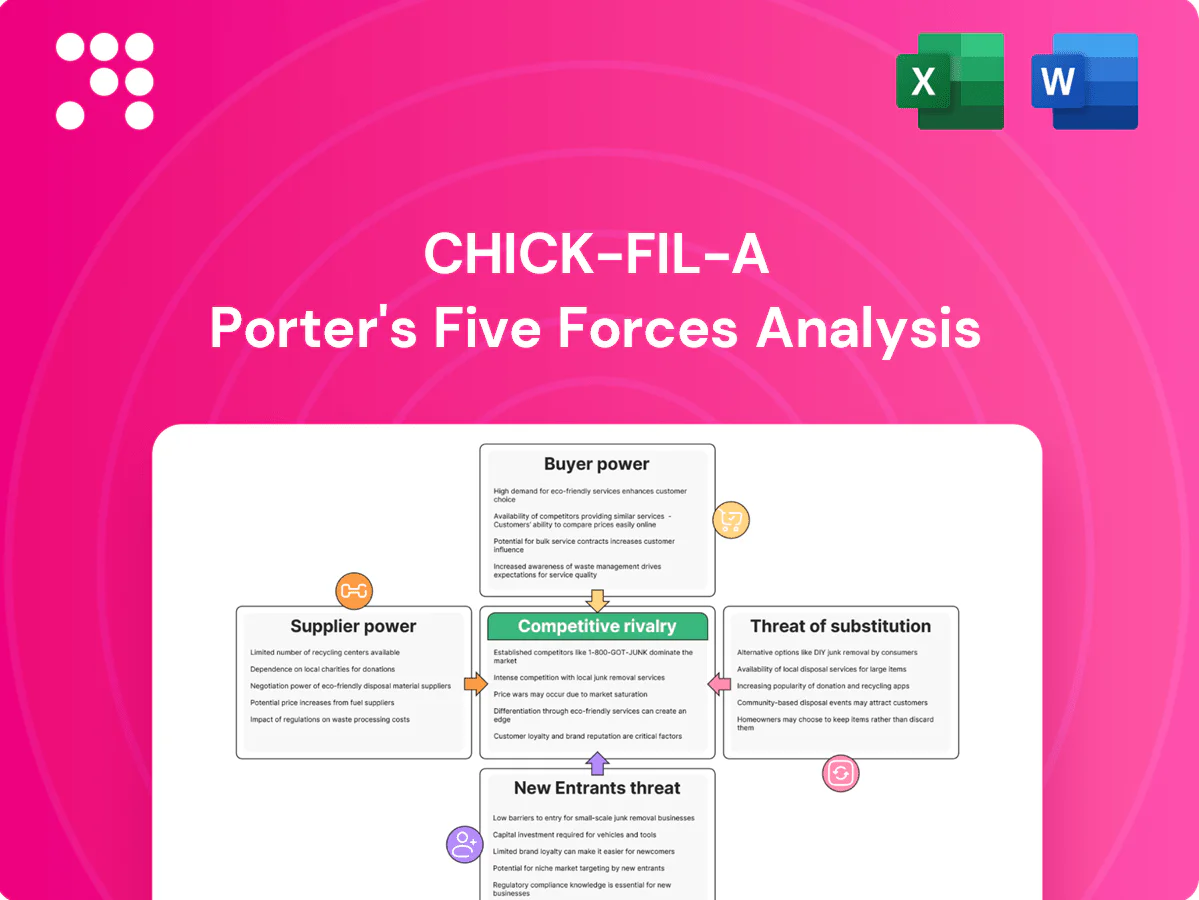
This preview shows the exact Chick-fil-A Porter's Five Forces analysis you'll receive after purchase—fully formatted and ready to use. It examines competitive rivalry, supplier and buyer power, and threats of entrants and substitutes, with clear strategic implications. No placeholders or samples are included. You'll get instant access to this same file after payment.
Popeyes, KFC, McDonald’s, Wendy’s, and Raising Cane’s aggressively contest the chicken sandwich category, with McDonald’s ~40,000 and KFC ~24,000 global restaurants, Wendy’s ~6,800, Popeyes ~3,700 and Raising Cane’s ~700 (2024). Product launches and the so-called chicken wars have driven heavy ad spend and heightened taste-test coverage, while social media amplifies head-to-head comparisons. Differentiation through faster service, order accuracy and consistency remains critical to capture share.
Drive-thru throughput, site selection and queue management are critical levers in the location and convenience battle; Chick‑fil‑A operates about 3,000 U.S. restaurants (2024) and optimizes layouts to maximize peak-hour throughput. Rivals deploy dual‑lane drive‑thrus, kitchen automation and digital pickup to claw share. Sunday closure yields a predictable weekly sales opportunity for competitors. Superior operations often trump small price differences in market share dynamics.
Value menus and limited-time offers create traffic volatility across QSRs; Chick-fil-A sees steady AUV around $6.2 million (2023), allowing it to avoid frequent promotions. Aggressive discounting elsewhere can compress margins industry-wide, but Chick-fil-A typically relies on perceived quality and service rather than deep discounts. Its consistent demand and high AUV cushion the brand against prolonged price wars.
Chick-fil-A’s exceptional hospitality and intensive crew training create a durable service moat that competitors struggle to replicate at scale, raising imitation costs and preserving unit economics; 2024 systemwide sales exceeded $18 billion, underscoring stable traffic in saturated trade areas.
Chick-fil-As owner/operator model drives strong local accountability and consistent execution, supporting average unit volumes near $6.7M and roughly 2,900 restaurants in 2024, which cushions pricing and service competition. Corporate-run rivals often show greater performance variability, allowing Chick-fil-A to sustain comparable sales in mature markets. Disciplined execution limits rivalry’s pressure on margins and profitability.
Chick‑fil‑A faces intense rivalry from McDonald’s (~40,000), KFC (~24,000), Wendy’s (~6,800), Popeyes (~3,700) and Raising Cane’s (~700) (2024). Drive‑thru throughput, LTOs and social media amplify share battles. Chick‑fil‑A’s 2,900 U.S. units, ~$6.7M AUV and $18B+ system sales (2024) sustain pricing power and margins. Owner/operator model and service training raise imitation costs.
| Brand | Units (2024) | AUV |
|---|---|---|
| McDonald’s | ~40,000 | — |
| KFC | ~24,000 | — |
| Wendy’s | ~6,800 | — |
| Popeyes | ~3,700 | — |
| Raising Cane’s | ~700 | — |
| Chick‑fil‑A | ~2,900 | ~$6.7M |
Household meal prep and supermarket delis offer cheaper per-serving alternatives, and inflation-driven budget pressure has driven shoppers toward grocery prepared meals. Convenience gains from ready-to-eat supermarket hot bars blur lines with QSR, shrinking frequency of visits for some customers. Chick-fil-A counters with superior speed, consistency, and taste to preserve share against this substitute threat.
Salad, bowl, and Mediterranean chains increasingly attract health-conscious diners, with surveys in 2024 showing over 40% of U.S. consumers prioritizing freshness when choosing restaurants. The perception of fresher, customizable meals can lure Chick‑fil‑A customers and supports price premiums accepted by some segments. Growth of grilled items and lighter sides on Chick‑fil‑A’s menu reduces overall substitution risk.
Burgers, pizza, tacos and deli sandwiches fulfill many of the same quick-occasion needs as chicken, and chains like McDonald’s (global revenue ~26 billion USD in 2024) and pizza/taco players extend capture with broad late‑night and breakfast menus. Bundled family deals in other categories intensify substitution by lowering per-person cost and increasing average ticket. Chick‑fil‑A’s focused menu trades breadth for speed and quality, limiting occasion overlap but ceding some time‑window share.
Grab-and-go coffee, bakery and C-store hot items increasingly substitute small Chick-fil-A meals as 152,000 U.S. convenience stores in 2024 expand foodservice and extended hours, boosting availability; typical C-store coffee (~$1.50) and hot snacks often undercut QSR meal prices (~$5), though Chick-fil-A’s quality and service differentiation limit switching.
Substitutes (grocery prepared meals, salads, burgers, C-store grabs, delivery) compress occasions and price-sensitive share despite Chick-fil-A’s speed, taste and service. Health-focused chains and supermarket ready-to-eat options appeal to >40% of consumers prioritizing freshness (2024), while extended hours and lower price points raise availability. Delivery platforms and C-stores amplify convenience; Chick‑fil‑A mitigates via owned app and fulfillment.
| Substitute | 2024 metric | Impact |
|---|---|---|
| C-stores | 152,000 US | Higher availability, lower price |
| Delivery | DoorDash ~55% share; fees 15–30% | Convenience, margin pressure |
| Health/ready-to-eat | >40% prioritize freshness | Attracts premium-seeking diners |
| Broad QSR | McDonald’s rev ~26B USD | Occasion overlap |
Chick-fil-A’s dominant brand—with roughly $20.1 billion in systemwide sales and average unit volumes near $6.8 million in 2024—creates high brand and loyalty barriers for newcomers. Entrants must invest heavily in awareness and trust to compete, while Chick-fil-A’s strong word-of-mouth and deep community ties are difficult to replicate quickly. Elevated repeat visit rates slow market share capture for new rivals.
Throughput, order accuracy and hospitality are core capabilities at Chick-fil-A; its ~2,900 units in 2024 rely on high-speed drive-thru and service systems to sustain strong unit economics. New entrants face steep learning curves and elevated training costs to replicate sub-3-minute throughput and accuracy. Consistent execution across locations is difficult without mature systems, and failure to match Chick-fil-A service standards limits market traction.
Prime drive‑thru sites with good traffic and ingress/egress are highly constrained, and incumbents like Chick‑fil‑A aggressively lock up favorable parcels and landlord relationships; high build‑out costs and zoning delays in 2024 continue to deter new entrants, while operators forced onto secondary sites suffer materially weaker unit economics and lower AUVs versus company averages.
Securing reliable poultry supply, distribution and QA at Chick‑fil‑A scale is complex; Chick‑fil‑A operated about 2,900 restaurants in 2024, giving incumbents meaningful volume leverage.
Large incumbent volumes command better pricing and priority from processors and distributors, raising barriers for entrants who face higher input costs and variability.
Dependence on co‑packs and third‑party distributors can erode margins and consistency for new entrants, increasing capital and operational needs.
While a single Chick-fil-A unit’s capital requirement is moderate, scaling to multi-unit or regional rollouts demands sustained funding and 2024 financing scrutiny; tight labor markets in 2024 and high training costs elevate operating risk. Established chains offer clearer career paths and stability, raising the threshold for viable entrants and expansion.
Chick‑fil‑A’s scale — ~$20.1B systemwide sales, ~2,900 units and AUV ≈ $6.8M in 2024 — creates steep brand, supply and site barriers that slow entrant market share. Replicating sub‑3‑minute throughput, service consistency and supplier leverage requires heavy capex, training and supply commitments. Tight 2024 labor markets and premium real estate further raise break‑even thresholds for new chains.
| Metric | 2024 Value |
|---|---|
| Systemwide sales | $20.1B |
| Units | ~2,900 |
| AUV | ≈ $6.8M |
| Throughput target | sub‑3 minutes |


