
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
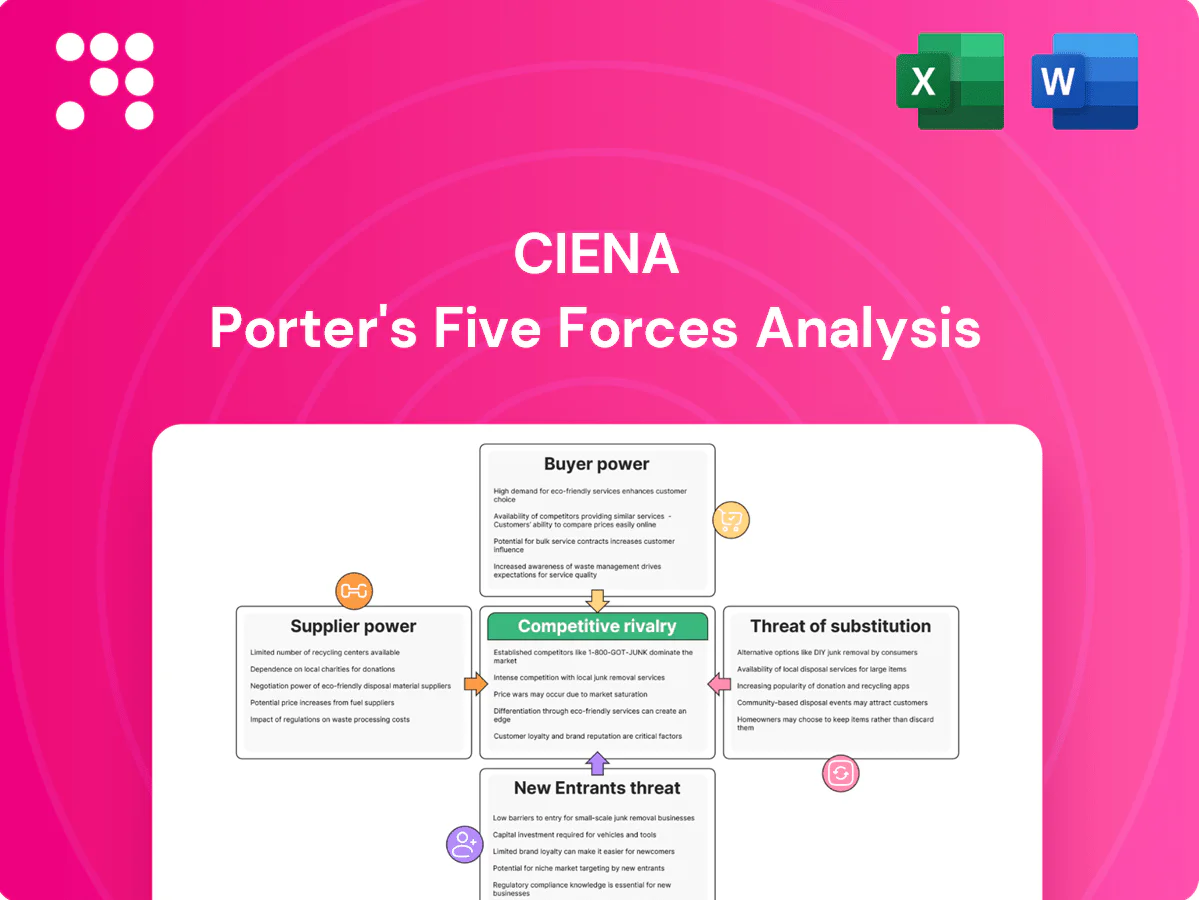
Ciena’s Porter's Five Forces snapshot highlights strong supplier power, intense rivalry, moderate buyer leverage, low threat of substitutes, and meaningful barriers to entry. These forces shape margins and strategic choices across optical networking and services. This brief teaser only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Ciena’s competitive dynamics in detail.
Ciena depends on a narrow supplier base for coherent DSPs, high-end optics and specialty semiconductors, which increases supplier leverage during tight cycles or process-node transitions. In 2024 semiconductor lead times remained elevated at 20+ weeks, amplifying risk to Ciena’s delivery cadence and cost structure. Dual-sourcing is feasible for some legacy parts but not for bleeding-edge components, so any disruption can ripple through margins and backlog.
Critical ASICs and modules for Ciena rely on advanced foundries and contract manufacturers; TSMC and Samsung together controlled roughly 70% of advanced-node capacity through 2023–2024, concentrating supplier power. Capacity constraints or node migrations have repeatedly shifted pricing leverage to suppliers, raising component costs. Long qualification cycles, typically 12–18 months, make rapid switching difficult. This dependence can compress Ciena margins during supply imbalances.
Key Ciena modules embed supplier-owned IP in lasers, modulators and pluggables, and the global optical transceiver market was roughly USD 11B in 2024, concentrating bargaining power with incumbents. Proprietary designs limit interchangeability and can raise switching costs, with IP holders able to command premiums often in the 10–30% range for newest performance tiers. Ciena reduces exposure through in-house optics design and close co-development with key suppliers to retain margin and roadmap control.
Specialty optical materials and global logistics raise cost and availability risk for Ciena; in 2024 supply-chain fragility contributed to longer lead times for tunable lasers and photonic components. Geopolitical export controls on advanced optics and semiconductors further constrain sourcing. Buffer inventory reduces stockouts but ties up working capital against Ciena’s ~3.1B 2024 revenue, boosting supplier leverage when their chains are compliant and resilient.
Development tools, firmware, and testing platforms for Ciena often originate from niche vendors, creating dependency that lets suppliers dictate licensing and support terms which can delay delivery schedules and maintenance windows.
Deep integration into Ciena’s optical hardware and network OS raises switching friction, increasing migration costs and time; vendors with unique testbeds or firmware expertise can command higher fees and stricter SLAs.
Ciena faces high supplier leverage due to narrow sources for DSPs, optics and specialty semiconductors; 2024 semiconductor lead times >20 weeks and node concentration raise delivery and cost risk. TSMC+Samsung held ~70% advanced-node capacity (2023–24), and the optical transceiver market was ~USD 11B in 2024, amplifying supplier pricing power.
| Metric | 2024 Value |
|---|---|
| Lead times | >20 weeks |
| Foundry concentration | TSMC+Samsung ~70% |
| Optical market | ~USD 11B |
| Ciena revenue | ~USD 3.1B |
 Detailed Word Document
Uncovers competitive drivers, buyer and supplier power, threat of substitutes and new entrants, and intensity of rivalry shaping Ciena’s pricing, margins, and strategic positioning, while highlighting disruptive technologies and defenses that protect or threaten its market share.

 Customizable Excel Spreadsheet
A concise Porter's Five Forces summary for Ciena—visualize competitive pressures, supplier and buyer leverage, and threat of substitutes to quickly identify strategic pain points and prioritize high-impact responses.
Large carriers, hyperscalers and governments drive a significant share of Ciena’s business; Ciena reported $3.94 billion revenue in FY2024 with its top customers accounting for roughly 45% of sales, boosting buyer leverage. Their scale and sophisticated procurement teams extract favorable pricing and contractual terms. Competitive RFPs further compress margins and push tougher SLAs. Losing a key account would materially dent growth and cash flow.
Open standards like Open ROADM and 400/800G enable multi-vendor environments, reducing vendor lock-in and lowering technical switching barriers. Operational integration, end-to-end orchestration and strict service SLAs still anchor provider relationships, slowing churn. Buyers leveraged interoperability in 2024 to extract better commercial terms; Ciena reported roughly $3.3B revenue in FY2024, reflecting intense pricing and design competition.
Extensive 12–24 month lab and field trials typically precede volume awards for Ciena, with buyers using evaluation stages to extract concessions; fiscal 2024 revenue was about $4.08 billion, highlighting the scale behind protracted deals. Multi-year framework agreements lock in price curves, which together cap vendors’ near-term pricing power despite technology leadership.
Customers prioritize lifecycle cost, energy efficiency and automation outcomes; Ciena’s FY2024 revenue of about $3.7B underscores buyer leverage as operators demand proof of throughput gains and opex cuts to justify purchases, plus bundled support and flexible financing—forcing vendors to share efficiency gains through pricing and commercial terms.
Many operators rationalize supplier counts to 3–5 preferred vendors by 2024 to streamline procurement and operations, making preferred-vendor status a gatekeeper for network RFPs. Consolidation boosts selected vendors’ volume but increases buyer leverage in negotiations. MSAs in 2024 routinely embed price and SLA penalty clauses that compress supplier margins and shift risk back to vendors.
Large buyers drive strong leverage: Ciena FY2024 revenue ~$3.94B with top customers ~45% of sales, enabling tougher pricing and SLAs. Open standards and multivendor RFPs lower switching costs, while 12–24 month trials and 3–5 preferred-vendor rationalization maintain procurement control. MSAs with price/SLA penalty clauses are routine, compressing vendor margins.
| Metric | Value |
|---|---|
| FY2024 revenue | $3.94B |
| Top-customer share | ~45% |
| Procurement cycle | 12–24 months |
| Preferred vendors per operator | 3–5 |
This preview shows the exact Porter's Five Forces analysis for Ciena you’ll receive after purchase—complete, professionally formatted, and data-driven. It contains the full competitive assessment, force-by-force evaluation, and strategic implications ready for immediate download. No placeholders or samples: the file displayed is the file you get, ready for use upon payment.
Ciena competes head-to-head with Nokia, Huawei, Cisco and Infinera across regions, where rivals bring deep product portfolios and entrenched carrier relationships. Regional policy and security rules, notably U.S. restrictions on Huawei, regularly reallocate share and supplier eligibility. Continuous multi-year and short-cycle RFPs keep bid pressure high; Ciena reported FY2024 revenue of about $3.63 billion, underscoring scale constraints versus larger incumbents.
Rapid shifts from 400G to 800G and emerging 1.6T (doubling per generation) force leapfrogging; by 2024 major vendors demonstrated 1.6T coherent tech. Performance/price gains quickly commoditize prior gens, so vendors invest hundreds of millions annually in R&D to defend share; missing a single cycle can cause double-digit share erosion within 12–24 months.
Large tenders for Ciena hinge on unit economics and TCO, with FY2024 revenue ~$3.2B and non-GAAP gross margin near 40% underscoring scale pressures. Discounting and rebates are common to secure footprint, especially in multi-year supply deals where suppliers concede 5–15% price concessions. Services and software differentiation temper but do not eliminate price pressure, as customers still prioritize capex and opex savings. Margin erosion risks persist in high-volume optical and packet transport deals.
Open line systems and pluggable optics enable mix-and-match architectures that fragment value pools and invite module-centric rivals; the pluggable optics market was about $3.2B in 2024 while Ciena reported roughly $3.6B revenue in FY2024, underscoring stakes for incumbents.
Aftermarket and services are central to Ciena's rivalry: lifecycle services, orchestration software and automation are primary battlegrounds, with Ciena reporting about $3.29 billion revenue in fiscal 2024 as it pushes software-led offers to defend optical hardware pricing.
Ciena faces intense rivalry from Nokia, Huawei, Cisco and Infinera; FY2024 revenue $3.63B highlights scale constraints vs larger incumbents. Rapid shifts (400G→800G→1.6T) commoditize generations and force heavy R&D or share loss. Open line systems and a $3.2B pluggable optics market (2024) fragment value pools; software/services are essential to defend margins.
| Metric | 2024 |
|---|---|
| Ciena FY2024 revenue | $3.63B |
| Non-GAAP gross margin | ~40% |
| Pluggable optics market | $3.2B |
5G FWA can provide gigabit-class access and microwave backhaul delivers multi-Gbps links, substituting fiber in select last-mile scenarios. For core/backbone, fiber supports 100G, 400G and 800G wavelengths commercially available by 2024 and typically outperforms wireless on capacity and latency. Still, wireless options defer optical build-outs in cost-sensitive markets, reducing near-term demand for transport gear.
Operators increasingly lease dark fiber or wavelengths, converting upfront capex to opex and delaying vendor equipment sales; the global dark fiber market was valued at about $2.4 billion in 2024, reflecting rising wholesale uptake. In mature wholesale markets substitution risk is higher, though stringent SLAs and latency/control needs still lead many carriers to own gear for critical routes.
Cloud-managed networking threatens Ciena as hyperscalers bundle connectivity and edge services that abstract transport: in 2024 AWS (31%), Azure (23%) and Google Cloud (11%) dominate cloud infrastructure, shifting buyer preference to integrated stacks. Customers increasingly favor platform-led over bespoke builds, moving value toward software. Vendors must embed into hyperscaler ecosystems or risk disintermediation.
LEO constellations (Starlink >2m subs in 2024) push broader reach and latency into the low tens of milliseconds, making them viable for remote sites and backhaul where terrestrial buildouts are slow; they can offset fiber expansion timelines on certain routes. However capacity and cost per bit still lag fiber in dense corridors—single fiber trunks carry Tbps at far lower $/bit—so substitution is niche and route- and timeline-specific.
Substitution risk is moderate: 5G FWA, LEO (Starlink >2M subs in 2024) and microwave replace fiber in niche last-mile/backhaul roles while fiber (100/400/800G commercial by 2024) dominates core capacity. Cloud bundles (AWS 31%/Azure 23%/GCP 11% 2024) and white-box growth (Dell'Oro 2024) pressure vendor sales; dark fiber market ~$2.4B (2024).
| Substitute | 2024 metric |
|---|---|
| Dark fiber | $2.4B |
| Cloud share | AWS31%/Azure23%/GCP11% |
| LEO | Starlink>2M subs |
Cutting-edge optics and coherent DSPs require heavy upfront investment—development programs commonly exceed $100 million—while lack of scale makes unit economics uncompetitive; long certification and interoperability cycles, often 12–24 months, further delay revenue realization, creating high barriers that deter most greenfield entrants from challenging incumbents like Ciena.
Top operators demand proven reliability, references, regulatory and interoperability compliance, often specifying carrier-class five-nines (99.999%) availability. New entrants must pass extensive lab testing and multi-vendor field trials that typically run 6–18 months and build global support and OSS/BSS integrations. Established vendors’ installed bases create operational inertia and high switching costs. Winning anchor customers therefore remains a steep, capital- and time-intensive climb.
Patents, export controls and security certifications create high entry barriers for Ciena's market, forcing newcomers to navigate IP portfolios and restricted tech lists. Aligning to open standards while differentiating products is technically and commercially complex. Regulatory regimes vary widely—over 150 jurisdictions had data protection laws by 2024—so newcomers must absorb sizable legal and compliance costs.
Securing advanced foundry slots and coherent optics is a major barrier for new entrants: TSMC held ~54% foundry share in 2023, squeezing access to leading nodes, while Ciena reported ~$4.1B revenue in FY2024, underpinning incumbent scale advantages. Preferred pricing and allocation go to high-volume suppliers, component shortages and 20+ week optics lead times in 2024 amplify disadvantages, and strict carrier reliability standards further raise upfront costs.
Open systems and merchant silicon have lowered some entry hurdles, enabling ODM-based hardware and open software to seed niche plays; Ciena reported roughly 3.5 billion USD revenue in FY2024, underscoring the incumbents' scale advantage. Entrants often start with modules or specific software/protocol layers, capturing small pockets of demand. Scaling to Tier-1, carrier-grade breadth—multi-year contracts often exceeding 100 million USD and demanding 5-9s availability—remains a high barrier.
High CAPEX, 12-24 month certs, supply squeeze (~54% foundry share) deter entrants
High upfront R&D and manufacturing CAPEX, plus 12–24 month certification cycles, create steep barriers; Ciena reported ~$4.1B revenue in FY2024 and incumbents benefit from scale. Foundry concentration (TSMC ~54% 2023) and 20+ week optics lead times in 2024 restrict component access and raise costs. Regulatory, IP and carrier five‑9s reliability requirements further deter greenfield entrants.


