
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
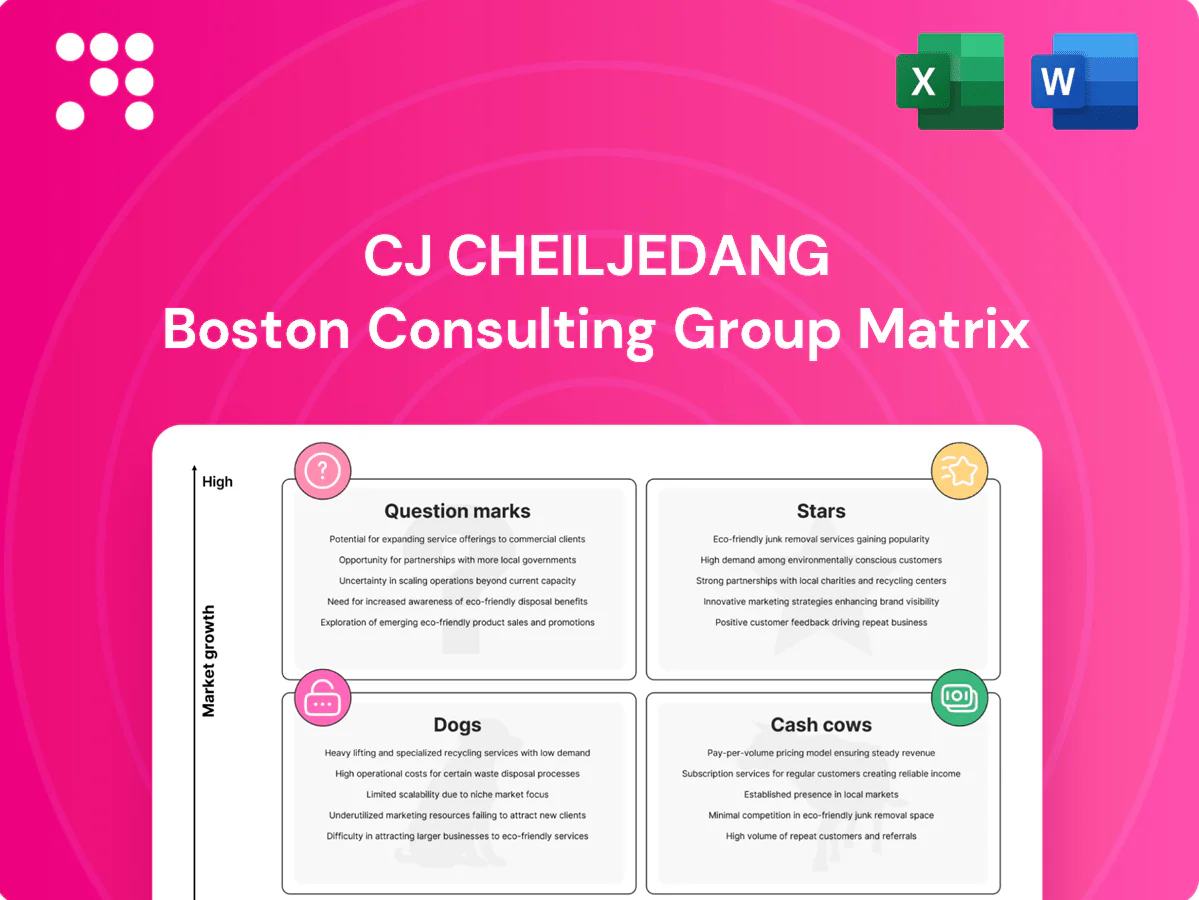
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
CJ CheilJedang’s BCG Matrix preview hints at which product lines are driving growth and which are weighing on margins — but it’s only the surface. Buy the full BCG Matrix for quadrant-by-quadrant placement, clear strategic moves, and an editable Word + Excel pack you can use in boardroom decisions. Skip the guesswork and get the clarity to act now.
Bibigo global frozen mandu is a Star: double-digit growth in 2024 and leading share in the US and Asian frozen dumpling categories, riding the Korean food wave. It dominates the category but requires heavy promotion, velocity pushes and new SKUs to stay hot. Cash in equals cash out for now, which matches the Star playbook. Keep investing to cement leadership and scale ahead of copycats.
US Asian convenient meals on the Schwan’s platform are a Star for CJ CheilJedang in 2024, leveraging Schwan’s national frozen-distribution reach to capture outsized share in a still-expanding frozen/convenience segment. Strong brand heat and distribution justify continued marketing and R&D spend, with returns keeping pace with investment. Prioritize reinvestment to scale penetration and transition this mature growth engine into a Cash Cow.
Savory taste solutions (nucleotides/yeast extracts) sit in Stars: clean-label umami is a clear growth pocket and CJ holds meaningful share with global F&B customers, serving blue-chip meat, snack and prepared-meal makers. Demand from reformulation and sodium-reduction initiatives keeps volume up-and-to-the-right—industry reports forecast ~5% CAGR for umami ingredients through 2028. Technical selling and capacity additions require upfront capex and working capital, consuming cash in the near term. Worth defending and extending via targeted R&D, COGS optimization and selective plant expansions to secure long-term margin leverage.
Rising protein consumption in emerging markets—global feed amino acids market valued at about USD 11 billion in 2023 with ~4.5% CAGR—keeps feed additives buoyant, and CJ CheilJedang ranks among top-tier suppliers of lysine and methionine by capacity and sales.
Scale and fermentation know-how translate to high share in feed segments, but CJ requires targeted capex and incremental working capital to chase demand spikes and avoid stockouts.
Maintaining price discipline and deep channel coverage is essential to preserve Star status amid margin volatility and cyclic demand.
Convenience continues to gain share in Korea/SEA and CJ CheilJedang retains category leadership in premium RTD/RTS bowls; 2024 channel data show continued double-digit growth in ready-meals. Trial-driving promos and quarterly new-flavor drops sustain unit momentum; marketing spend is sizable but supported by accelerating revenue per SKU in 2024. Stay aggressive until growth normalizes, targeting share expansion now.
Bibigo mandu, Schwan’s US frozen meals, savory umami solutions and feed amino acids are Stars in 2024: double-digit growth or high-single-digit CAGR, leading share positions, but net cash neutral due to heavy promo, R&D and capex. Continue aggressive reinvestment to cement scale and transition winners to Cash Cows.
| Business | 2024 metric | Action |
|---|---|---|
| Bibigo frozen mandu | Growth >10%, US category leader | Invest: promo/SKUs |
| Schwan’s frozen meals | Double-digit growth, national reach | Scale distribution |
| Umami ingredients | ~5% CAGR to 2028 | R&D + capacity |
| Feed amino acids | Market USD 11bn (2023), CAGR ~4.5% | Targeted capex |
 Detailed Word Document
Comprehensive BCG Matrix review of CJ Cheiljedang’s portfolio, detailing Stars, Cash Cows, Question Marks, Dogs and strategic moves.

 Customizable Excel Spreadsheet
One-page CJ Cheiljedang BCG Matrix placing each business unit in a quadrant to clarify priorities and cut reporting friction.
Hetbahn instant rice is the category leader in Korea’s mature instant-rice segment, delivering sticky repeat purchase behavior with low incremental marketing and high throughput that yields dependable margins. It consistently generates cash flow that CJ CheilJedang uses to fund higher-risk, growth-oriented plays. Priority actions: maintain product quality, optimize plant efficiency and supply chain, and milk the brand responsibly to sustain returns.
Beksul sugar and flour sit in stable, low-growth pantry categories where CJ leverages scale and nationwide shelf presence to lead price and distribution rather than mass advertising; the SKUs act as steady cash generators with modest capex needs. Margin resilience comes from procurement and logistics efficiency, so the playbook is cost-squeeze, protect share, and keep the business boring and profitable.
Dashida core seasonings reach household penetration of over 80% in South Korea, delivering low-single-digit category growth (~3% CAGR) off a very wide base. Brand equity keeps promotional spend efficient, supporting a marketing ROI above typical benchmarks. The product line posts solid margins (around 18% EBITDA) and steady cash flow, while incremental innovation and an emphasis on distribution economics—covering roughly 200,000 retail points—drive incremental sales.
Domestic frozen dumplings (Korea) sit in the cash-cow quadrant: the category has matured with low single-digit annual growth, while CJ CheilJedang retains the market-leading share per company disclosures (2024), allowing marketing to be maintenance-focused rather than aggressive share acquisition.
High line efficiency delivers healthy gross and operating margins, converting steady cash flow into surplus capital that CJ redeploys to fund expansion and innovation in new categories abroad.
Animal feed operations sit as cash cows: mature and competitive, yet CJ’s scale, long-term supply contracts and integrated livestock feed chain deliver steady volume and free cash. Market growth is low (2024 est. ~2–3%), with cadence volatility manageable at scale. Operational excellence — formulation, logistics and tight working capital — outperforms branding to keep cash churning.
Hetbahn, Beksul, Dashida and frozen dumplings are CJ CheilJedang cash cows: mature categories with low-single-digit growth (2024) delivering steady free cash to fund expansion. Dashida posts ~18% EBITDA (2024); animal feed grows ~2–3% (2024). Priority: maintain quality, optimize operations, milk for reinvestment.
| Business | 2024 growth | Share | EBITDA |
|---|---|---|---|
| Hetbahn | low-single-digit | leader | — |
| Dashida | ~3% CAGR | 80%+ pen. | ~18% |
| Feed | 2–3% | scale | — |
The CJ CheilJedang BCG Matrix you're previewing is the exact same polished file you'll receive after purchase. No watermarks, no demo placeholders—just a ready-to-use strategic report focused on product portfolio and market positioning. Designed for clarity and immediate use, it’s editable, printable, and presentation-ready. Buy once and download the final document straight to your inbox.
Legacy bulk sugar exports sit in a low-growth segment with price-taker dynamics and limited product differentiation, constraining pricing power and margin recovery.
Working capital and logistics cash is tied up while returns lag core business ROIC, making structural margin restoration difficult without market shifts.
Strategic options include pruning volumes, reallocating capacity, or exiting persistently unprofitable lanes to free cash and improve portfolio returns.
Commodity flour for overserved foodservice faces saturated channels and razor-thin spreads (industry gross margins ~2–3%), with suppliers easily swapped and Black Sea/US wheat averaging roughly USD 300/ton in 2024; market share is patchy and hard to defend, so turnarounds often burn capital (incremental CAPEX/working capital hits often in the KRW 10–20bn range) with little upside; shrink to core SKUs or divest.
Generic MSG and undifferentiated flavor bases sit in a stagnant category with near‑zero growth in major markets in 2023–24 and aggressive low‑cost competition, especially from China and regional producers. Without proprietary IP or branded differentiation, premiumization is limited and margin compression can push returns to break‑even or turn the portfolio into a cash trap. Recommend aggressive SKU rationalization and redeploy capital to higher‑growth, higher‑margin segments.
Small, non-core regional SKUs function as Dogs: in 2024 they consumed shelf space and inventory carrying costs while contributing negligible market share and no measurable brand uplift, rarely covering the complexity tax of segmented production and distribution. Operational reviews show these SKUs inflate working capital and exceed marginal gross margins versus core items, so pruning tail SKUs improves fill rates and reduces logistics overhead. Cut the tail, keep the head.
Underperforming private-label contracts leave CJ CheilJedang with high volumes but razor margins; switching costs for retailers are low so buyers squeeze price and leverage alternatives. Cash drips out slowly as working capital and dedicated capacity stay locked, eroding return on invested capital. Exit or reprice to clear hurdle rates quickly.
Legacy bulk sugar, commodity flour and generic MSG behave as Dogs: low growth, weak pricing power and margin compression (commodity flour industry gross margins ~2–3%; Black Sea/US wheat ~USD 300/ton in 2024). Working capital and logistics lock cash (incremental CAPEX/WC hits often KRW 10–20bn), returns trail core ROIC. Prune or exit tail SKUs and reprice/terminate low‑margin private‑label contracts.
| Category | 2024 datum | Implication |
|---|---|---|
| Commodity flour | Wheat ~USD 300/ton; margins ~2–3% | Low margin, consider shrink/divest |
| MSG | Growth ~0% (2023–24) | Premiumization limited |
| Tail SKUs | WC/CAPEX KRW 10–20bn (incremental) | Delist to free cash |
PHA bioplastics sit in a high-growth sustainability space but CJ’s commercial share is still emerging; global bioplastics production capacity was about 2.4 million tonnes in 2023, with PHA representing a small subset. Capex-heavy plants and long specification and procurement cycles mean cash outflow precedes profit. With successful scale-up and customer lock-in it can flip to Star. Worth a targeted, disciplined push.
Category growth is real—global plant-based foods continue expanding at roughly a 10%+ CAGR into 2024, but the channel is crowded and volatile with fast product churn. CJ has brand permission in Korean and ethnic niches but holds single-digit share outside specialty aisles, limiting scale. Success requires bolder product-market fit and sharper price-pack architecture; invest selectively with clear ROI thresholds or pivot quickly.
Question mark: Functional nutrition (amino acid blends, wellness) — health positioning is rising as the global dietary supplements market reached about USD 170 billion in 2024, yet CJ’s consumer-brand footprint remains early-stage internationally. Technical credibility is strong from CJ’s biotech and amino-acid expertise, but marketing moats are weak; scale via partnerships and DTC is viable. Test-and-learn, then double down where repeat purchase is proven.
Cross-border DTC for Korean pantry sits as a Question Mark: global e-commerce hit $5.7T in 2023 and cross-border volumes are ~20%, so discovery is strong but acquisition costs bite and share remains small without owned communities; freshness and cold-chain add logistics complexity; pilot in 2–3 focus markets, build loyal cohorts, then scale.
Precision-fermented bio-actives sit in Question Marks: market growth is attractive — industry estimates show ~41% CAGR 2024–2030 (Grand View Research) — but regulatory and commercialization timelines remain uncertain, keeping current share low and R&D burn high. Upside is large if a hero molecule secures sticky B2B contracts; recommend stage-gating spend and co-developing with anchor customers.
Question marks: PHA bioplastics—high-growth sustainability niche (global capacity ~2.4M t in 2023) but CJ share nascent; heavy capex, scale needed to become Star. Functional nutrition—global supplements ~USD170B (2024); CJ has tech but weak consumer moat; test DTC/partnerships. Precision-fermentation—~41% CAGR (2024–30); high R&D, stage-gate with anchor customers.
| Segment | 2023/24 Metric | CJ Status | Recommendation |
|---|---|---|---|
| PHA bioplastics | 2.4M t cap (2023) | Nascent | Targeted scale-up |
| Functional nutrition | USD170B market (2024) | Tech strong, brand weak | Partner + DTC tests |
| Precision fermentation | ~41% CAGR 2024–30 | Low share, high R&D | Stage-gate, co-dev |


