
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
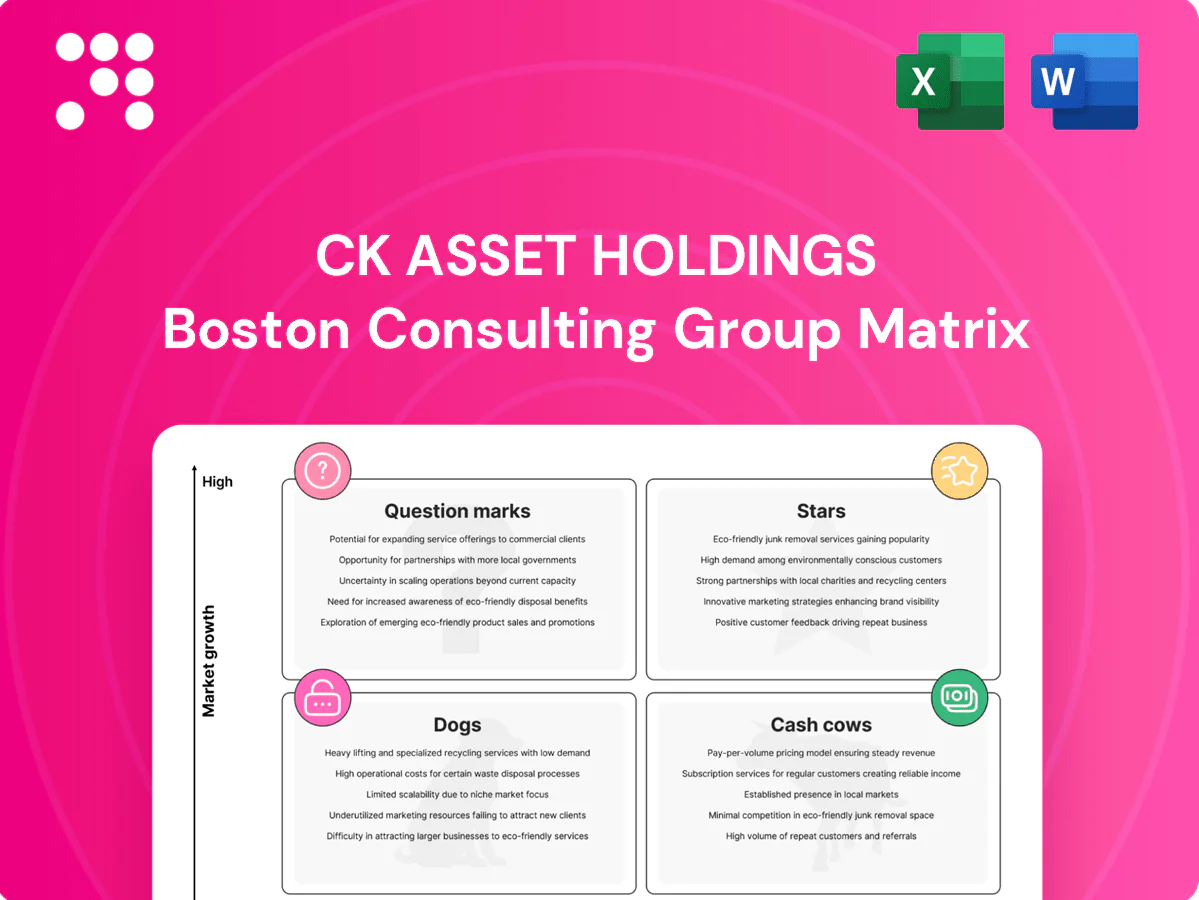
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where CK Asset Holdings’ businesses fall—Stars, Cash Cows, Dogs or Question Marks? This preview scratches the surface; buy the full BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and clear strategic next steps. Get instant access in Word + Excel and stop guessing—plan where to invest, divest, or defend with confidence.
CK Asset’s HK premium residential launches in 2024 recorded sell-through rates above 70% in the first month and headline gross margins near 30%, underpinning their classification as Stars in the BCG matrix.
The group holds a leading share of the Hong Kong primary market by value (circa 15%) and strong brand pull, yet continues heavy spend on marketing and placements to sustain rapid absorption.
At this growth clip cash in equals cash out as sales proceeds fund land and capex, so ongoing investment is required to lock the pipeline and defend price leadership.
Mainland tier‑1 mixed‑use Stars cluster around Shanghai (population ~24.9m) and Shenzhen (~17.6m), where placemaking near transit keeps demand and market share high. They require large pre‑sale engines and rigorous on‑the‑ground execution, with working capital burned quickly as inventory turns fast. Nurture them now; once the cycle cools these assets can become stable cash cows.
Core CBD offices and prime retail assets are flagship investments for CK Asset, recording near-full occupancy and strong rental reversion in 2024 amid a recovering Hong Kong market. Market share and public visibility remain high, though ongoing capex and tenant incentives are material to sustain tenancy. Active promotion and branded events continue to drive footfall; strategy: hold and pursue selective upgrades to cement leadership.
UK/Europe build‑to‑rent benefits from structural rental demand—private rented sector is about 20% of UK households (ONS)—and strong institutional capital interest, with pension and insurance allocations growing. CK’s scale allows sourcing land, development and operating synergies, though upfront capex for operating setup and leasing is required; unit economics improve as portfolio density rises, so double down while consolidation continues.
Hospitality in gateway cities is a Star for CK Asset: RevPAR rose c.70% y/y and ADR c.40% in 2023–24 across core markets, helping CK’s centrally located assets punch above their weight. Brand marketing and refurb cycles consume cash in this growth phase, and pipeline additions need careful pacing. Invest through the upswing to capture share before rates normalize.
CK Asset Stars: HK premium launches 2024 sell-through >70% month-one, headline gross margin ~30% and c.15% market share, driving rapid cash recycling. Mainland tier‑1 mixed‑use (Shanghai pop 24.9m; Shenzhen 17.6m) show high absorption but burn working capital. UK BTR benefits from PRS ~20% of households; unit economics improve with scale. Hospitality RevPAR +70% y/y, ADR +40% (2023–24).
| Asset | Key metric | 2024 |
|---|---|---|
| HK residential | Sell-through / margin | >70% / ~30% |
| Mainland mixed-use | Market cities | Shanghai 24.9m; Shenzhen 17.6m |
| Hospitality | RevPAR / ADR | +70% / +40% |
 Detailed Word Document
Maps CK Asset units into Stars, Cash Cows, Question Marks and Dogs with investment guidance, risks and trend context.

 Customizable Excel Spreadsheet
One-page CK Asset BCG matrix placing each business unit in a quadrant for fast portfolio clarity.
Stabilized HK investment properties form CK Asset’s cash cows: mature office towers and retail malls with entrenched tenants delivering predictable cash flow in 2024. Low growth but high market share sustains steady margins; management minimizes promotion spending and focuses on operational efficiency and lease-mix optimization. These assets are milked to fund new development pipelines and tech investments.
Property & project management services are fee-based and asset-light, delivering sticky contracts and predictable cash flow; in 2024 the segment showed modest growth with low churn. Margins benefit from scale and cross-sell across CK Asset’s portfolio, improving operating leverage. Focus for optimization: upgrade systems, digitize workflows and expand wallet share per site to lift ancillary revenue and EBITDA per asset.
Infrastructure and utility stakes in CK Asset act as defensive cash cows, delivering inflation-linked, predictable cash yields with low ongoing capex once assets are stabilized; payouts are reliable and support group distributions. These holdings are not high-growth but sustainably fund development and investment across the portfolio. Maintain asset condition, refinance opportunistically, and prioritize dividend harvest to maximize shareholder returns.
Long‑lease logistics/industrial parks form cash cows for CK Asset, with high occupancy in 2024, covenant‑strong tenants and steady contractual escalators delivering predictable rental income and strong cash conversion.
Market growth in 2024 was moderate while CK Asset’s share in prime logistics stock remains solid, requiring limited promotional spend; targeted incremental capex enhances NOI and cash flow per asset.
Legacy hotels within CK Asset deliver stable occupancy—Hong Kong hotel occupancy averaged 74% in 2023 (Hong Kong Tourism Board)—driven by repeat corporate and airline contracts; growth is flat but cash generation is clean, enabling tight opex control and targeted room refreshes to maintain yield.
Stabilized HK investment properties, fee‑based property services, infrastructure stakes, logistics parks and legacy hotels act as CK Asset cash cows in 2024, delivering predictable cash flow, high occupancy and low promotion spend; surplus funds development pipelines and tech investments.
| Asset | Characteristic | Note |
|---|---|---|
| HK investment props | Predictable rents | 2024 steady cash flow |
| Property services | Fee-based, sticky | Low churn |
| Infrastructure | Inflation-linked yields | Defensive |
| Hotels | Stable occupancy | HK 74% (2023) |
The file you’re previewing is the exact CK Asset Holdings BCG Matrix report you’ll receive after purchase — no watermarks, no demo text, just the finished, professionally formatted analysis. It’s crafted for clarity and decision-making, ready to edit, print, or present. Buy once and download immediately; what you see is what you get, no surprises.
Small China tier-3 residential projects in CK Asset’s BCG Dogs bucket show low absorption (often under 10%), heavy discounting pressure and limited brand lift, leaving growth stagnant and market share thin (typically below 5%). Cash is tied up in slow-moving inventory, increasing holding costs and liquidity strain. Prioritize exits or bundle these assets for divestment to free capital and cut carrying losses.
Underperforming fringe retail assets face persistent headwinds as e‑commerce growth and weak local catchment reduce footfall and tenant sales, forcing discounting and higher vacancy. Turnaround plans demand significant capex for reconfiguration and leasing incentives yet typically yield only marginal rental uplift and prolonged payback. These assets often merely reach cash break-even under current demand patterns. Strategic disposal or repurposing to residential, logistics, or mixed‑use is the pragmatic option.
Aging industrial blocks in CK Asset’s portfolio have obsolete specs, high vacancy (often exceeding 20% in older stock) and retrofit costs that can reach HKD 5,000–8,000 per sqm, eroding yields. Market demand has shifted to modern logistics/last-mile facilities with higher rents and lower downtime. Projected returns on solo refurbishments frequently fail to clear common developer hurdles (~8%–10%). Recommend sell or JV for redevelopment rather than sinking solo capital.
Non‑strategic minority investments at CK Asset are thinly held positions with limited control, often carrying minimal information rights and generating little operational synergy, tying up balance sheet liquidity for negligible strategic impact in 2024.
These stakes are hard to scale or influence, typically representing a small single‑digit percent of non‑core investment value, and management focuses on pruning underperformers and recycling proceeds into core property and infrastructure assets.
Active disposal and redeployment in 2024 prioritized capital efficiency, improving return on equity and liquidity metrics while reducing distraction from core development and asset management operations.
Over-supplied resort hotels face steep seasonality and pricing wars that compress margins, with heavy discounting turning marketing spend into short-term occupancy gains rather than durable market share; cash generation is intermittent, often a dribble rather than steady flow.
Strategic options include exit or conversion to alternative lodging formats—serviced apartments, long-stay units, or MICE-focused properties—to stabilize revenue and improve asset utilization.
CK Asset Dogs: low‑absorption China tier‑3 housing (<10% sales), fringe retail vacancy 15–25% and heavy discounting (10–20%), industrial older stock vacancy >20% with retrofit ~HKD 5,000–8,000/sqm, non‑core stakes single‑digit value. Recommend prioritized disposals, JV redevelopments or conversion to residential/logistics to free capital and improve ROE in 2024.
| Asset | Key metric (2024) | Typical loss/Cost | Action |
|---|---|---|---|
| Tier‑3 housing | Absorption <10% | Deep discounts 10–20% | Sell/bundle |
| Fringe retail | Vacancy 15–25% | Lower rents | Dispose/repurpose |
| Old industrial | Vacancy >20% | Retrofit HKD5k–8k/sqm | JV/redevelop |
| Non‑core stakes | Single‑digit value% | Low yield | Prune/recycle |
Explosive demand: hyperscaler capex topped US$200bn in 2023 and stayed elevated into 2024, but CK’s share is nascent and build costs (~US$8–12m per MW) make the roll‑out capital‑intensive. Siting, grid access and JV structure are make‑or‑break due to land and power constraints in core markets. With the right partners CK could scale into a star rapidly; otherwise pass decisively to avoid value dilution.
Renewable‑linked utility platforms sit in the Question Marks quadrant: policy tailwinds from China’s 2060 neutrality pledge and Hong Kong’s 2050 net‑zero target boost demand, but entry points remain fragmented across markets and technologies. Returns will hinge on offtake quality and build costs, so low early footprint and market share mean outcomes are binary. CK Asset must pick a lane, secure long‑dated PPAs and scale rapidly or exit to avoid sunk costs.
Overseas residential targets attractive demographics: UN estimates 56.2% of the world population lived in urban areas in 2024, and fast-growing cities such as Ho Chi Minh City (≈9.2m residents in 2024) offer long-term demand tailwinds.
However, unfamiliar local cycles make sales velocity uncertain and brand still building, forcing high initial marketing burn and slower sell-through versus home markets.
Strategically, CK Asset should concentrate resources deep in 1–2 cities to achieve scale and brand recognition or else pull back to limit marketing and holding-cost exposure.
Co‑living and extended‑stay sit as Question Marks for CK Asset in 2024: urban demand is rising (Hong Kong population ~7.4m, global urban residents >4.5bn in 2024), but operations are complex at scale and CK’s current share is small; success requires technology platforms, community programming, and localized operations to stabilize returns. Pilot to prove unit economics, then roll or shut.
Smart-building/proptech ventures are Question Marks for CK Asset: global smart-building market ~USD 100bn in 2024 with ~12% CAGR to 2029, and tech can deliver 20–30% energy/OPEX reductions, but current deployments are scattered with vendor concentration risk and low share of wallet in the group; if pilot ROI clears, accelerate portfolio-wide embedment, otherwise halt tinkering and reallocate capex.
Question Marks: high market tailwinds but small CK share and binary outcomes. Hyperscaler capex >US$200bn (2023) with build costs ~US$8–12m/MW; renewables benefit from China 2060/HK 2050 targets; smart‑building market ~US$100bn (2024, ~12% CAGR) and urbanization ~56.2% (2024). Pilot, secure long PPAs/partners, scale fast or exit to avoid dilution.
| Segment | 2024 metric | Key risk | Play |
|---|---|---|---|
| Data centres | Hyperscaler capex >US$200bn | Capex intensity | JV + long‑term contracts |
| Renewables | Policy tailwinds (2060/2050) | Offtake/build cost | Pick lane + PPAs |
| Proptech/co‑living | Smart market US$100bn | Ops scale | Pilot → scale/exit |


