
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
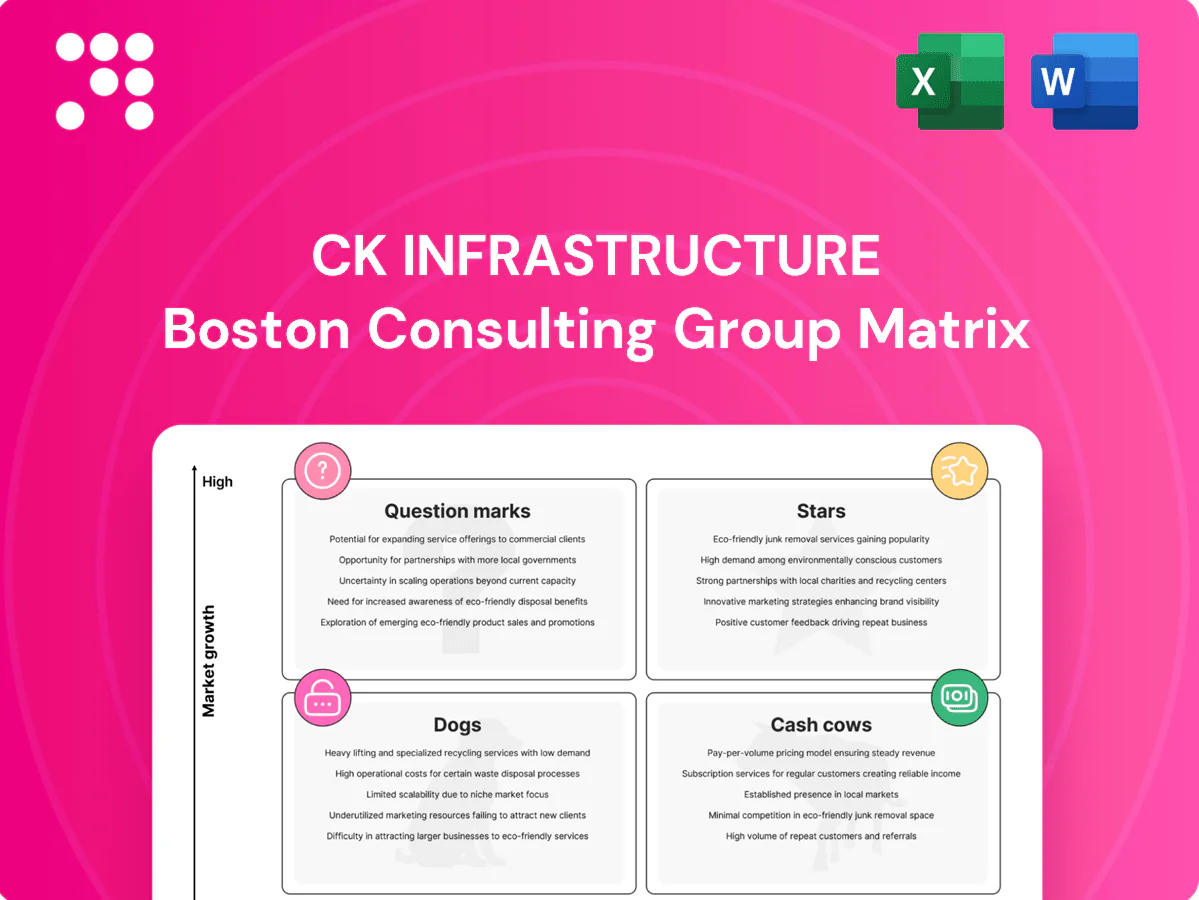
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick snapshot: CK Infrastructure’s BCG Matrix paints a picture of solid cash cows in core utilities and a few question marks in new energy ventures—high cash flow, selective growth needs. Want clarity on which assets to milk, which to divest, and where to double down? Purchase the full BCG Matrix for quadrant-by-quadrant placement, actionable strategy, and a ready-to-use Word report plus Excel summary. Skip the guesswork—get the data-backed roadmap to steer capital and priorities with confidence.
High market share in the fast-growing waste-to-energy decarbonization niche benefits from 2024 tailwinds as the global WtE market is expanding at roughly a 6% CAGR and assets typically run 85–90% utilization under long-term feedstock contracts. Expansion requires cash, but CK Infrastructure’s pipeline and secured contracts justify staying on offense. Hold share now; assets should mature into strong cash generators later.
Gas distribution in growth regions remains strong as population and industrial demand accelerated through 2024, keeping networks utilization high. CKI’s scale and regulated frameworks lock in predictable returns while ongoing capex expands the asset base and muddies marginal risk. Promotion focuses on stakeholder trust and targeted grid upgrades rather than mass advertising. Continued investment is warranted to cement leadership before growth normalizes.
First-mover sites and long‑dated PPAs give CK Infrastructure volume in fast‑growing markets, with project pipelines in 2024 totaling multiple GW of contracted capacity and near‑term CODs underpinned by secured offtake. Interconnection rights and local operational know‑how form tangible moats that raise barriers to entry and protect returns. Build‑out remains capital intensive, but 2024 earnings momentum from contracted renewables and merchant exposure is strengthening cash flow. Hold the throttle on new builds and defend offtake to convert scale into steady cash cows later.
Traffic on CKI smart toll corridors has rebounded above pre‑shock ADT, with volumes rising an estimated 15% year‑on‑year in 2024 on key regional routes driven by GDP and mobility recovery.
Dynamic pricing and digital tolling lift yield and generate first‑party traffic/data — boosting toll revenue per vehicle and enabling targeted demand management while improving loss detection.
Ongoing expansion and O&M digitization require capital deployment now; focus on maintenance excellence and superior customer UX to protect market share and lifetime revenue.
Advanced water treatment hubs sit in Stars: urban growth and stricter effluent standards in 2024 make advanced tertiary treatment essential, driving high-capex tenders. CKI’s operating depth wins large tenders and secures long concessions (typically 20–30 years), converting growth into durable cashflows. Scale lets CKI upgrade membranes and controls faster than rivals, preserving margin and market share.
Stars: WtE, gas distribution, renewables, tolls and advanced water are high-share, high-growth assets; WtE ~6% CAGR (2024) with 85–90% utilization. CKI had ~3.5 GW contracted renewables pipeline (2024) and toll ADT +15% YoY (2024). Concessions often 20–30 years, requiring capex now to secure long-term cashflow.
| Asset | 2024 metric | Key note |
|---|---|---|
| WtE | CAGR 6% / 85–90% util | feedstock contracts |
| Renewables | 3.5 GW contracted | long PPAs |
| Tolls | ADT +15% YoY | dynamic pricing |
| Water | Concessions 20–30 yrs | tech refresh |
 Detailed Word Document
BCG analysis of CK Infrastructure's units, classifying Stars, Cash Cows, Question Marks and Dogs with clear invest/hold/divest guidance.

 Customizable Excel Spreadsheet
One-page CK Infrastructure BCG Matrix that clarifies portfolio weak spots and prioritizes capital allocation for faster decisions.
Mature regulated electricity distribution represents a stable, high-share cash cow for CK Infrastructure, operating in slow-growth territories with predictable allowed returns and low customer churn; low promotional spend and steady inflation pass-through preserve margins. Incremental capex on reliability and digitization improves cash conversion. Milk prudently while maintaining strong regulator relationships in 2024.
Established water utilities are an essential service with an entrenched footprint and modest demand growth of roughly 1% annually in developed markets; regulated returns typically sit around 4–6%, so operating levers and leakage control drop straight to cash. Minimal marketing is required—focus stays on compliance and service KPIs such as leakage reduction and supply continuity. Surplus cash funds the next wave of growth bets and de-risked capex.
Core toll roads and legacy bridges in CK Infrastructure sit on long-dated concessions (typically 30+ years) with mature traffic patterns and stable tariff regimes, where maintenance outweighs expansion and cost discipline drives returns. High EBITDA margins and limited competitive threats give predictable cash outflows and unexciting but reliable inflows, supporting steady dividend coverage and balance-sheet resilience.
Gas networks in saturated markets show household gas penetration above 80% in developed markets (2024), producing slow customer growth but stable volumes; clear regulatory frameworks deliver predictable returns. Efficiency programs and roll-out of smart meters have compressed operating costs and widened margins, requiring minimal marketing as reliability is the core brand, allowing networks to throw off cash to fund higher-growth platforms.
Contracted baseload generation in CK Infrastructure functions as a cash cow: in 2024 over 90% of plant output remains covered by PPAs that lock pricing and volume, leaving growth minimal while protecting revenue visibility.
O&M optimization and active fuel hedging sustained thick margins in 2024, with limited capex required beyond regulatory compliance.
This fleet is a clean, steady contributor to dividends and debt service.
Mature regulated networks, contracted baseload and core tolls are stable cash cows for CK Infrastructure in 2024, yielding predictable cashflow with regulated returns of ~4–8% and PPA coverage >90%. Low growth, minimal capex beyond compliance, and high EBITDA margins support dividends and debt service while funding selective growth.
| Asset | 2024 metric | Role |
|---|---|---|
| Electricity/water | Returns 4–6% | Cash generator |
| Toll roads | Concessions 30+ yrs | Stable cash |
| Baseload | PPA >90% | Revenue visibility |
The CK Infrastructure BCG Matrix you're previewing is the exact, final file you'll receive after purchase. No watermarks or demo placeholders—just a fully formatted, ready-to-use strategic matrix tailored to CK Infrastructure's portfolio. It arrives immediately for editing, printing, or presenting. Crafted for clarity and decision-making, there are no surprises—only actionable insight.
Merchant fossil generation (uncontracted) sits in low-growth, high-volatility territory: renewables reached about 30% of global power generation by 2024 (IEA), shrinking market share for uncontracted thermal plants. Cash flows swing with spot prices, offering limited upside without major reinvestment; turnarounds are costly and slow, often taking years. This is prime trim-or-exit territory for CK Infrastructure’s merchant fossil exposure.
Small, non-core concessions in fragmented markets show thin scale and weak bargaining power, creating administrative drag that ties up teams and capex for marginal returns; growth is muted (low single-digit volume/price expansion) and competitors crowd the space. Consider strategic bundling for sale to realize value and cut operating overheads.
Demographic shifts and new bypass openings have bled volume on mature toll concessions, with case studies showing traffic declines of 10–20% post-bypass in comparable markets. Tariff hikes face elasticities that prevent full pass-through to revenue, typically recovering only a portion of lost volume. Heavy capex cannot regenerate underlying demand trends; ROI often falls below concession WACC. Hold-to-runoff or divest while residual value remains preferable.
Legacy coal-adjacent infrastructure sits squarely in Dogs: policy and ESG headwinds in 2024 tightened, with over 100 global banks enforcing coal restrictions, capping growth prospects and valuation upside. Maintenance costs are rising while utilization drifts lower, squeezing margins; refinancing is costly as corporate yields hover above 4–5% in 2024. Strategic wind-down and decommissioning plans outperform attempts at operational turnarounds.
Overcapacity in CK Infrastructure’s waste transfer sites has created a Dogs profile: local competition and flat volumes compress margins, while high fixed costs trap cash with minimal organic growth. Expansion projects have weak IRRs and do not pencil under current volume forecasts, making further investment unattractive. The strategic priority is to rationalize the footprint and redeploy capital into higher-return assets.
Merchant fossil and legacy coal assets face low growth and volatile cash flows as renewables hit ~30% of global power generation in 2024 (IEA); over 100 banks imposed coal limits in 2024, raising refinancing costs. Small concessions and waste sites show flat volumes and thin margins; toll concessions see 10–20% traffic declines after bypasses. Priority: divest, rationalize footprint, redeploy capital.
| Asset | Issue | 2024 metric | Action |
|---|---|---|---|
| Merchant fossil | Spot volatility | Renewables ~30% | Exit/divest |
| Coal-adjacent | ESG/financing | >100 banks coal limits | Wind-down |
| Tolls | Demand loss | Traffic -10–20% | Sell/hold-runoff |
| Waste sites | Overcapacity | Flat volumes | Rationalize |
Battery storage co‑located with renewables sits in a rapidly expanding market—global battery storage market value reached about USD 17.2bn in 2024—yet CKI’s current share remains small relative to peers. Revenue‑stacking rules and merchant volatility mean returns can wobble and IRRs vary project‑to‑project. With scale and superior control tech CKI could convert this Question Mark into a Star; if not, cut exposure fast.
Hydrogen-ready gas network pilots sit in the Question Marks quadrant: high-growth narrative with over 30 pilots worldwide by 2024 and many trials targeting up to 20% H2 blending, but standards and long-term demand remain early-stage. Capex is heavy and payback is uncertain without clear policy lifts and blending mandates. Strategic fit for CK Infrastructure is strong if blending volumes scale; decision should follow pilot KPI results.
Smart water analytics market ~USD 1.9bn in 2024 with ~14% CAGR; utility adoption is accelerating but the vendor field remains fragmented. CKI is piloting solutions across holdings rather than leading deployments yet. Cross-selling into CKI-owned UK, Aus and Hong Kong utilities could capture share given industry non-revenue water losses of ~20–30%. Invest to secure a beachhead or partner out to scale faster.
Advanced recycling and circular waste projects sit as Question Marks for CK Infrastructure: regulatory push is real (EU and many APAC EPR rules tightened in 2024) but economics are still maturing against global plastic waste of ~400 million tonnes/year. Technology risk and feedstock variability bite, yet early wins (pilot scale 1–10 ktpa) can anchor regional leadership; go big on one or two, pause the rest.
EV charging integrated with toll and service areas sits in Question Marks: usage is ramping as public EV fleet grows and site control is an edge, but competition is fierce and capex per DCFC site ranges roughly 150,000–500,000 USD; utilization curves typically take 12–36 months to mature. If CKI leverages traffic data and bundles retail, parking and advertising, roll-out can scale faster via digital targeting and revenue stacking.
Question Marks: battery storage (global USD 17.2bn in 2024) and hydrogen pilots (30+ by 2024) sit in high-growth but low-share positions; smart water (USD 1.9bn, ~14% CAGR) and advanced recycling (400 Mt/yr waste) face tech/policy risk; EV charging capex USD 150–500k per DCFC and 12–36m ramp. Prioritise 1–2 scale pilots, partner or divest rest.
| Segment | 2024 stat | Risk | Action |
|---|---|---|---|
| Battery | USD 17.2bn | merchant volatility | scale tech |
| H2 gas | 30+ pilots | policy/standards | pilot KPIs |
| Water | USD 1.9bn | fragmented vendors | cross-sell |
| Recycling | 400 Mt/yr | tech/feedstock | focus 1–2 |
| EV | USD 150–500k/site | competition | pilot clusters |


