
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
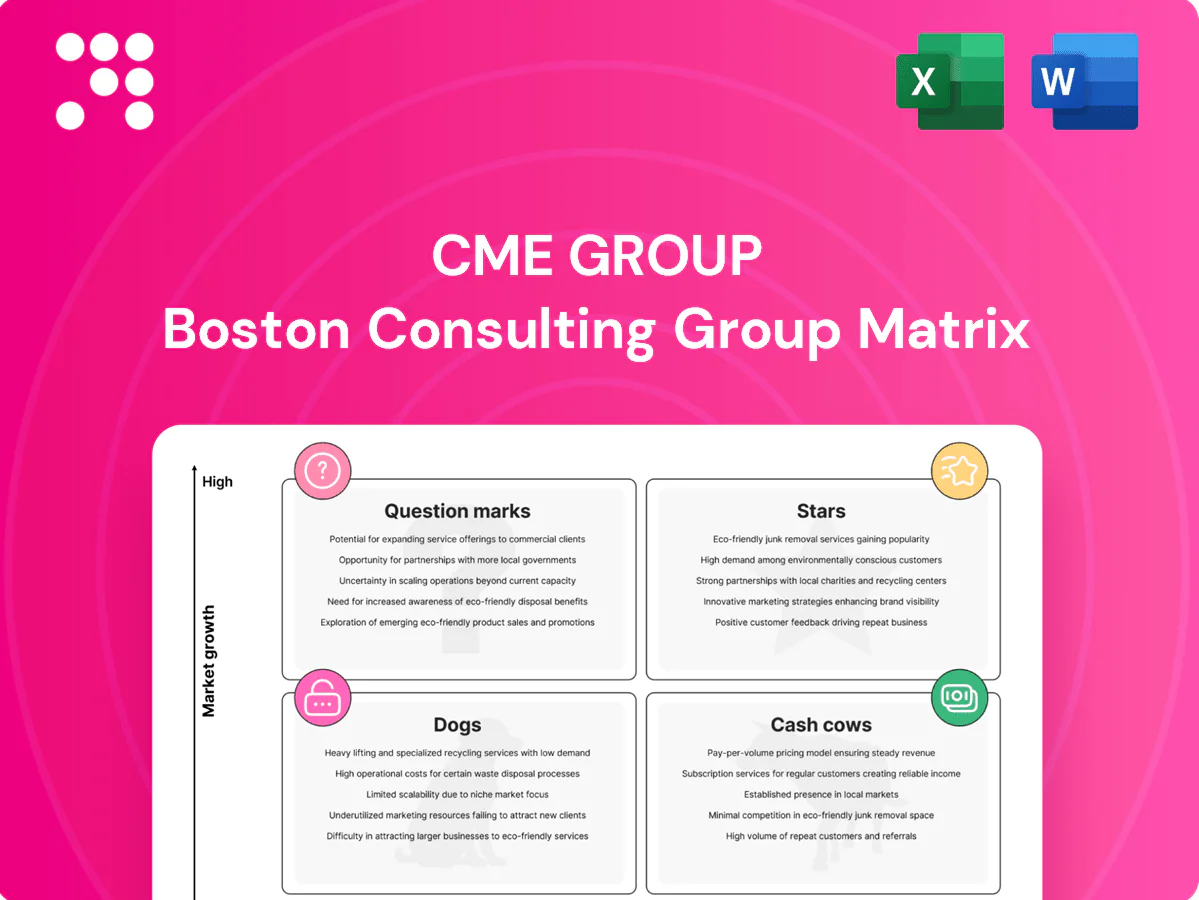
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where CME Group’s products sit—market leaders, cash generators, or underperformers? This snapshot teases the quadrant logic; the full BCG Matrix gives you the quadrant-by-quadrant placements, data-backed recommendations, and clear strategic moves. Buy the complete report for a ready-to-use Word analysis and an Excel summary that lets you present, prioritize capital, and act fast. Skip the guesswork—purchase now for instant, actionable clarity.
Runaway adoption and rate volatility have kept SOFR and U.S. Treasury futures/options as CME’s hottest engine in 2024, with SOFR supplanting Eurodollars as the dominant USD short‑term benchmark. CME effectively owns the on‑exchange rates complex, supplying the primary execution, clearing and liquidity hubs. The franchise still consumes cash for product upgrades and liquidity programs but returns it through robust volume growth. Continue funding liquidity initiatives and education to maintain flagship status.
Launched in May 2019, the Micro E-mini suite offers one-tenth the notional of standard E-minis, giving retail and smaller institutions an accessible S&P, Nasdaq and Russell exposure. Volatility spikes historically drive onboarding of new users, while listed options and growing liquidity deepen the micro ecosystem. It already leads adoption but needs sustained promotion and market-maker incentives to scale globally. Hold share; it can graduate into a dominant Cash Cow.
Cross-asset options on futures saw options ADV climb in 2024 to roughly 22.7 million contracts as hedgers and vol funds increased activity across rates, equity, energy and ags. CME’s clearing netting, portfolio margin and deep liquidity pools provide a structural edge, lowering capital and execution costs. Options liquidity is earned daily—quote support, analytics and market-making matter. Continued investment in tools and multi-leg spreads is essential; the growth runway remains long.
Macroeconomic shocks and OPEC headlines make optionality the point of the spear for WTI options and spreads, and CME Group (NYMEX/WTI) remains the dominant venue for the crude vol surface as of 2024 H1.
Nurturing deep wings and complex calendar/strip spreads requires ongoing liquidity provisioning and tight market-maker programs; CME reported strong dealer participation through dedicated liquidity rebates in 2024.
Widening the bench of users — hedgers, funds, systematic vol sellers/buyers — keeps wings tradable and spreads executable in stressed markets.
COMEX metals during macro cycles: gold and copper reclaimed focus in 2024 as inflation, geopolitics and electrification drove demand; gold futures rallied and copper hit multi-year highs, pushing liquidity into CME contracts. Liquidity concentrates when narratives heat up, and CME’s contracts sit at the centre of price discovery. Surges required active liquidity provision and analytics to keep bid-ask spreads tight. After cooling, traded base volumes remained larger than pre-surge levels.
SOFR/Treasury futures, Micro E‑minis and options on futures are Stars in 2024: SOFR ADV surged to ~1.9M contracts/day, Micro E‑mini ADV ~0.6M, options ADV ~22.7M, all showing double‑digit volume CAGR and high market share on‑exchange; continued investment in liquidity programs and tech is priority.
| Product | 2024 ADV | YoY vol CAGR |
|---|---|---|
| SOFR/Treasury | 1.9M | +24% |
| Micro E‑mini | 0.6M | +18% |
| Options on futures | 22.7M | +15% |
 Detailed Word Document
BCG Matrix review of CME Group products: Stars, Cash Cows, Question Marks, Dogs with investment, hold, divest guidance.

 Customizable Excel Spreadsheet
One-page CME Group BCG Matrix placing each business unit in a quadrant to clarify priorities and eliminate reporting noise.
Massive, mature, and relentlessly traded, E-mini S&P 500 futures averaged about 3 million contracts/day in 2024 and remain the rent payer for CME Group. Market share is entrenched—CME controls north of 80% of U.S. index futures flow—yielding excellent margins and steady fee revenue. Promotion needs are low; incremental tech and clearing efficiency gains flow straight to the bottom line, so milk it, maintain resiliency, and keep fees sensible.
WTI Crude Oil futures serve as the global benchmark with deep, hourly liquidity, recording over 1.0 million average daily contracts on CME in 2024, underpinning dependable cash flow rather than rapid growth. Steady volume and pricing trends allow infrastructure and matching tech upgrades to lift margins without large incremental capex. Focus on protecting benchmark integrity and harvesting predictable fee revenue.
CBOT corn, soybeans and wheat are core hedging tools for the global food system, underpinning a sticky, indispensable flow; global production in 2024 was roughly corn 1.23 billion tonnes, soybeans 392 million tonnes and wheat 782 million tonnes, keeping baseline demand high. Volume ebbs with harvests and weather but the franchise is rock solid; marketing is light because much of the value is baked into tight basis and futures prices. Continue to streamline clearing and cross-margin benefits to lock in low-cost, high-turnover cash cow economics.
Gold futures (COMEX) sit squarely in CME Group’s Cash Cows: timeless hedge with global demand, mature market structure, and minimal promo spend; 2024 ADV about 325,000 contracts and open interest ~1.1 million contracts, usage stays high while spreads remain tight (average bid-offer under $0.30/oz), so focus on operational resilience and fee capture to collect the cash.
Clearing and market data services are recurring, high-margin cash cows for CME Group, tied to network effects that made 2024 net revenue roughly 5.8 billion and kept core margins elevated; low growth but very sticky with strong pricing power. Infrastructure spending has increased operating leverage, letting these units fund new strategic bets without straining capital.
E-mini S&P ADV ~3.0M (2024), CME >80% U.S. index futures share; WTI ADV ~1.0M (2024); Gold (COMEX) ADV ~325k, OI ~1.1M (2024); CBOT grains underpin sticky flows. Clearing & market data net revenue ~$5.8B (2024); low growth, high margins—prioritize resilience, fee capture, modest tech efficiency.
| Instrument | 2024 ADV | Metric | Priority |
|---|---|---|---|
| E-mini S&P | 3.0M | ~80% US share | Maintain fees |
| WTI | 1.0M | Global benchmark | Protect integrity |
| Gold | 325k | OI 1.1M | Fee capture |
| Clearing/Data | - | $5.8B rev | Efficiency |
The CME Group BCG Matrix you’re previewing is the exact final file you’ll receive after purchase. No watermarks, no demo text—just a fully formatted, editable report built for strategic clarity. It’s ready to download, print, or present to stakeholders immediately. Purchase delivers the same concise, market-informed analysis shown here.
Some specialty CME contracts never built durable order books, with many niche listings averaging under 100 contracts ADV and contributing negligible liquidity versus CME Group’s broader volumes (global ADV in the low tens of millions contracts/day). They tie up product, listing and technology attention without proportional fee income. Turnarounds require large marketing, market-maker incentives and often fail to sustain scale. Better to rationalize or sunset low-ADV contracts.
A few minor FX crosses attract virtually no natural hedgers, and CME Group reported in FY2024 that the top five FX futures accounted for over 95% of FX futures average daily volume, leaving obscure crosses with under 5% share. Without hedgers, liquidity providers exit, pushing these contracts toward break-even or loss. They consume operational bandwidth and risk. Trim and redeploy resources to higher-impact FX products.
Legacy pit-era formats or dormant listings at CME sit as Dogs: by 2024 electronic trading represented over 95% of volume at CME Group, leaving pit-based contracts with negligible market share and falling open interest. They neither consume nor generate meaningful cash—mostly operational clutter and fixed-cost overhead. Costly resuscitation won’t reverse structural disinterest; strategic delisting and shelf-cleaning is warranted.
Regionalized energy/utility contracts have narrow appeal on CME: hyper-local benchmarks cannot scale on a global venue, so participation stays shallow, spreads remain wide, and users avoid them; cash stays trapped supporting illiquid contracts. In 2024 such niche contracts represented under 1% of CME energy open interest, prompting recommendations to exit or consolidate into broader benchmarks like WTI, Henry Hub or pan-European power hubs.
Over-engineered bespoke spreads with virtually no user base are dogs in CME Group’s BCG matrix; CME reported an average daily volume of about 20.1 million contracts in 2024, while bespoke spreads represent a vanishing share and add latency to desks that need sub-second pricing.
Dogs: niche contracts with <100 ADV, pit-era listings and bespoke spreads add fixed costs versus CME Group global ADV ~20.1m/day (2024); niche energy <1% energy open interest (2024) and top-5 FX >95% FX ADV (FY2024). Recommend delist/consolidate; marketing rarely recovers scale.
| Contract type | 2024 metric | Implication |
|---|---|---|
| Niche listings | avg <100 ADV | Delist/consolidate |
| Regional energy | <1% energy OI | Merge to broader hubs |
| FX minor crosses | top5=95% ADV | Redeploy resources |
Policy tailwinds are real—voluntary carbon traded roughly $2.2 billion in 2024 (Ecosystem Marketplace)—but liquidity remains fragmented across multiple venues and schemes, diluting price discovery. CME’s clearing trust is a competitive asset, cutting counterparty and credit risk and aiding institutional participation. Realizing high growth requires decisive investment in market-making and standardization; if depth fails to form within 12–24 months, pursue partnerships or prune offerings.
Electrification is a clear megatrend with EVs reaching roughly 16% of global new car sales in 2024, driving structural lithium demand growth. Price discovery for lithium and battery metals is still maturing: spot lithium carbonate prices plunged roughly 60–70% from 2022 peaks into 2024, exposing volatility. Early liquidity in CME-linked battery contracts has been promising but inconsistent, so push index quality, deliverable specs, and commercial onboarding. Scale fast or risk drifting into niche status as industrial adoption accelerates.
Institutional interest rose through 2024, but most crypto options volume remains off-exchange or in spot options; CME offers BTC options (launched 2020) and ETH options (launched Aug 2023) and benefits from regulated clearing and strong counterparty credibility.
With improved block trading, margining and longer tenors CME can expand share; invest in targeted liquidity programs and institutional education, and narrow the lineup if traction stalls.
Overnight Asia-session liquidity is expanding as hedging flows migrate to 24/5 trading, lifting USD rates share in APAC sessions though depth still trails U.S. core hours; market-maker incentives and targeted regional client onboarding can materially increase depth, otherwise the Asia window risks shifting to maintenance mode.
Event-style, bite-size retail contracts beyond micros saw rising appetite in 2024 for simple, low-stakes speculation but customer behavior remained fickle and regulated access tightened in several jurisdictions; growth can be significant with intuitive UX and targeted education. Successful rollout demands marketing muscle, vigilant risk controls, and a clear scale plan to avoid becoming noise without revenue.
Question Marks show strong policy and demand tails but fragile liquidity: voluntary carbon ~$2.2B (2024), EVs ~16% of new car sales (2024) with lithium spot down ~60–70% from 2022, rising institutional crypto interest but uneven on-exchange volumes, and growing Asia 24/5 hedging. Invest in market-making, standardization, regional onboarding or prune within 12–24 months.
| Product | 2024 signal | Key metric | Action |
|---|---|---|---|
| Carbon | Policy tailwinds | $2.2B | Standardize |
| Battery metals | Demand + volatility | Li -60–70% | Scale fast |
| Crypto | Inst. interest | Options on CME | Trade infrastructure |
| Asia rates | 24/5 rise | Lower depth | MM incentives |


