
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock CNPC Capital’s strategic playbook with our concise Business Model Canvas — three to five actionable sentences revealing how the firm creates value, monetizes assets, and sustains competitive advantage. Ideal for investors, strategists, and founders, the full downloadable canvas (Word & Excel) delivers the complete nine-block analysis and ready-to-use insights to inform deals and strategy. Purchase now to access the detailed breakdown and financial implications.
Core partnership with CNPC HQ and subsidiaries gives CNPC Capital mandate, volume and proprietary data access, aligning financial products to group strategy and 2024 capex cycles (RMB 300 billion capex guidance). This secures captive demand for banking, insurance, leasing and asset management, while enabling group-wide liquidity pooling and enterprise-level risk optimization across domestic and international operations.
CNPC Capital partners with major state banks—including ICBC, China Construction Bank, Agricultural Bank of China and Bank of China—for syndicated loans, credit lines and RMB settlement facilities, lowering cost of funds and diversifying liquidity sources. These relationships support large project financing and trade finance needs and, given the Big Four’s standing among the top global banks by assets in 2024, enhance CNPC Capital’s credibility and market reach.
Maintains licences and compliance with PBOC, NAFR/CBIRC, CSRC and SAFE to operate as a regulated SOE financial arm. Access to China interbank market and bond exchanges supports issuance and investment, with the onshore bond market exceeding RMB 140 trillion in 2024. This partnership framework enforces risk standards and policy alignment while enabling RMB, FX and cross-border flows backed by roughly USD 3.1 trillion in FX reserves.
CNPC Capital partners with insurers and reinsurers to secure capacity through reinsurance treaties and specialty risk-transfer solutions, improving capital efficiency and underwriting resilience. These relationships provide access to global catastrophe and energy-risk expertise, leveraging 2024 market capacity reported near record levels by Aon to optimize program design. This stabilizes loss ratios across cycles and supports solvency management.
CNPC Capital partners with core banking, treasury, ERP and risk analytics vendors to scale operations; API and data integrations improve visibility across legal entities and enable automation and real-time decisioning. Cybersecurity partners protect sensitive financial data—global security spending was about 188 billion USD in 2023 (Gartner), signaling material investment in defenses.
Partnerships with CNPC HQ, Big Four state banks and global insurers secure captive demand, lower funding costs and provide reinsurance capacity for energy risks aligned with CNPC’s RMB 300 billion 2024 capex guidance. Regulatory links (PBOC, CBIRC, CSRC, SAFE) enable access to the RMB onshore bond market (>RMB 140 trillion in 2024) and cross-border flows (~USD 3.1 trillion FX reserves). Tech and cybersecurity vendors enable API-led integrations and protection amid ~USD 188 billion global security spend (2023).
| Partnership | Key 2024/2023 Figure |
|---|---|
| CNPC capex guidance | RMB 300 billion (2024) |
| Onshore bond market | >RMB 140 trillion (2024) |
| FX reserves | ~USD 3.1 trillion (2024) |
| Cybersecurity spend | USD 188 billion (2023) |
 Detailed Word Document
Comprehensive Business Model Canvas for CNPC Capital detailing customer segments, channels, value propositions and revenue streams across the nine BMC blocks, with competitive-advantage analysis, linked SWOT insights and polished narratives ideal for investor presentations and strategic decision-making.

 Customizable Excel Spreadsheet
Condenses CNPC Capital’s complex strategy into a clean, one-page Business Model Canvas with editable cells—ideal for teams to quickly identify core components, save hours of structuring, and adapt the model for boardrooms, comparisons, or fast executive summaries.
Centralized treasury runs cash pooling across >500 group entities to optimize net interest and working capital, using intra-group lending to reduce external financing; daily liquidity pools target a c.¥100–200bn operational buffer. It manages consolidated debt maturities and liability mix to lower refinancing risk and executes FX and commodities hedges aligned to exposures (Brent ~$86/bbl 2024) within a macro context of c.$3.1tn China FX reserves.
Corporate banking provides loans, guarantees, trade finance and settlement services to CNPC subsidiaries, supporting upstream and downstream operations. It structures capex and project finance solutions for major energy projects and infrastructure. Pricing follows risk-adjusted return mandates within group policies and 2024 governance updates. It actively manages covenants and collateral to protect group balance-sheet integrity.
Design P&C, engineering, liability and employee benefit covers tailored to upstream, midstream and downstream risks. Administer claims and loss-prevention programs to reduce frequency and severity. Negotiate reinsurance and set retentions to optimize capital efficiency. Monitor exposure accumulation across assets and geographies as CNPC operates in over 70 countries as of 2024.
CNPC Capital finances rigs, pipelines, refining equipment and logistics fleets via operating and finance leases and targeted sale-leasebacks, supporting a multi‑billion-dollar equipment portfolio in 2024. It manages residual value and asset recovery, aligning lease terms to asset life and projected cash flows to preserve liquidity and mitigate depreciation risk.
Manage surplus cash, pension and reserve portfolios through diversified allocations to money markets, domestic and sovereign bonds, and policy-aligned instruments; China's onshore bond market was ~150 trillion CNY in 2024, offering deep liquidity. Run liquidity ladders and ALM to match duration and cashflow needs, supported by reporting, performance and risk analytics with daily VaR and scenario stress testing.
Centralized treasury pools cash across >500 entities, targeting a ¥100–200bn buffer, managing debt maturities and FX/commodity hedges (Brent ~$86/bbl 2024) against China FX reserves ~$3.1tn. Corporate banking provides loans, guarantees, trade and project finance with covenant controls. Asset finance and insurance manage rigs/pipelines/refining fleets (multi‑bn portfolio), leases, RV recovery and ALM with daily VaR.
| Activity | 2024 Metric |
|---|---|
| Group entities | >500 |
| Liquidity buffer | ¥100–200bn |
| Brent | $86/bbl |
| China FX reserves | $3.1tn |
| Onshore bond market | ¥150tn |
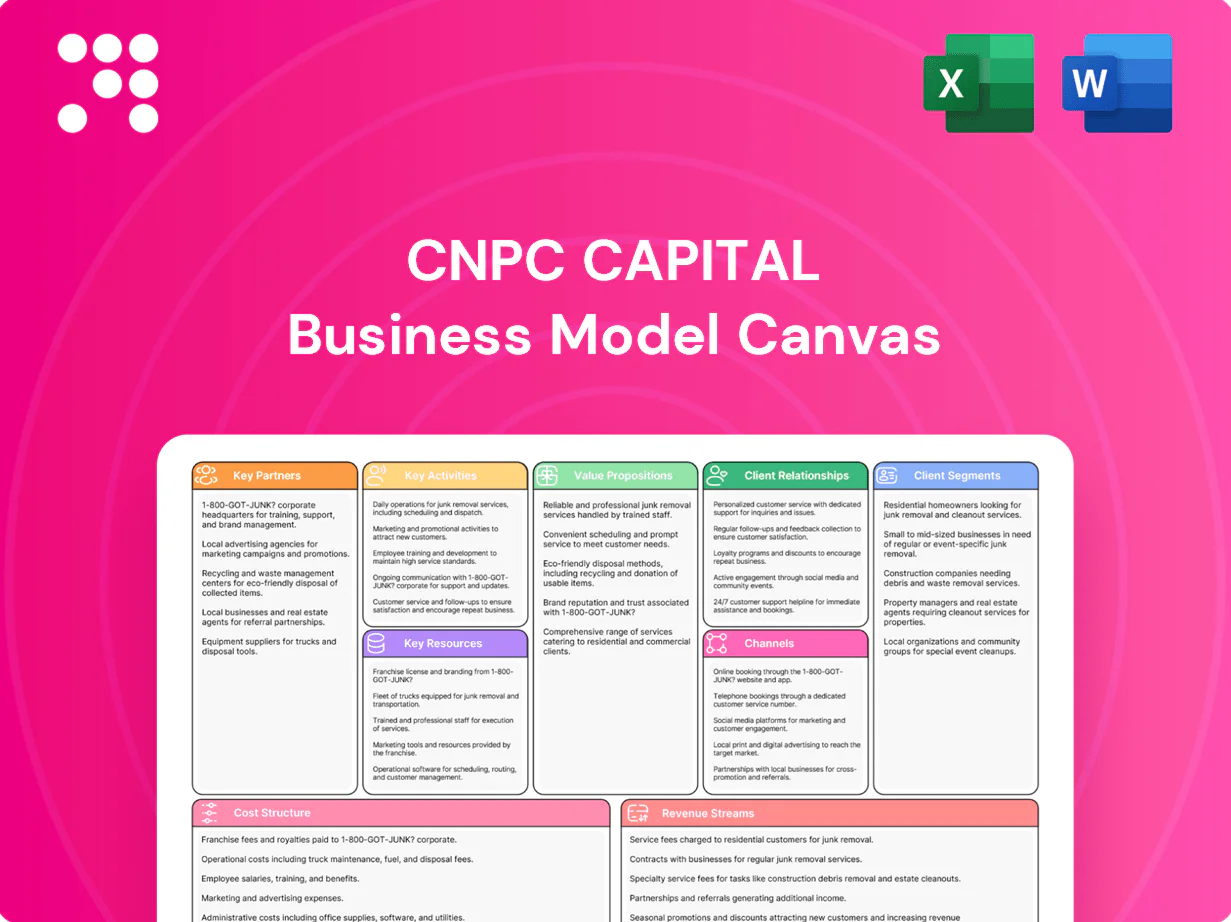
The CNPC Capital Business Model Canvas shown here is the actual deliverable, not a mockup, and reflects the exact structure and content you’ll receive after purchase. Upon ordering, you’ll instantly get the full file—ready-to-edit in Word and Excel—with all sections, formatting, and data included. No placeholders, no surprises—what you preview is what you’ll own.
Parent CNPC support delivers scale, credibility and a steady project pipeline, underpinned by CNPC’s state-owned status and placement on the 2024 Fortune Global 500. Access to the group balance sheet and parent guarantees materially lowers CNPC Capital’s funding costs and enhances ratings uplift. A strategic mandate ensures a captive flow of lending opportunities and stronger counterparty confidence.
Regulatory licenses for banking, insurance, leasing and asset-management approvals enable CNPC Capital to underwrite, insure and deploy capital across corporate and project finance lines. Market access includes interbank, FX and bond platforms, tapping a domestic bond market exceeding CNY 150 trillion in 2024 and global FX liquidity underpinning cross-border flows. Embedded compliance frameworks ensure regulatory alignment and auditability across transactions. Licenses facilitate RMB international business as RMB reached roughly 3.6% of global payments in 2024.
CNPC Capital maintains a strong capital base to underwrite, lend, and invest, with diversified funding channels—domestic bonds, interbank markets and group deposits—managing duration and cost. Contingent liquidity arrangements with state-owned partners and access to capital markets provide additional buffers. These resources support resilience under stress and enable sustained lending and investment activity.
CNPC Capital's data and systems centralize treasury, core banking, policy administration and risk engines into a unified platform, driving credit, market and operational risk analytics from data lakes (>5 PB) and real-time ERP/SCM feeds with sub-second updates. Integrated risk engines and policy admin support automated decisioning; STP rates exceed 90% for trade and payment flows in 2024, while automation strengthens controls and reduces manual interventions by ~70%.
Specialist talent at CNPC Capital combines risk, actuarial, project finance and energy-sector experts with relationship managers embedded in business units, supported by legal, compliance and ALM professionals to underwrite complex deals; global energy investment topped about 2.6 trillion USD in 2024, underscoring scale and skill needs.
Parent backing, licenses and a strong capital base give CNPC Capital low funding costs, captive deal flow and cross-border capabilities; tech (data lakes >5 PB, STP >90%) and specialist talent (risk, actuarial, project finance) enable complex underwriting. Market access taps a CNY 150+ trillion domestic bond market and supports RMB internationalization (≈3.6% payments, 2024).
| Metric | 2024 |
|---|---|
| Data lakes | >5 PB |
| STP | >90% |
| Domestic bond market | CNY 150+ T |
| RMB global payments | ≈3.6% |
Leveraging CNPC group scale and parent guarantees, CNPC Capital cut external funding spreads, translating into lower weighted average borrowing costs versus standalone peers in 2024. Internal transfer pricing aligns with group credit metrics, reducing external interest outflows and delivering measurable savings on finance expense. An optimized debt mix and cash-pooling reduced idle balances and short-term issuance, driving tangible interest-cost reductions for the group.
One-stop finance integrates banking, insurance, leasing and asset management within CNPC Capital, providing a single interface that simplifies approvals and execution. Coordinated terms accelerate deal timelines and improve coherence across financing structures. This reduces friction across the full project lifecycle, aligning with CNPC's 2024 strategic push for integrated financial solutions.
Liquidity assurance ensures CNPC Capital provides reliable access to working capital and capex funding to sustain upstream and downstream projects, aligning with IEA 2024 estimates of ~1.2 mb/d global oil demand growth that pressures investment needs.
CNPC Capital offers tailored insurance and hedging programs to mitigate commodity, operational and political energy risks, consolidating exposures under enterprise risk oversight to enable centralized control. Strategic reinsurance purchases and derivatives positions smooth earnings volatility and protect cash flow. These measures enhance capital efficiency and support compliance with regulatory capital and reserve rules as CNPC remains a top global oil and gas firm in 2024.
Financial solutions are explicitly tied to CNPC strategy and policy to fund overseas expansion—operating in over 70 countries—and domestic projects, aligning capital with strategic priorities. Robust governance frameworks provide transparency and auditability through standardized controls and internal audits. Centralized capital allocation and risk management deliver group-wide optimization and improved capital efficiency across subsidiaries.
CNPC Capital leverages parent support to lower group funding costs and centralizes finance, insurance, leasing and asset management into a one-stop service that accelerates project execution. Liquidity assurance backs capex and working capital amid IEA 2024 global oil demand growth of ~1.2 mb/d, while tailored hedging and reinsurance smooth cash flow and improve capital efficiency.
| Metric | 2024 Fact |
|---|---|
| Countries | Over 70 |
| IEA demand growth | ~1.2 mb/d (2024) |
Captive mandates are structured as long-term internal service agreements with CNPC business units, securing predictable demand and multi-year planning horizons. They include prioritized service levels and transparent pricing frameworks aligned with corporate budget cycles. Embedded escalation paths and governance boards ensure rapid resolution and compliance with CNPC group policies.
Dedicated relationship managers cover four pillars—upstream, midstream, downstream and international—ensuring focused coverage and bespoke credit and insurance programs. Quarterly reviews assess pipeline, risk and performance to align capital deployment and limits. Tailored credit and insurance structures support project timelines and commodity risk. Cross-sell initiatives link lending, treasury, trade finance and insurance suites to deepen wallet share.
Advisory partnership delivers project finance structuring, risk engineering, and ALM advisory to support feasibility studies, tender preparation, and capital structuring for upstream and midstream projects.
We coordinate end-to-end with EPC contractors and lender syndicates to align cashflow models, covenants, and security packages while providing market insights and benchmark pricing from global debt and equity markets in 2024.
Service-level agreements set defined turnarounds: 72-hour claims, 5-business-day loan decisions and settlements, with a 2024 industry benchmark SLA compliance target of 95%. KPI dashboards track time-to-decision, NPS and settlement accuracy; penalties/credits automatically adjust fees for missed SLAs (typical cap 3–5%). Continuous improvement cycles run quarterly, using root-cause analytics and process automation. Reporting is transparent to management via monthly scorecards and real-time dashboards.
CNPC Capital offers digital self-service portals for requests, tracking, and documentation, with APIs linking subsidiary ERPs to central treasury systems for streamlined workflows. Real-time dashboards show balances, exposures, and premiums updated intra-day (2024 integration standard), while chat/ops support resolves exceptions and SLA breaches within targeted 2-hour windows.
Captive mandates deliver multi-year predictable demand with prioritized SLAs and governance; SLA target 95% (2024). Dedicated RMs cover upstream/midstream/downstream/international with quarterly reviews and bespoke credit/insurance. Digital portals and APIs provide intra-day balances; support resolves exceptions within 2-hour SLA. Penalties/credits adjust fees 3–5% for missed SLAs.
| Metric | Value |
|---|---|
| SLA target (2024) | 95% |
| Claims turnaround | 72 hours |
| Loan decision | 5 business days |
| Support SLA | 2 hours |
| Fee adjustments | 3–5% |
Group directives route board and finance policies to channel business internally, using mandates that define product usage and priorities and ensuring adoption across subsidiaries; CNPC reported group revenue of about RMB 2.26 trillion in 2023, underscoring scale for centralized mandates. These directives align investment and operational decisions with strategic plans and cascade compliance across the network of downstream and upstream units.
Finance shared service centers consolidate requests and processing across CNPC Capital, handling centralized invoicing and payments to reduce duplicated tasks. Standardized workflows cut processing time and error rates, aligning with industry SSC gains of 20-30% efficiency. A hub-and-spoke model covers 30+ provinces nationwide. Operations run on SLA-based metrics targeting >99% compliance.
Single sign-on unifies loan, insurance and leasing workflows into one credential set, reducing friction and supporting 2024 industry benchmarks of ~30% faster decision cycles. Dashboards and e-docs streamline approvals and cut paperwork by up to 40% in comparable lenders. Real-time notifications and status alerts plus mobile access—85% field-team adoption in 2024 peers—ensure approvals on the go.
CNPC Capital's API integrations connect treasury with ERPs, TMS, and procurement to automate payments, reconciliation, and data feeds. 2024 pilots showed reconciliation time cut by ~70% and error rates falling below 1%, shifting latency from hours to near-real-time. Continuous APIs enable real-time risk monitoring and end-to-end liquidity visibility across pools.
On-site CNPC Capital teams embed finance staff at major projects and refineries to enable rapid decisions and tailored financing solutions aligned with CNPC’s integrated operations. They coordinate claims and audits on-site to accelerate settlements and maintain compliance. Proximity strengthens stakeholder relationships and channels real-time feedback into product design; in 2024 China represented about 17% of global oil demand, highlighting on-site strategic value.
Channels combine centralized mandates, SSCs, SSO, APIs and embedded on-site teams to drive adoption, cut processing time and enable real-time liquidity/risk views; CNPC group revenue ~RMB 2.26trn (2023) and SSCs target >99% SLA. 2024 pilots: reconciliation -70%, error <1%, field adoption ~85%, decision cycles ~30% faster. Channels prioritize speed, compliance and integration.
| Metric | Value |
|---|---|
| Group revenue (2023) | RMB 2.26 trillion |
| Reconciliation cut (2024 pilot) | ~70% |
| Error rate (pilot) | <1% |
| Field adoption (peers, 2024) | ~85% |
| SLA compliance target | >99% |
In 2024 CNPC Capital prioritized upstream capex finance, insurance and hedging for E&P units, funding drilling campaigns and field development to sustain production growth.
It manages geological and operational risks through tailored risk-transfer and technical due diligence while providing equipment leasing and performance guarantees to accelerate projects.
Midstream and logistics customers include pipeline operators, storage terminal owners and transport consortia seeking long‑tenor project finance for large infrastructure. CNPC Capital structures loans with extended maturities and tailored covenants to secure continuity and insure physical assets and revenue streams. Financing also optimizes working capital through receivables, inventory facilities and tariff‑linked repayment profiles. Risk mitigation combines asset insurance, business continuity clauses and tariff escalation mechanisms.
Serving refineries and petrochemical complexes, CNPC Capital finances turnarounds and expansions for upstream and downstream projects for CNPC group companies and partners. It provides commodity price risk management via hedging programs tied to crude and product markets and offers asset-heavy leasing solutions for processing units and tankage. The segment targets large-capex, long-tenor deals aligned with energy transition investments.
CNPC Capital provides cross-border financing and risk solutions for overseas JVs and projects, managing FX, sanctions and political risks while coordinating with international lenders and insurers to secure long-tenor facilities. As of 2024 China is the world’s largest crude oil importer, underpinning continued outbound energy investment and the need for global-compliant financing.
CNPC Capital targets employees and the broader ecosystem by offering selected retail and affinity financial products tailored for staff, integrating vendor and supplier financing within corporate policies, and centralizing employee benefits administration to streamline access and compliance.
CNPC Capital focuses on upstream E&P capex finance, drilling and hedging to sustain production growth.
Midstream clients receive long‑tenor project finance, asset insurance and tariff‑linked structures to secure cashflows.
Refinery/petrochemical customers get turnaround and expansion finance plus commodity hedging; it also provides cross‑border FX and political risk solutions.
| Segment | 2024 note |
|---|---|
| Upstream | Capex, hedging |
| Midstream | Long‑tenor project finance |
| Downstream | Turnaround/expansion finance |
| Cross‑border | Supports overseas JVs; China was world’s largest crude importer in 2024 |
Interest expense on borrowings and deposits is anchored to China benchmark rates (2024 1yr LPR 3.65%, 10yr CGB ~2.85%) plus corporate spreads; liquidity buffers and commitment fees typically add 25–50 bps; hedging costs for FX and rates range ~10–40 bps; overall cost of funds is driven by market spreads and CNPC group credit profile.
Loan loss provisions and write-offs form a core cost line as CNPC Capital must reserve against project-specific credit deterioration and sectoral oil & gas cyclicality. Insurance claims, reserves and reinsurance premiums add volatility, with claims driven by upstream project incidents and commodity-linked exposures. Counterparty defaults and recoveries influence net credit expense through recoveries, collateral realization and restructuring outcomes. These costs are cyclical, rising in downturns with higher project losses and falling during stable market periods.
Operating expenses for CNPC Capital center on personnel and branch costs plus shared services, with vendor, outsourcing and professional fees covering IT, compliance and advisory; payment and settlement costs arise from bank and clearing fees, while training and travel fund on-site support and field audits.
Technology and data costs cover core systems, enterprise licenses and cloud spend—often 25–35% of tech budgets—while cybersecurity and data management consume roughly 10–15% for resilience and compliance; API and portal development plus ongoing maintenance drive recurring engineering costs, and analytics/model validation require dedicated teams and ~5–8% of operating expenses to meet 2024 regulatory and ML-audit expectations.
Compliance and governance for CNPC Capital covers regulatory reporting and audits, adherence to Basel III minima (CET1 4.5% and total capital ratio 8% as of 2024) and ongoing solvency monitoring, plus legal and enterprise risk management overhead to meet China and international standards.
CNPC Capital cost base is driven by interest expense (2024 1yr LPR 3.65%, 10yr CGB ~2.85%) plus spreads, liquidity buffers 25–50bps and hedging 10–40bps; credit costs (LLP/write-offs) vary with oil & gas cycles; Opex centers on personnel, shared services and tech (core systems 25–35% of tech spend, analytics 5–8% of Opex); compliance holds CET1 4.5% / total 8% capital overhead.
| Metric | 2024 Value |
|---|---|
| 1yr LPR | 3.65% |
| 10yr CGB | ~2.85% |
| Liquidity buffer | 25–50bps |
| Hedging | 10–40bps |
| Tech:core systems | 25–35% |
| Analytics %Opex | 5–8% |
| CET1 / Total | 4.5% / 8% |
Interest income derives from intra-group loans, overdrafts and deposits supporting upstream projects, plus project finance and revolving facilities for EPC and gas pipelines. Treasury placements and interbank placements leverage overnight and term markets; China 1-year LPR stood at 3.65% in 2024. Centralized pooling of group liquidity boosts net interest margin through internal funding spreads and lower excess cash costs.
Insurance premiums—P&C, engineering, liability and health—constitute CNPC Capital’s core revenue, reported as earned premiums net of reinsurance with ancillary fees and profit commissions layered on top. Profit commissions and fee income augment underwriting margins, while investment float generated from premium timing contributes materially to returns, typically adding low-double-digit percentage points to investment income in 2024. The mix prioritizes P&C engineering and large-liability covers to match CNPC’s asset and project exposures.
Leasing income stems from rental payments and finance-lease interest providing predictable cash flow; CNPC Capital reported a leasing portfolio >RMB 200 billion in 2024, yielding mid-single-digit returns. Residual value gains and terminal fees materially boost total returns, while asset-management and servicing charges create recurring fee income. Contractual penalties and buyout options enhance recovery and upside on early terminations.
CNPC Capital earns management fees on group funds in line with 2024 industry ranges of 0.5–1.5% p.a., plus performance fees commonly 10–20% of outperformance.
Mandates include liquidity and reserve requirements that drive predictable fee income and reduce redemption risk.
Custody and reporting services are billed as recurring fees; securities lending, where permitted, adds incremental revenue (typically 1–5 bps of AUM in 2024).
Treasury and advisory fees combine FX/hedging spreads and structuring fees, guarantees, letters of credit and trade finance facilitation, plus consulting on risk and project structuring; arrangement and underwriting income capture transaction origination margins. In 2024 China’s FX reserves were about 3.12 trillion USD, supporting large-scale FX hedging and trade finance capacity. Fee mix emphasizes recurring hedging spreads and one-off underwriting/arrangement fees tied to project value.
CNPC Capital earns interest from intra-group/project finance and treasury placements (China 1yr LPR 3.65% in 2024), insurance premiums with investment float adding low-double-digit points in 2024, leasing income from a >RMB 200bn portfolio yielding mid-single digits, and fees (management 0.5–1.5% p.a., performance 10–20%, securities lending 1–5 bps). Treasury/advisory and guarantees add transaction fees and contingent income.
| Stream | 2024 metric |
|---|---|
| Interest | 1yr LPR 3.65% |
| Leasing | >RMB 200bn, mid-5% yield |
| Mgmt fees | 0.5–1.5% p.a. |
| Perf fees | 10–20% |


