
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
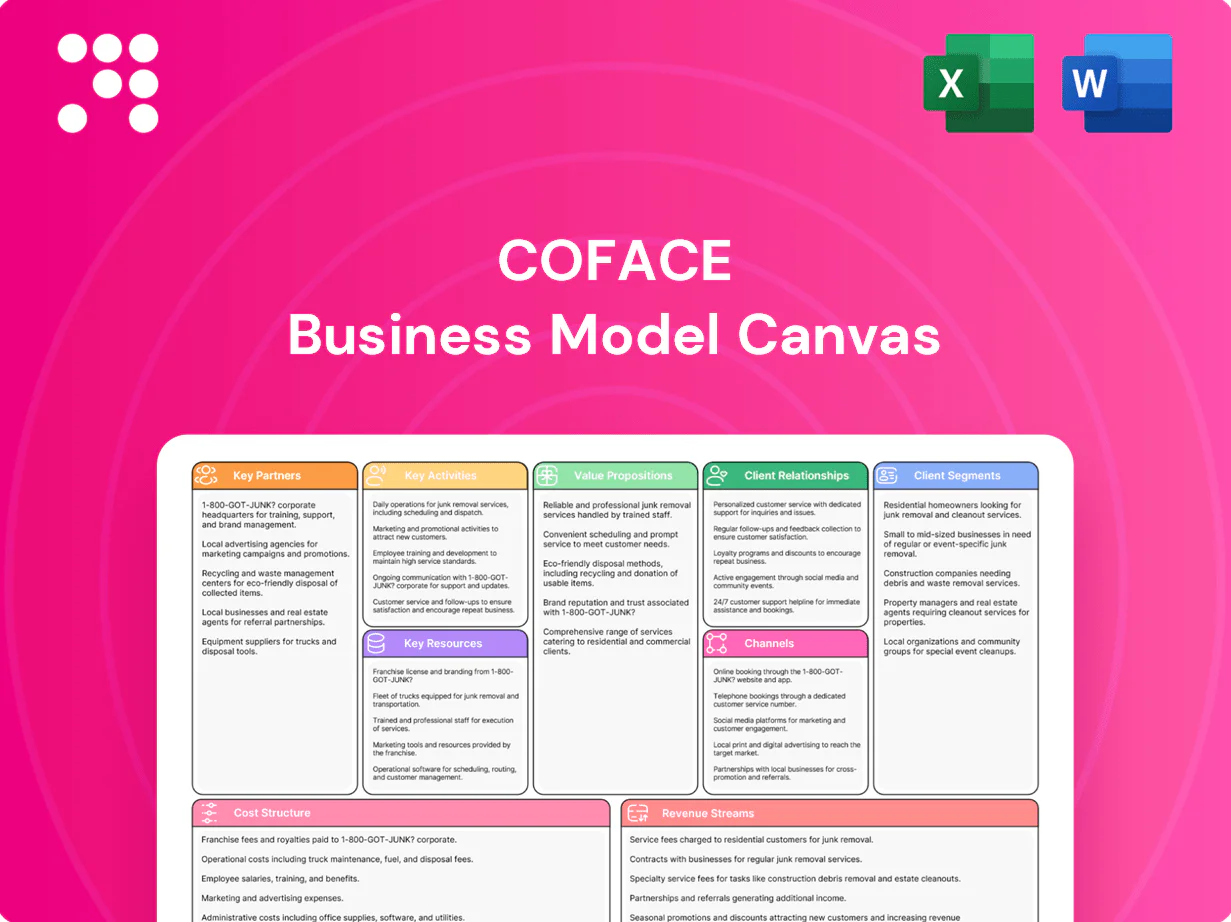
Unlock Coface’s strategic blueprint with a concise Business Model Canvas that maps its value propositions, customer segments, key partners and revenue logic. See where competitive advantage, risks and growth levers align in one clear snapshot. Purchase the full, editable Canvas to use in benchmarking, strategy or investor work.
Proprietary datasets combining extensive payment behavior, claims history and buyer records power Coface analytics, leveraging a network covering 200 countries and a legacy since 1946. Global trade datasets and longitudinal records create a defensible moat for credit scoring and risk pricing. Data quality, timeliness and coverage are treated as core differentiators across underwriting and recovery. APIs and centralized data lakes enable internal models and client integrations in real time.
Risk models combine credit scoring, limit algorithms and early-warning systems to monitor counterparty risk in real time, supporting Coface underwriting and policy administration platforms that ensure scale and control across portfolios.
AI/ML models implemented in 2024 improved prediction accuracy and automated workflows, with industry surveys reporting insurer AI adoption above 60% that year.
Robust cyber and compliance frameworks protect data and model integrity, reducing operational risk and regulatory breaches while enabling secure, scalable risk decisioning.
Insurance licenses across 100+ countries (Coface, 2024) enable local distribution and cross-border solutions. Adequate solvency capital underpins policy promises and supports measured growth. Reinsurance programs optimize capital efficiency and limit net exposure. Robust compliance capabilities handle multi-country regulatory demands and reporting.
Coface leverages a presence in 100+ countries with 4,400 employees (2024), multilingual teams in key trade corridors, and a recognized trade-credit brand that fosters client trust; local expertise boosts recovery and legal navigation while network effects enrich risk data and speed service delivery.
Expert talent at Coface—underwriters, economists, data scientists and collectors—delivers risk pricing and recovery, supported by sector specialists for nuanced views and claims/legal teams that improve recovery rates; partner management and sales expand channels across 100+ countries and a workforce of ~4,400 (2024 company footprint).
Proprietary trade datasets, APIs and centralized data lakes (200 countries, longitudinal records since 1946) underpin credit scoring and real-time decisioning. Risk models and AI/ML (2024 AI uplift) automate underwriting and monitoring. Insurance licenses and reinsurance across 100+ countries, solvency capital and robust compliance secure promises. Local teams (4,400 employees, 2024) drive collections, recovery and client trust.
| Metric | Value (2024) |
|---|---|
| Countries | 100+ |
| Employees | 4,400 |
| AI adoption uplift | >60% |
| Legacy data | Since 1946 |
Coverage for insolvency and protracted default stabilizes cash flows, lowering bad-debt expense and earnings volatility for clients. Coface policies enable safer market entry and acceptance of larger orders, supporting revenue growth. In 2024 Coface continued operating across 100+ countries, offering credit risk solutions that free management to focus on expansion.
Insured receivables enable companies to unlock bank funding and obtain better terms; in 2024 Coface-backed policies facilitated access to roughly €15bn of bank financing for clients. Lenders accept insured assets as collateral, reducing lenders' risk and lowering borrowers' cost of capital. Policies are increasingly used to underpin supply chain finance programs and securitizations. The result is improved liquidity that shortens working capital cycles and boosts cash conversion.
Continuous buyer monitoring and dynamic ratings inform sales decisions, backed by Coface’s global footprint in 100+ countries (2024) to contextualize risk across markets. Clients set smarter credit limits and tailored payment terms using quantitative scores and behavior signals. Dashboards and real-time alerts provide early warnings to reduce exposure, with insights extending beyond insured buyers to analyze full portfolios for proactive risk management.
Professional, cross-border recovery services raise net outcomes by combining centralized coordination with local legal expertise that accelerates enforcement; Coface operates in 100+ countries, enabling faster case handling and jurisdictional reach. Transparent reporting and aligned incentives build trust with clients and creditors, while reduced DSO and higher recovery rates improve cash conversion for working capital management.
Flexible, scalable coverage: Coface offers tailored policies from whole-turnover programs to single-risk limits, with top-up, excess-of-loss and captive support options, and modular endorsements by sector and geography; Coface is present in 100+ countries and provides global risk intelligence across 200+ markets (2024).
Coface stabilizes cash flow and reduces bad-debt volatility via insolvency and protracted-default cover, enabling safer market entry and revenue growth. Insured receivables unlocked about €15bn of bank financing in 2024, improving liquidity and lowering cost of capital. Global risk intelligence and buyer monitoring across 100+ countries and 200+ markets enable proactive credit decisions and faster recoveries.
| Metric | 2024 |
|---|---|
| Geographic footprint | 100+ countries |
| Market coverage | 200+ markets |
| Bank financing enabled | €15bn |
Dedicated account managers coordinate underwriting, claims and service for clients across Coface's network in 100+ countries, ensuring consistency and local expertise. They conduct regular reviews to optimize limits and policy terms, provide strategic guidance aligning coverage with 2024 growth plans, and maintain escalation paths that guarantee prompt, SLA-driven issue resolution.
Portals for limit requests, declarations and claims filing give clients 24/7 digital self-service access to submit and track cases, with real-time statuses, dashboards and alerts reducing back-and-forth communications.
Workshops on credit policy and best practices deliver tailored sessions that reduce exposure and align with Coface’s 2024 Country Risk Map covering 162 countries. Sector outlooks and country risk updates draw on the 2024 sector barometer to flag emerging vulnerabilities. Joint simulations to stress-test portfolios quantify downside scenarios and elevate clients’ internal credit capabilities through hands-on training.
Data-driven touchpoints trigger proactive communications when risk signals shift, delivering quarterly portfolio analytics and benchmarking that translate into tailored insights for CFOs and credit managers and show value beyond indemnification.
Brokers provide day-to-day assistance and advocacy for Coface clients, resolving claims and onboarding risks while feeding market intelligence; in 2024 Coface reported premium income around €1.9bn, underscoring broker distribution importance. Tri-party collaboration aligns incentives and information flow between client, broker and underwriter, supported by service-level agreements that set expectations, improving satisfaction and retention.
Dedicated account managers coordinate underwriting, claims and service across Coface’s 100+ country network, aligning coverage with the 2024 Country Risk Map (162 countries) and SLA-driven escalation. 24/7 digital portals plus quarterly analytics deliver proactive alerts and CFO-focused insights that reduce exposure and cycles. Broker-led distribution supports retention and generated ~€1.9bn premium income in 2024.
| Metric | 2024 |
|---|---|
| Countries covered | 100+ |
| Risk map | 162 countries |
| Premium income | €1.9bn |
| Portal uptime | 99.9% |
| SLA response | 24–72h |
In 2024 Coface's broker network across 100 countries distributes credit insurance to all client sizes, from SMEs to multinationals. Brokers bundle coverage with broader risk solutions such as debt collection and country-risk intelligence, while broker portals streamline quotes and endorsements to reduce administrative cycles. Education programs and incentive schemes in 2024 targeted improved pipeline quality and higher placement rates.
Relationship managers target strategic accounts within Coface's 100+ country network, focusing on high-exposure corporates. Consultative selling aligns trade-credit and insurance solutions to client risk profiles and portfolio metrics. Vertical specialists address sector-specific exposures such as commodities and construction. Account-based marketing supports personalized engagement across key accounts.
Coface embeds offers with trade finance and factoring through bank and lender partnerships, enabling white‑label and co‑branded solutions and joint pitches to treasury and credit teams. In 2024 Coface reported €1.8bn revenue, leveraging partner distribution to scale financed receivables. Real‑time data links and APIs speed underwriting and can cut decision time by up to 50%. Joint go‑to‑market increases penetration into corporate cash‑management channels.
Digital platforms offer instant quote-bind for SMEs and mid-market customers; RESTful APIs connect to ERP, e-invoicing systems and marketplaces to automate risk checks and policy issuance. Self-service portals and embedded flows cut cycle times and cost-to-serve by up to 40% (2024 industry benchmark) and partners can embed cover at point of transaction, lifting conversions by ~15%.
Coface's thought leadership combines country risk conferences, reports and webinars built on its 163-country risk coverage, driving credibility and inbound demand through authoritative analysis in 2024.
In 2024 Coface used a 100-country broker network and 163-country risk coverage to distribute credit insurance to SMEs and multinationals, supporting €1.8bn revenue. Digital APIs and portals cut underwriting time up to 50% and cost-to-serve ~40%, while embedded cover lifted conversions ~15% and partner channels scaled financed receivables.
| Metric | 2024 |
|---|---|
| Revenue | €1.8bn |
| Broker network | 100 countries |
| Risk coverage | 163 countries |
| Underwriting time | -50% |
| Cost-to-serve | -40% |
| Conversion lift | +15% |
SMEs and mid-market exporters, which represent roughly 90% of firms and about 50% of global employment (World Bank, 2024), need affordable, simple credit insurance to support growth. They benefit from digital onboarding and standardized terms that speed access to cover. Insured receivables unlock bank financing, while packaged intelligence and collections reduce DSO and bad-debt risk.
Large corporates and multinationals run complex portfolios across sectors and jurisdictions, often spanning 100+ countries where Coface is present. They require tailored programs, high credit limits and captive solutions to manage concentrated exposures. These clients demand advanced analytics, API integration and governance reporting for real-time oversight, plus robust global recoveries and compliance capabilities.
Banks and trade finance providers use trade credit insurance to de-risk lending on receivables and insist on fast decisions and policy terms aligned to loan covenants. They prefer both portfolio and single-name covers and integrate real-time data feeds and eligibility rules into credit workflows. The ICC estimated a global trade finance gap of about 1.7 trillion USD in 2022, underscoring demand.
Factors and SCF platforms for Coface target factors and corporate treasuries, enabling insured invoices to materially increase advance rates (market practice often reaches 80–90%), requiring seamless ERP/API integrations and real-time credit limit checks to avoid exposure breaches, scalable orchestration across thousands of buyers and suppliers, and claims workflows designed for rapid settlement to protect cashflow.
Credit managers, analysts and treasurers subscribe to Coface business information and ratings to feed credit decisions, compliance checks and cash‑flow planning; these insights directly shape credit policies and mitigate exposure while often acting as a gateway to trade credit insurance upsell. Coface operates in over 100 countries, supporting multinational risk teams.
SMEs (~90% of firms, ~50% of employment — World Bank 2024) need affordable, fast digital credit insurance; large corporates require bespoke global programs across Coface's 100+ countries; banks use cover to de-risk lending amid a $1.7T trade finance gap (ICC 2022); factors/SCF seek 80–90% advance rates and API integration.
| Segment | Key needs | Metric |
|---|---|---|
| SMEs | Digital onboarding, standardized cover | ~90% firms; ~50% employment (2024) |
| Large corporates | Tailored limits, analytics | Coface: 100+ countries |
| Banks/Factors | Real-time limits, high advance | $1.7T gap (ICC 2022); 80–90% advance |
Indemnity payouts are Coface’s largest variable expense, driving short-term cash outflows and reserve needs. Recovery fees and legal costs reduce net recoveries and can materially widen net loss on large claims. Active frequency and severity management—through underwriting, pricing and credit limits—directly improves profitability. Reinsurance cessions shift cost exposure and lower retained claim volatility.
Broker commissions, partner fees and sales salaries form the bulk of Coface’s acquisition cost, with commissions commonly accounting for double-digit percentages of premiums and Coface reporting €1.9bn in gross written premiums in 2024, concentrating spend on distribution. Marketing, events and enablement platforms (CRM, training) are recurrent fixed and variable costs to sustain renewal and cross-sell. Channel incentives target growth segments (SMEs, trade corridors) while digital acquisition reduces unit costs over time through automation and lower CAC.
Operations and technology costs cover policy administration, underwriting platforms and client portals, with 2024 investments focused on scalable SaaS and cloud-based admin systems. Data acquisition, storage and cybersecurity are prioritized to meet 2024 regulatory expectations and rising cyber threats. AI/ML model development and maintenance, plus RPA-driven process automation, target lower handling costs and faster claims and credit decisions.
Coface relies on dedicated underwriting, analytics, claims and legal teams to manage credit risk, supported by about 4,300 employees and operations in 100+ countries (2023); ongoing training and certifications preserve standards while regional and sector specialists raise decision accuracy. Compensation structures link variable pay to portfolio risk outcomes to incentivize loss control.
Compliance, audits and multi-jurisdictional reporting drive recurring legal and operations costs for Coface, with solvency capital requirements remaining material—Coface reported a Solvency II ratio of 217% in 2024—while regulatory charges and supervisory fees compress ROE. Reinsurance premiums and broker fees reduce net written premium and are a predictable line item in expense forecasts.
Indemnity payouts are Coface’s largest variable cost; gross written premiums were €1.9bn in 2024 and Solvency II ratio 217% (2024). Distribution costs (commissions) and reinsurance materially reduce net premium; ~4,300 employees across 100+ countries drive ops and training spend. 2024 tech and data investments target automation to lower handling costs and CAC.
| Metric | 2024 |
|---|---|
| GWP | €1.9bn |
| Solvency II | 217% |
| Employees | ~4,300 |
| Countries | 100+ |
Core income derives from whole-turnover and single-risk policies, with premiums in 2024 totaling €1.9bn; pricing reflects exposure, risk grade and loss experience. Policies include minimum premiums and adjustable-declaration clauses to protect margin. Multi-year programs and portfolio diversification enhance revenue visibility and reduce volatility. Underwriting discipline and pricing for loss history drive renewal economics.
Coface monetizes information subscriptions via recurring fees for company reports, credit ratings and APIs, supporting its 2024 group revenues of €1.7bn. Plans are tiered from SMEs to global enterprises with volume discounts, while usage-based pricing targets high-volume clients. Sales teams actively cross-sell subscriptions into trade credit insurance and risk mitigation packages.
Coface charges contingency-based fees (industry 2024 ranges 15–30%) on successful recoveries, aligning incentives with client outcomes. Fixed fees cover pre-legal actions and dunning to ensure predictable cashflow. Legal pass-through costs are billed separately with success premiums for complex cases. This fee mix enhances total client value by balancing risk-sharing, transparency, and recovery efficiency.
Reinsurance and co-insurance arrangements generate income from fronting and coinsurance participations, complemented by fee-based underwriting and administration services; Coface reported group revenues near €2.5bn in 2024, with reinsurance contributing an increasing share to net income and capital efficiency.
Core revenue from premiums reached €1.9bn in 2024, driven by whole-turnover and single-risk policies with risk-based pricing and minimum premiums. Recurring info subscriptions and APIs supported group revenues of €1.7bn in 2024. Recovery fees (15–30% industry range) and surety/guarantee fees and reinsurance participations diversify income and improve capital efficiency.
| Stream | 2024 figure |
|---|---|
| Premiums | €1.9bn |
| Group revenues | €1.7bn |
| Recovery fee range | 15–30% |


