
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
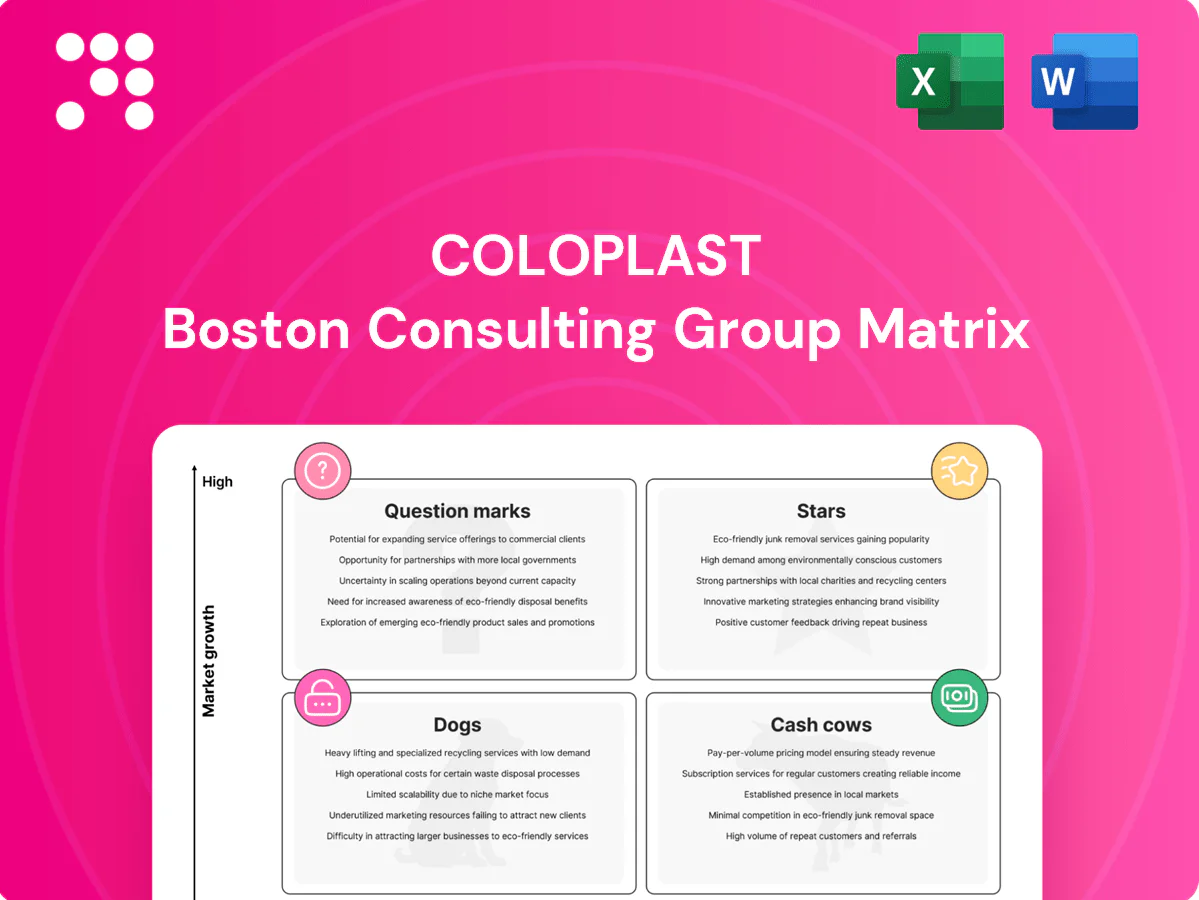
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick look: Coloplast’s BCG Matrix snapshot shows which product lines are winning market share and which are burning cash — a must-see if you manage portfolio strategy. Want the full picture with quadrant placements, data-backed moves, and clear ROI priorities? Purchase the complete BCG Matrix for a detailed Word report + an Excel summary you can use in meetings right away. Buy now and skip the guesswork.
Ostomy care is a Star for Coloplast with high share in a steadily expanding chronic-care market—global 65+ population passed ~10% in 2022 and continues rising, supporting demand; industry estimates put ostomy-care CAGR near 6% in 2024. Strong clinician and user brand preference sustains share, but growth requires continued investment in education and placement. Cash in equals cash out most quarters due to ongoing promotion and service; keep the foot down—this engine can scale into a larger cash generator.
Coloplasts premium continence catheter lines are Stars with top-tier share in intermittent catheters, driven by a secular shift to safer, user-friendly tech and rising home-based care and subscription adoption. Demand growth favors recurring revenue but mandates ongoing clinical engagement and sampling budgets to sustain uptake. High-growth investment strains cash, yet defending share is strategically justified; nurture to reach Cash Cow status.
Interventional urology sits in Coloplasts BCG Stars: minimally invasive stone and BPH procedural devices captured accelerating share as the global market expanded ~9% in 2024, pushing strong revenue momentum but heightening competition. New launches require significant capex and expanded sales force; marketing and evidence generation consumed a material portion of growth investment in 2024. Invest now to lock leadership before adoption flattens.
Advanced dressings like Biatain-level foam are Stars for Coloplast: solid share in 2024 as advanced wound care grew about 6% year-on-year and payers prioritize outcome-based products, enabling foam to outgrow basic dressings. Hospital-to-home shifts lifted outpatient wound volumes (≈15% increase in 2024), but require ongoing clinical evidence and training. High growth drives higher spend on trials, KOL engagement and access initiatives; continued investment is needed to cement leadership and transition to Cash Cow.
Integrated homecare services drive recurring supply and nurse support that increase retention and channel share as homecare formalizes; the global home healthcare market is growing at roughly 7% CAGR (2024 estimates), making scale via digital onboarding vital. Onboarding and logistics require upfront cash burn, but rising adoption pushes lifetime value above acquisition cost within 12–24 months. Push geographic coverage and keep the service flywheel spinning to capitalize on recurring revenue.
Stars: ostomy, continence catheters, interventional urology, advanced dressings, homecare services — high share in 2024 with growth: ostomy ~6% CAGR, continence recurring revenue growth ~6%+, interventional urology ~9% y/y, wound care ~6% y/y, homecare ~7% CAGR; require ongoing clinical, sales and onboarding investment to scale to Cash Cow.
| BU | 2024 growth | Share | Key invest | Payback |
|---|---|---|---|---|
| Ostomy | ~6% CAGR | High | Training | 24–36m |
| Catheters | ~6%+ | Top | Sampling | 12–24m |
| Urology | ~9% y/y | Growing | Launch/force | 24–36m |
| Dressings | ~6% y/y | Solid | Evidence | 18–30m |
| Homecare | ~7% CAGR | Expanding | Digital/onboard | 12–24m |
 Detailed Word Document
BCG analysis of Coloplast products: identifies Stars, Cash Cows, Question Marks, Dogs with investment, divestment and trend-driven recommendations.

 Customizable Excel Spreadsheet
One-page Coloplast BCG Matrix pinpointing product pain points and prioritizing fixes for faster relief.
Core ostomy base SKUs sit in mature segments with dominant share—Coloplast is a global leader in ostomy care and the global ostomy market was estimated at about 5.0 billion USD in 2024—driven by predictable reorder cycles and high customer stickiness. Low incremental marketing and manufacturing efficiencies keep gross margins healthy, typically outpacing less-mature portfolios. These SKUs generate steady cash flow to fund growth bets; focus remains on maintaining quality, optimizing cost, and milking responsibly.
Established continence lines in mature markets deliver reliable cash flows thanks to stable contracts, sticky users and high compliance, allowing predictable margins and low churn. Growth is modest so promotional and placement spend remains tight while scale and procurement discipline widen margins. Surplus cash is deployed to underwrite new platform launches and targeted R&D to extend lifetime value.
Adhesives, barrier rings, and accessories are high-attachment consumables with loyal usage patterns and limited innovation cycles; in 2024 they remained low-growth but high-repeat-purchase drivers that underpin Coloplast’s recurring revenue base. These items deliver strong contribution margins and, with minimal marketing spend, keep the cash net positive for the company. Quietly, they fund R&D and growth initiatives across the portfolio while supporting stable cash flow and operational leverage.
Skin care protectants in existing channels are a mature niche with entrenched clinical protocols and steady demand in 2024, delivering predictable cash flow and limited year-on-year growth pressure.
While price pressure persists, scale, formulary presence and distribution agreements sustain healthy margins and profitability without heavy promotional spend.
Optimize product mix, protect institutional contracts, and allocate surplus cash to higher-growth initiatives while maintaining supply reliability.
Aftercare programs are operationally efficient and proven to reduce churn, acting as low-cost revenue insurance; Bain reports a 5% retention lift can raise profits 25–95%. Growth is slow but impact on lifetime value is high. Ongoing costs are modest versus the cash they safeguard, since retention typically costs far less than acquisition. Maintain and refine—don’t overspend.
Core ostomy, continence and consumable SKUs are mature, high-share cash cows delivering steady, high-margin recurring cash (global ostomy market ~5.0 billion USD in 2024). Low promo cost and institutional contracts preserve margins while funding R&D and growth bets. Retention programs (Bain: 5% lift → profit +25–95%) protect CLV cost-effectively.
| Product | Role | 2024 metric |
|---|---|---|
| Ostomy SKUs | Cash cow | Market ~$5.0B |
| Consumables | Repeat revenue | High margin, low promo |
The file you’re previewing is the exact Coloplast BCG Matrix report you’ll receive after purchase. No watermarks, no placeholders—just the fully formatted, analysis-ready document. It’s crafted for strategic clarity and arrives ready to edit, print, or present to your team. Buy once, download instantly, no surprises or extra steps.
Legacy low-tech wound dressings sit in a commoditized, price-driven tender environment with eroding margins; the global wound care sector's growth slowed to ~3% CAGR by 2024, intensifying price pressure. With low growth and a shrinking share, these units trap resources while turnarounds are costly and often fail to stick. Prune or exit to free up cash for higher-return segments.
Markets are shifting to silicone and premium-coated catheters, leaving older latex variants with low share and stagnant growth as they consistently lose tender bids. Upgrades and ad hoc coating fixes have increased production costs without driving volume, pushing these SKUs to cash breakeven at best. Immediate SKU rationalization and redeployment of manufacturing and R&D resources is required to stem losses and focus on high-margin premium lines.
Small niche SKUs tie up capital in inventory and regulatory upkeep: long-tail SKUs often represent >20% of a medtech SKU base while contributing <5% of revenue, stressing working capital and compliance budgets. Sales coverage can’t justify the overhead given low call frequency and sell-through, reducing strategic leverage versus core portfolios. Sunset or bundle selectively to clear the deck and reallocate resources to higher-yield lines.
Hospital-only items are losing tenders to integrated bundles offered by larger rivals, driving share declines and margin-eroding discounting; growth is flat-to-negative and clinical customers prefer bundled services over standalone products. Divestment or partnership is recommended rather than chasing low-margin contracts that damage long-term profitability.
Geographies with persistent reimbursement cuts have pushed Coloplast below commercial hurdle rates as chronic pricing pressure and slow approvals erode margins; market share remains thin, growth is effectively absent, and service costs continue to linger.
Cash is increasingly trapped in difficult operations; recommended response is to scale back to a service-light footprint or pursue exit in affected markets to stop value destruction.
Legacy wound and latex catheter SKUs sit in low-growth (~3% CAGR by 2024) commoditized markets, losing tenders and yielding margins near cash‑breakeven. Long‑tail SKUs (>20% of base, <5% revenue) trap inventory and compliance spend. Recommend SKU rationalization, divest/partner in hospital bundles, and redeploy capex to premium coated/silicone lines.
| Metric | 2024 | Action |
|---|---|---|
| Market growth | ~3% CAGR | Exit/limit |
| SKU concentration | >20% SKUs, <5% rev | Prune |
| Margins | ≈cash‑breakeven | Redeploy |
Sensor-enabled ostomy monitoring sits in a high-growth digital-health niche addressing a clear unmet need: the global ostomy devices market was ~USD 2.2bn in 2023 while digital health growth exceeds mid-teens CAGR, yet sensor solutions hold only early share. Development, clinical trials, and EHR integration are cash-intensive and can strain margins. If clinical adoption and reimbursement follow, the product can flip to a Star quickly; recommend a focused bet with defined milestones or a fast cut.
Usage of digital continence apps and telehealth is rising as payers warm to remote care, with 2024 surveys showing roughly 60% of payers increasing coverage for remote services; revenue models remain nascent and unit monetization is unproven. Customer acquisition and compliance work burn cash upfront, often requiring 12–18 months of investment before signal. If the solution drives device pull-through and >3x lifetime value vs cost-to-acquire, it scales; invest to validate monetization, then double down or divest.
Antimicrobial/biologic advanced dressings sit as a Question Mark: clinical promise and favorable 2024 reimbursement trends support uptake, but market share is uncertain amid fierce competitors; the global advanced wound care market was ~USD 10B in 2024 with ~5–6% CAGR. Evidence generation and access typically require selective investments—bench-to-clinic programs often cost USD 1–3M—so fund around the strongest indication claims; winning indications converts the asset into a Star.
US expansion in ambulatory urology is a Question Mark: attractive growth runway given a 65+ population of about 58 million in 2024, but Coloplast’s local share is low versus entrenched device and service incumbents; building sales coverage and clinical evidence will require significant time and capital. Early wins in focused regions can unlock scale; pivot if traction stalls.
Direct-to-home in emerging markets: demand rising as mobile and logistics infrastructure improve, but Coloplast brand share remains nascent; initial pilots in 2024 show high customer acquisition and education costs with regulatory onboarding driving cash burn, while lifetime value per ostomy/wound-care patient remains compelling if retention exceeds 12–18 months.
Sensor-enabled ostomy and digital continence products are Question Marks: high-growth markets (ostomy devices ~USD 2.2bn 2023; advanced wound care ~USD 10bn 2024; digital health mid-teens CAGR) but require cash-heavy evidence, sales and regulatory spends (bench-to-clinic USD 1–3M; CAC payback 12–18 months). Invest selectively: require LTV/CAC >3 or divest.
| Asset | Market (2023/24) | Key metric | Trigger |
|---|---|---|---|
| Sensor ostomy | USD 2.2bn (2023) | CAC payback 12–18m | Clinical + reimbursement signal |
| Advanced dressings | USD 10bn (2024) | Bench-to-clinic 1–3M | Winning indication |


