
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Comerica's Porter’s Five Forces snapshot highlights competitive intensity across regional banking—buyer bargaining, supplier and capital constraints, threats from fintech entrants, and substitute products shaping margins. This brief flags strategic risks and growth levers for management and investors. Unlock the full Porter’s Five Forces Analysis to explore Comerica’s competitive dynamics, market pressures, and strategic advantages in detail.
Comerica supplements deposits with FHLB lines, brokered CDs and capital‑markets funding, giving those suppliers pricing and covenant leverage; with the fed funds target at 5.25–5.50% in 2024, spreads and issuance costs rose. During tight liquidity windows spreads widen and terms toughen, lifting cost of funds and pressuring margins. Diversifying maturities and holding strong ratings mitigates reliance, but supplier power spikes in stress periods. Liquidity regulation (e.g., GSIB/LCR focus) further elevates these counterparties’ importance.
Core banking vendors for regional banks like Comerica (FIS, Fiserv, Jack Henry) plus concentrated cloud providers (AWS 32%, Azure 23%, GCP 10% in 2024) and dominant card networks (Visa+Mastercard ~80% of card volume) raise switching costs via contract lock-ins, integration complexity, and compliance burdens. Vendors can affect roadmaps, pricing, and SLAs. Co-development and multi-vendor architectures lower single-vendor dependence.
Households and small businesses supply Comerica with low-cost, fragmented deposits, limiting individual bargaining power, while large corporate and municipal depositors can negotiate preferential rates and services. Rate competition sharpened in 2023–2024 as the federal funds rate rose to 5.25–5.50%, shifting leverage toward depositors. Relationship banking and cash-management offerings help Comerica retain balances and mitigate outflows.
Skilled relationship managers and scarce risk, cyber, and regulatory professionals push wage pressure higher; US unemployment averaged about 3.7% in 2024, tightening labor supply and elevating supplier power for talent. Rising compliance demands and tighter labor markets increase hiring costs and attrition risk, which can degrade service quality and constrain growth. Training pipelines and retention incentives partially mitigate scarcity but raise operating expense.
Card networks, ACH and real-time rails and custodians are essential infrastructure with few substitutes: Visa and Mastercard account for over 80% of U.S. card volume, FedNow went live in 2023 and top custodians hold tens of trillions in assets under custody. Fee schedules and rule changes materially affect Comerica’s economics and product design. Network access rules force ongoing compliance and tech investment, while scale-based pricing favors the largest banks and pressures midsize peers.
Comerica faces elevated supplier power: wholesale funding (FHLB, brokered CDs) tightened as fed funds hit 5.25–5.50% in 2024, lifting cost of funds and covenant leverage; vendor lock‑ins (FIS/Fiserv/Jack Henry) and concentrated cloud (AWS 32%, Azure 23%, GCP 10% 2024) raise switching costs. Large depositors and card networks (Visa+Mastercard ≈80%) extract pricing concessions; talent scarcity (US unemployment ~3.7% 2024) raises wage pressure.
| Metric | 2024 |
|---|---|
| Fed funds | 5.25–5.50% |
| AWS market share | 32% |
| Visa+MC share | ≈80% |
| Unemployment | ~3.7% |
 Detailed Word Document
Tailored Porter’s Five Forces analysis for Comerica that uncovers key competitive drivers, customer and supplier influence, entry barriers, substitutes and disruptive threats, with strategic commentary and editable output for investor reports, internal strategy decks, or academic use.

 Customizable Excel Spreadsheet
A concise Comerica Porter's Five Forces one-sheet that visualizes competitive pressure with an editable spider chart, ready to drop into pitch decks or boardroom slides—no macros or complex code, easily swap in your own data and scenarios for rapid, actionable strategy decisions.
Corporate and middle-market clients frequently multi-bank and run RFPs, intensifying price and term competition; Comerica reported about $39.3 billion in commercial loans in 2024, underscoring the scale at stake. These clients remain rate-sensitive on loans and deposits and demand integrated treasury solutions. Bundling and superior service can blunt customer power, but large clients retain strong negotiating leverage. Credit appetite cycles in 2024 shifted bargaining dynamics as underwriting tightened.
Retail customers can instantly compare Comerica rates and fees using digital tools, and with over 200 million U.S. mobile banking users in 2024, transparency and customer bargaining power have risen sharply. Account portability via ACH, Zelle and fintech front-ends lowers switching friction, while convenient branches and strong digital UX boost loyalty. Rate chasers still move quickly, but targeted rewards and personalized advice can materially reduce churn.
Wealth and institutional Comerica clients with high balances exert strong bargaining power, negotiating fees, mandates, and investment spreads. Passive products now account for roughly half of US mutual fund and ETF assets, and rising robo adoption compresses fees and strengthens buyer leverage. Performance, platform breadth, and fiduciary capabilities remain key differentiators, while bespoke planning and trust services allow Comerica to justify premium pricing.
Treasury management users exert moderate-high bargaining power: integrations make Comerica sticky, yet 2024 AFP survey shows 76% of corporates standardize requirements and run RFPs, forcing price competition. Demand for APIs/interoperability raises expectations for customization without premiums; cross-sell depth and strong fraud controls (top renewal driver) offset discounting.
Comerica’s concentration in five core states — Texas, Michigan, California, Arizona and Florida — exposes it to localized competition and client bargaining dynamics; in hot metros rival banks often push pricing by tens of basis points to win marquee clients. Regional economic shifts (energy and auto cycles in TX and MI) can quickly alter client leverage on pricing and covenants. Diversifying across sectors and metros reduces this geographic bargaining risk.
Corporate, middle-market and treasury clients exert high bargaining power via multi-bank RFPs and rate sensitivity; Comerica held about $39.3B in commercial loans in 2024. Retail customers gain transparency from ~200M US mobile banking users (2024), raising switching risk. Wealth/institutional clients demand fee compression as passive products hit ~50% of US fund assets.
| Segment | Power | Key stats (2024) |
|---|---|---|
| Commercial | High | $39.3B loans |
| Retail | Moderate-High | ~200M mobile users |
| Wealth | High | Passive ≈50% assets |
| Treasury | Moderate-High | 76% RFP (AFP) |
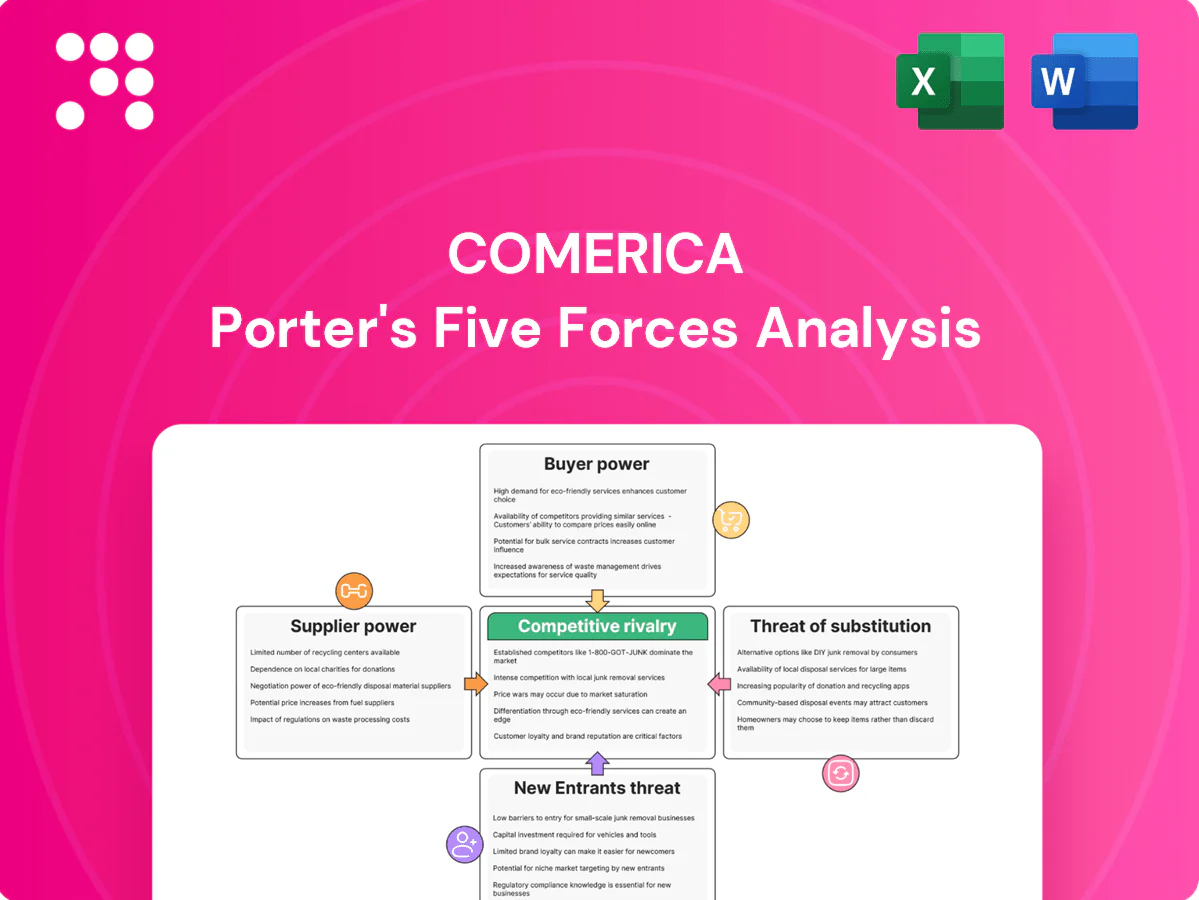
This preview is the complete Comerica Porter's Five Forces Analysis and exactly matches the file you'll receive upon purchase. It includes the full assessment of competitive rivalry, buyer and supplier power, threats of entry and substitution, and strategic implications. No placeholders—download-ready and professionally formatted.
Rivalry with peers like PNC, Fifth Third, Key, and Truist is intense across loans, deposits and treasury, with peers holding hundreds of billions in assets versus Comerica’s tens of billions in 2024. Similar product sets force competition on rate, deal structure and service levels. Relationship depth and industry specialization—commercial real estate, energy, technology—are key battlegrounds. Ongoing M&A among peers can shift market share rapidly.
Large money-center and super-regional banks (JPMorgan ~$3.9T, Bank of America ~$3.0T, Wells Fargo ~$1.9T in total assets, 2024) leverage scale, brand, and tech to penetrate Comerica’s markets and can underprice or bundle services across broader platforms. Their multi-billion-dollar digital and analytics investments raise CX expectations, forcing Comerica to differentiate through agility, relationship banking, and local credit decisioning.
Local credit unions and community banks compete on price and personalized service in retail and small business, with US credit unions holding about $2.1 trillion in assets in 2024 and roughly 4,500 community banks nationwide. Tax-exempt status of credit unions sharpens pricing pressure. Deep local knowledge and community ties raise retention risk for Comerica. Comerica offsets with broader product breadth, treasury capabilities and ~95.6B assets (2024).
Fintechs target payments, SMB lending and cash management with slick UX and speed, capturing roughly 30% of SMB payments volume while SMB fintech lending grew about 22% in 2024. Nonbank lenders and private credit (AUM ~1.6tn in 2024) compete on underwriting flexibility and sub-48 hour turnaround. Partnerships can both mitigate and intensify rivalry. Data-driven pricing pressures traditional margins.
Core banking products are commoditized and published rates are highly transparent, fueling price-based rivalry; in 2024 an estimated 72% of consumers reportedly compared rates online, increasing pressure on margins. Switching costs remain moderate for retail customers but higher for commercial clients, though API-driven integrations are improving portability. Service reliability and risk appetite now act as crucial differentiators as cyclical credit conditions amplify competition.
Competition is intense: regional peers and money-centers (JPM ~$3.9T, BofA ~$3.0T, Wells ~$1.9T; Comerica ~$95.6B in 2024) compete on rates, structure and service, while credit unions ($2.1T assets) and community banks pressure pricing. Fintechs hold ~30% SMB payments share and SMB lending grew ~22% in 2024; private credit AUM ~1.6T. Transparent rates (72% compare online, 2024) amplify margin pressure.
| Segment | 2024 metric |
|---|---|
| Comerica assets | $95.6B |
| Top banks (JPM/BoA/WF) | $3.9T/$3.0T/$1.9T |
| Credit unions | $2.1T |
| Fintech SMB payments | 30% share |
| SMB fintech lending growth | 22% |
| Private credit AUM | $1.6T |
| Consumers comparing rates | 72% |
Rising yields made MMFs and T-bills compelling alternatives to bank deposits in 2024, with 3-month T-bills near 5.5% and MMF assets topping $5 trillion, intensifying competition for Comerica deposits. Broker sweep programs and brokerage links enable instant cash shifts, increasing deposit volatility and pressuring deposit betas and NIM. Offering ICS-like swept, fully insured solutions and competitive retail business rates can reduce outflows and stabilize core deposits.
Direct lenders, BDCs and fintech platforms are substituting bank term loans and revolvers by offering faster execution and flexible structures at higher cost; private credit AUM reached about $1.3 trillion in 2024 (Preqin). Borrowers increasingly trade price for certainty and bespoke covenants. Banks must win on advisory, ancillary services and total-relationship value to retain origination share.
Digital wallets and RTP networks cut reliance on checking-based payments as global digital wallet users reached 5.2 billion in 2024, driving merchant and consumer preference for low-cost, instant options. This shift can erode interchange income and deposit balances for banks. Embedding real-time rails and value-added services helps retain transaction and deposit activity.
Automated portfolios and zero-commission platforms (robo AUM ~1.5 trillion in 2024) increasingly substitute Comerica’s traditional wealth offerings, accelerating fee compression and transparency that shift clients away from full-service models. Median retail advisory fees near ~0.50% in 2024, intensifying margin pressure. Hybrid advice and planning defend complex, high-net-worth segments while differentiation via trust, estate and bespoke credit is essential to retain clients.
Platforms now embed payments, lending and insurance at point-of-need, routing customers around traditional Comerica channels.
Buy-now-pay-later and merchant financing have become direct substitutes for cards and small loans, with BNPL global GMV exceeding 300 billion USD in 2024.
Data ownership and superior UX on platforms create strong customer lock-in, though bank-as-a-service and partnerships let banks capture fee flows.
Higher-yield substitutes eroded Comerica deposits and fee pools in 2024: MMF assets ~$5T and 3‑month T‑bills ~5.5% drove flows; private credit AUM ~$1.3T and robo AUM ~$1.5T compressed loan and wealth share while digital wallets (5.2B users) and BNPL (~$300B GMV) shifted payments and small-credit activity; ICS-like sweeps, real‑time rails and hybrid advice mitigate losses.
| Metric | 2024 Value |
|---|---|
| MMF assets | $5T |
| 3M T‑bills | ~5.5% |
| Private credit AUM | $1.3T |
| Robo AUM | $1.5T |
| Digital wallet users | 5.2B |
| BNPL GMV | $300B |
Bank charters, capital requirements and supervisory scrutiny raise high entry costs: Basel III sets CET1 at 4.5% plus a 2.5% capital conservation buffer (effective CET1 ~7%), Tier 1 and total capital minima of 6% and 8%, and a 3% leverage floor, deterring de novo entrants; building compliance and risk infrastructure is capital- and staff-intensive, protecting full-service incumbents like Comerica. Niche entrants often sidestep charters via bank partnerships.
Fintechs launch bank-like products via sponsor-bank models (eg, Chime with The Bancorp), bypassing charter hurdles and rapidly scaling customer-facing services with modern UX and low onboarding friction.
They retain front-end economics—fee income, interchange, customer data—even while relying on incumbent balance-sheet functions, creating risk of channel displacement for Comerica unless it partners or competes effectively.
Branch-light digital-only banks cut fixed costs and can underprice incumbents, illustrated by Chime’s growth to roughly 12 million US customers by 2023–24. Customer acquisition remains costly, with reported CACs for neobanks commonly hundreds of dollars, but niche segments can be won through superior UX and lower friction. Access to FDIC-insured deposits via partner banks lowers regulatory barriers to entry. Scale and incumbent trust still slow expansion, raising churn and funding pressures.
Cloud platforms (AWS ~32% share in 2024), open APIs, and banking-as-a-service stacks cut build times from months to weeks, letting fintechs and challengers launch niche products rapidly. Modular stacks enable rapid experimentation, lowering barriers in payments, lending, and embedded finance where BaaS adoption surged in 2024. Incumbents must accelerate product iteration and partnerships to maintain lead.
Tight funding and higher rates raise entrant cost of capital, limiting sustainable growth and scale for new banks; the federal funds rate stayed at about 5.25–5.50% through 2024, keeping borrowing expensive and deterring capital‑intensive entrants. In periods of easy liquidity entrants proliferate and undercut pricing, so cyclical shifts directly modulate entry threat, while Comerica’s strong balance sheet and diversified deposit base buffer incumbents.
Regulatory capital (CET1 ~7%) and supervision keep de novo entry costly. Fintechs use sponsor-bank/BaaS (Chime ~12m) and cloud/APIs (AWS ~32% 2024) to launch fast. 2024 fed funds ~5.25–5.50% raises capital costs, limiting sustainable entrant scale.
| Metric | Value |
|---|---|
| CET1 | ~7% |
| Chime users | ~12m |
| AWS share | ~32% (2024) |
| Fed funds | 5.25–5.50% (2024) |


