
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Cover political, economic, social, technology, legal and environmental change.
Separate market signals from their business impact.
Create a structured view of opportunities and exposure.
Gain a competitive edge with our PESTLE Analysis tailored to We.Connect—three concise sections revealing political, economic, social, technological, legal, and environmental forces shaping its future. Use these insights to anticipate risks, pinpoint growth opportunities, and strengthen strategic plans. Purchase the full, ready-to-use report for immediate access to actionable intelligence and editable templates.
As an EU-based distributor WE.CONNECT benefits from tariff-free movement within the single market (0% intra-EU tariffs), but shifts in EU trade relations with major partners matter: EU goods trade with China was about €650bn in 2023, so tariffs or supply-chain frictions can raise component costs and reduce sourcing options. Anti-dumping duties on certain electronics can exceed 30% in cases, so monitoring EU trade negotiations is essential for accurate cost planning.
French industrial and digital policy—notably France 2030 (€54bn) and EU Digital Europe (€7.5bn 2021–27)—boosts enterprise IT spending and reindustrialization incentives. Public procurement (~€250bn/year) often favors local or EU-certified suppliers. Shifts in cloud, cybersecurity and edtech subsidies can redirect demand, and engagement with government programs opens B2B procurement channels.
Geopolitical tensions in semiconductor hubs like Taiwan, which supplies roughly 55% of global foundry capacity and over 90% of sub-7nm production, can lengthen lead times and drive up prices. Export controls on chips and equipment (expanded 2022–24) have constrained availability for some markets, raising input costs. Political unrest near key shipping lanes increases logistics premiums; diversifying suppliers reduces this exposure.
Local authorities in France—about 35,000 communes and 18 regions—direct procurement for schools, municipalities and hospitals, creating strong regional control over tenders. Decentralized budgets produce uneven regional demand across territories. Political turnover often delays tenders or shifts specifications; building regional reseller partnerships helps smooth revenue fluctuations.
EU energy policy raises manufacturing and distribution costs for energy-intensive components as the EU ETS averaged about €95/t CO2 in 2024, increasing input prices; incentives for energy-efficient products (tax breaks, grants) are reshaping portfolio choices toward low-energy designs. Political drive for strategic autonomy (e.g., Chips Act funding ~€43bn) favors EU-origin products and improves eligibility in public bids.
EU tariff-free single market aids WE.CONNECT but EU-China trade (€650bn 2023) and anti-dumping duties (up to 30%+) can raise component costs. France/EU programs (France 2030 €54bn, Digital Europe €7.5bn) and public procurement (~€250bn/yr) drive demand for local-certified suppliers. Semiconductor supply risk (Taiwan ≈55% foundry, >90% sub-7nm) and EU ETS (~€95/t CO2 2024) raise input prices.
| Metric | Value |
|---|---|
| EU–China trade | €650bn (2023) |
| Public procurement | €250bn/yr |
| EU ETS price | €95/t (2024) |
| Chips Act | €43bn |
| Foundry share (Taiwan) | ≈55% global |
 Detailed Word Document
Explores how political, economic, social, technological, environmental, and legal forces uniquely affect We.Connect, with each category expanded into actionable sub-points and examples specific to its industry and region. Backed by current data and forward‑looking insights, the analysis supports executives and investors in identifying threats, opportunities, and scenario-based strategic responses.

 Customizable Excel Spreadsheet
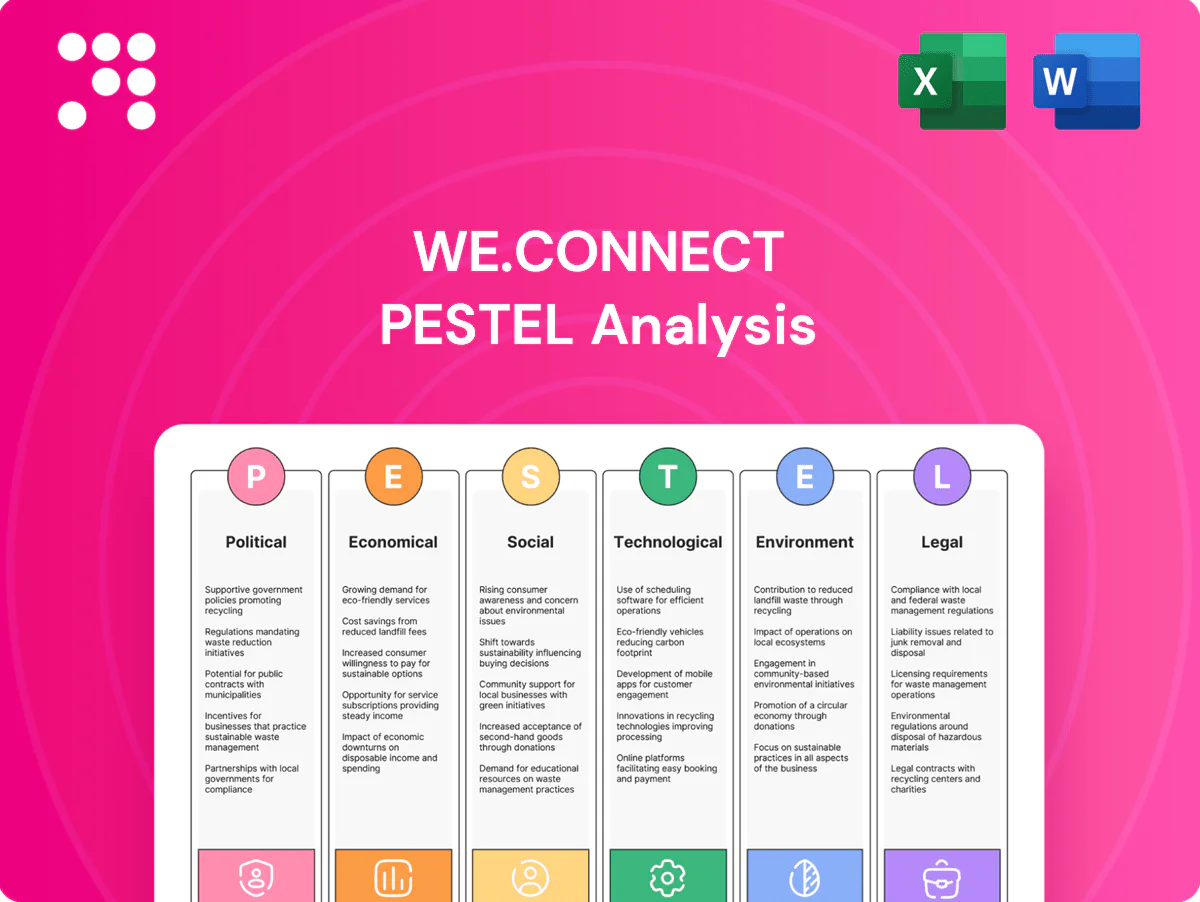
We.Connect's PESTLE delivers a clean, summarized version of the full analysis, visually segmented by PESTLE categories for quick interpretation and easily dropped into presentations or shared across teams for fast alignment.
Professional IT spending in France closely tracks GDP and business confidence, with INSEE business climate hovering around the 100 neutral mark through 2024, so slowdowns typically defer hardware refreshes while expansions accelerate upgrades.
Public sector budgets, with total government spending near 55% of GDP (OECD), can cushion downturns by front-loading procurement and maintenance contracts.
Forecasting replacement cycles and aligning contracts to multi-year public programs stabilizes revenue and reduces volatility for We.Connect during macro cycles.
Input costs for electronics are commonly priced in USD while We.Connect sells predominantly in EUR, and EUR/USD traded roughly 1.03–1.12 across 2024–H1 2025, creating material FX margin risk if unhedged. FX swings directly compress gross margins unless hedging programs are in place. Component price inflation in 2024 averaged mid-single digits for semiconductors, requiring agile pricing and SKU mix optimization. Transparent surcharges and contract clauses preserve customer relationships.
Semiconductor shortages or gluts rapidly propagate to PC, monitor and storage supply, driving volatile product availability and pricing; lead times swung from over 20 weeks in 2021 to roughly 12 weeks by mid-2024, amplifying inventory carrying costs. Allocation practices during tight cycles favor large OEMs, squeezing smaller distributors' margins and fill rates. Strategic inventory buffers and vendor capacity commitments are essential to stabilize supply and service levels.
Enterprise buyers increasingly emphasize lifecycle costs—energy consumption and maintenance—when procuring hardware; Gartner 2024 reports 62% of procurement leaders rank TCO above purchase price. Economic evaluations favor durable, energy-efficient equipment that reduces operating spend over typical 5–7 year lifecycles. Bundled warranties and managed services shift procurement conversations from price to value, while clear TCO documentation materially aids deal conversion.
IT spend tracks GDP/INSEE ~100 so cycles shift refresh timing; public spend ~55% GDP cushions demand; EUR/USD traded 1.03–1.12 (2024–H1 2025) creating FX margin risk; semiconductor lead times ~12 weeks (mid‑2024) and TCO now top priority (62% procurement leaders, Gartner 2024).
| Metric | Value |
|---|---|
| INSEE business climate | ~100 (2024) |
| Govt spending | ~55% GDP (OECD) |
| EUR/USD | 1.03–1.12 (2024–H1 2025) |
| Semiconductor lead time | ~12 weeks (mid‑2024) |
| TCO priority | 62% (Gartner 2024) |
The preview of the We.Connect PESTLE Analysis shown here is the exact document you’ll receive after purchase—fully formatted, professionally structured, and ready to use. This is a real screenshot of the product with no placeholders or teasers. After checkout you’ll instantly download this same finished file and can begin applying the insights right away.
Hybrid work normalization drives demand for monitors, webcams, docks and secure accessories as distributed workforces expand; Microsoft Work Trend Index 2023 reported 53% of workers prefer hybrid arrangements. Corporate policies increasingly standardize home-office kits, with IT budgets shifting to support centralized provisioning and cyclical refresh aligned to collaboration-tool upgrades. Ergonomics and ease-of-deployment now heavily influence SKU selection and TCO.
Schools and training programs need affordable, robust devices as 1 in 3 children lacked reliable home internet access in recent UN/UNICEF estimates; bulk public and NGO tenders often exceed 100,000 units, creating scale opportunities. Durable, easy-to-manage designs can cut total cost of ownership by roughly 25–35% over three years. Tailored education bundles (content, device management, training) can increase long-term account retention by ~20%.
Professional buyers increasingly demand eco-labels and repairability; the EU Ecodesign for Sustainable Products Regulation (ESPR, 2023) embeds durability and repair criteria into procurement. Transparent environmental data now affects RFP scoring and supplier selection. Take-back and refurbishment services boost value propositions as the global refurbished device market is projected to reach about $52bn by 2027. Marketing must emphasize measurable impact metrics.
Heightened awareness of cyber risks is increasing demand for hardware-level security in We.Connect devices, with encrypted storage and secure peripherals now core differentiators; IBM's 2024 Cost of a Data Breach Report cites an average breach cost of 4.45 million USD, underscoring buyer risk aversion. Certifications such as FIPS 140-3 and Common Criteria are often decisive in procurement, and bundling hardware with endpoint management/UEM strengthens trust and supports compliance.
Employees now expect consumer-grade design and plug-and-play performance; 72% of desk-based workers in 2024 said workplace apps must match consumer UX to avoid productivity loss. Low-noise, high-resolution, and eye-care features measurably boost satisfaction and adoption, while poor UX drives higher support tickets and can raise TCO by an estimated 15–25%.
Hybrid work and education access reshape demand toward durable, easy-to-deploy peripherals; 53% prefer hybrid (Microsoft 2023) and 1 in 3 children lacked reliable home internet (UNICEF recent). Sustainability, repairability and hardware security (avg breach cost 4.45M USD, IBM 2024) drive procurement and bundled services.
| Metric | Value |
|---|---|
| Hybrid preference | 53% |
| Children without internet | ≈33% |
| Avg breach cost | 4.45M USD |
Rapid CPU/GPU cycles and display advances can double performance gen-to-gen (NVIDIA cites up to 2x) and TSMC's ~40 billion USD capex in 2024 speeds node rollouts, quickly obsoleting inventory. Portfolio agility is crucial to avoid markdowns and tight refresh windows. Close vendor roadmapping must align launches with client refreshes, while certification and testing capacity, often 6–12 week lead times, must scale accordingly.
On-device AI in webcams, headsets and PCs—enabled by client NPUs such as Intel Core Ultra (introduced 2023) and AMD Ryzen AI (announced 2024)—creates clear upsell paths for premium bundles and subscriptions. Hardware acceleration drives compatibility and support requirements across drivers and firmware, increasing post-sale service needs. Live demos and benchmarks (latency, on-device inference rates) are essential to justify price premiums. Sales teams require targeted training on AI value props and product differentiation.
EU USB-C mandate effective December 2024 accelerates USB-C/Thunderbolt adoption while the Wi‑Fi Alliance launched Wi‑Fi 7 certification in 2023 and Wi‑Fi 6 remains widely deployed. DP 2.0 (announced 2019) and HDMI 2.1 (spec 2017) revisions drive dock and adapter demand and complexity. Backward compatibility gaps raise returns and support costs; published compatibility matrices materially reduce that risk.
Enterprises increasingly require hardware with remote management, firmware update capability and telemetry; 70% of firms list MDM/UEM integration as a buying criterion and the UEM market grew about 12% YoY in 2024. Offering pre-configuration and zero-touch enrollment boosts procurement wins and reduces deployment cost/time. Security-first firmware practices and signed updates cut vulnerability exposure and support compliance with rising IoT/endpoint regulations.
Advanced forecasting and EDI with real-time inventory visibility boost fill rates and can improve forecast accuracy 10–30% and reduce stockouts ~15% (2024 industry averages); API integration with retailers/resellers cuts order-to-cash and accelerates turnover by up to 25%; channel-level SKU analytics raise sell-through 8–12%; end-to-end cyber resilience is mandatory as attacks rose ~38% in 2024.
Rapid silicon cadence (TSMC ~$40B capex 2024) doubles perf gen-to-gen, forcing tight refresh windows and higher obsolescence risk. On-device AI (Intel Core Ultra, AMD Ryzen AI) enables premium bundles but raises support and certification burdens. USB-C mandate (Dec 2024), Wi‑Fi 7 rollout and UEM demand (~12% YoY growth, 2024) shift procurement to managed, secure devices.
| Metric | Value | Impact |
|---|---|---|
| TSMC capex | $40B (2024) | faster node rollouts |
| UEM growth | ~12% YoY (2024) | MDM priority in RFPs |
| Cyber attacks | +38% (2024) | need for signed firmware |
All We.Connect electronics must meet CE marking and related directives under the EU New Legislative Framework and Market Surveillance Regulation (EU) 2019/1020; non-compliance risks recalls, regulatory fines and reputational damage. The EU RAPEX system records over 2,000 product-safety alerts annually, illustrating real enforcement activity. Rigorous testing, technical documentation and supplier audits are mandatory to reduce downstream liability and recall costs.
Devices and services collecting user data must comply with GDPR, which mandates breach notification to authorities within 72 hours and exposes firms to fines up to €20 million or 4% of global turnover. Privacy-by-design in software and firmware is essential to reduce breach risk; IBM's 2024 Cost of a Data Breach Report put the global average breach cost at $4.45 million. Breach reporting and DPA terms materially affect B2B contracts, so clear data controller/processor roles avoid regulatory penalties.
WEEE, RoHS, and REACH impose mandatory controls on hazardous substances and end-of-life take-back, with global e-waste at 57.4 Mt in 2021 and REACH covering roughly 22,000 registered substances as of 2024. Producers must register, report and finance recycling schemes under WEEE and REACH, and RoHS bans key toxins like lead and mercury. Non-compliance can block EU market access; designing for recyclability cuts disposal costs and compliance burdens.
EU antitrust rules shape pricing, rebates and channel policies; undertakings risk fines up to 10% of global turnover for infringements. Selective distribution must be objective and proportionate and can still be lawful where supplier market share is below the 30% VBER threshold. MAP policies need careful design to avoid resale price maintenance. Legal review of partner agreements mitigates exposure and aligns with Commission guidance.
We.Connect must satisfy CE/Market Surveillance (RAPEX >2,000 alerts/yr), WEEE/RoHS/REACH (REACH ≈22,000 substances), GDPR (72h notify; fines ≤€20M or 4% turnover; avg breach cost $4.45M 2024) and EU antitrust (fines ≤10% turnover; VBER 30% threshold).
| Rule | Key figure |
|---|---|
| RAPEX | >2,000 alerts/yr |
| GDPR | €20M / 4% turnover; 72h |
| Avg breach cost | $4.45M (2024) |
| Antitrust | 10% global turnover; 30% VBER |
Buyers increasingly scrutinize product carbon footprints and efficiency ratings; EU public procurement (~14% of GDP) often mandates LCAs or eco-labels for tenders. Energy-efficient monitors and PCs (30–60% lower operational energy vs legacy models) can therefore win bids. Publishing LCAs and recognized labels (ENERGY STAR, EPEAT) verifies claims while design choices drive upstream Scope 3 emissions, which often account for >80% of device lifecycle emissions.
Take-back, refurbishment and recycling programs are becoming mandatory expectations as global e-waste topped 59.7 Mt in 2021 with only ~17% formally recycled, increasing regulatory and reputational risk for We.Connect. Modular, repairable designs cut material costs and lower disposal rates, supporting service margins. Partnerships with certified recyclers ensure compliance and traceability. Circular offerings (trade-in, subscription repairs) can unlock recurring revenue and higher customer LTV.
Reducing plastics and cutting package volume (right-sizing can shrink parcel volume by ~20%) lowers material and freight costs and reduces emissions; consolidated shipments and switching to low-emission carriers can cut logistics CO2e by up to ~30%. Using FSC-certified materials ( ~220 million ha certified globally in 2024) and right-sized boxes improves circularity. Track KPIs: % FSC content, kg packaging per order, CO2e per parcel, and report annually.
Extreme weather increasingly disrupts manufacturing and transport; insured losses from natural catastrophes were about USD 110 billion in 2023, putting upward pressure on 2024–25 premiums and risk pricing. Building buffer stocks and multi-route logistics improves resilience, while supplier climate-risk assessments inform sourcing decisions and can reduce downtime. Rising volatility is driving higher insurance costs for supply-chain exposures.
Regulatory tightening on ESG means EU CSRD and the Taxonomy raise reporting across value chains, extending obligations to roughly 50,000 companies and pressuring suppliers for scope 1–3 data; clients increasingly request emissions figures and targets. Aligning with SBTi (over 5,000 business commitments by 2024) boosts credibility and early compliance can be a clear sales advantage.
Buyers demand low-carbon, efficient devices (30–60% lower ops energy) and verified LCAs/labels; Scope 3 often >80% of lifecycle emissions. E-waste 59.7 Mt (2021) with ~17% recycled raises compliance/reputation risk; circular models boost margins. Extreme weather and insured losses ~USD 110bn (2023) increase premiums; CSRD (~50,000 firms) and SBTi (5,000+ commitments) tighten reporting.
| Metric | Value |
|---|---|
| E-waste (2021) | 59.7 Mt |
| Formal recycling | ~17% |
| Insured losses (2023) | USD 110bn |
| CSRD scope | ~50,000 firms |
| SBTi commitments (2024) | 5,000+ |


