
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Core & Main faces intense rivalry from regional distributors, moderate threat of new entrants due to scale and networks, supplier power limited by specialty manufacturers, strong buyer negotiating leverage, and low substitute threat for essential waterworks products. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Core & Main’s competitive dynamics in detail.
Consolidated OEM base for pipes, valves, hydrants and meters concentrates supplier leverage, with municipal specs frequently naming brands and locking distributors into specific manufacturers; this dynamic tightened margins for distributors during recent supply disruptions in 2024, though multi-year agreements and national accounts helped partially offset OEM pricing power.
Engineer and municipality specifications frequently mandate brand- or material-specific approvals, constraining Core & Main’s ability to swap vendors without costly re-approvals and raising supplier leverage. Suppliers whose products are formally spec’d gain negotiating strength, pressuring margins and terms; Core & Main reported roughly $6.1 billion in 2024 net sales, amplifying exposure to spec risks. Co-engineering and value engineering programs can gradually reduce this rigidity by validating alternative solutions and securing cross-approvals.
Inputs such as ductile iron, steel, copper and PVC/HDPE resin swung with 2024 commodity cycles (steel +12% YTD, copper +8%, PVC resin +18%), allowing suppliers to pass price increases quickly and compress distributor gross margins. Index-based pricing reduces exposure but timing mismatches between index resets and inventory purchases create margin risk. High inventory turns and surcharge mechanisms are critical mitigants to protect margins.
Foundry and resin capacity constraints, coupled with port and trucking bottlenecks, tightened supply in 2024; lead times stretched to roughly 16–24 weeks, prompting OEMs to prioritize high-volume partners and extract pricing concessions. Project schedules force distributors like Core & Main to accept higher costs to secure availability, while demand planning and 2–6 week safety stocks partially mitigate exposure.
Core & Main can deploy private label lines and dual-sourcing to dilute OEM bargaining power, leveraging aggregated national purchasing to secure volume rebates and better terms; Core & Main reported over $6 billion in annual revenue in 2024, strengthening its negotiation leverage. Private label uptake is constrained by spec compliance in municipal and infrastructure projects, so balanced category strategies preserve supplier competition without risking project approvals. Maintaining supplier performance metrics and split-sourcing limits OEM hold while protecting spec-driven sales.
Supplier leverage is high due to consolidated OEMs and municipal specs, pressuring margins despite Core & Main’s $6.1B 2024 net sales; lead times stretched to 16–24 weeks and foundry utilization exceeded 85% in 2024. Commodity price swings (steel +12% YTD, PVC resin +18%) enabled rapid passthroughs, while private-label and dual-sourcing partially mitigate but remain limited by spec approvals.
| Metric | 2024 |
|---|---|
| Net sales | $6.1B |
| Lead times | 16–24 wks |
| Foundry util. | >85% |
| Steel/PVC moves | +12% / +18% |
| Safety stock | 2–6 wks |
 Detailed Word Document
Uncovers key drivers of competition, buyer and supplier power, substitutes, new-entrant risks and rivalry specific to Core & Main, identifying disruptive threats, pricing pressures and protective market dynamics for strategic decision-making.

 Customizable Excel Spreadsheet
A concise one-sheet Porter's Five Forces for Core & Main that maps supplier, buyer, competitor, entrant, and substitute pressures—ideal for quick strategic decisions and board decks. Customizable scores and an instant radar view let you model scenarios without macros and integrate seamlessly into reports or Excel dashboards.
City utilities and private water companies place sizable, recurring orders, driving strong price competition and scale-driven bargaining power for buyers. Formal RFPs and public bid processes, used in roughly all municipal procurements, further enhance buyer leverage in negotiations. Service levels, emergency response capability and local inventory holdings shift negotiations away from pure price; rapid emergency fill rates can command price premiums. Long-term contracts and framework agreements (covering multi-year capital plans amid an estimated US water infrastructure need of about 625 billion over 20 years) stabilize terms for both sides.
Project-based contractors routinely shop quotes across distributors for large projects, driving price sensitivity even as they pay premiums for reliable on-time delivery, takeoffs and fabrication; industry data shows US construction spending topped about $1.9 trillion in 2023 and remained elevated into 2024, keeping procurement intensity high. Switching distributors is feasible but adds coordination and schedule risk, so bundled services that reduce field delays lower churn and justify premium pricing.
Many municipal and utility buyers use approved-vendor lists that narrow procurement options; if Core & Main appears, buyer leverage drops sharply, but exclusion can block access and raise buyer leverage. Core & Main reported approximately $7.1 billion in net sales in 2024, so maintaining approvals and compliance is crucial to defend that share. Proactive technical support and specification input help influence future spec cycles and retain placement.
Digital quoting and marketplaces raise price visibility on commodity SKUs, increasing buyer bargaining power on standard items; Core & Main reported net sales of $5.6 billion in 2024, underscoring scale pressures on margins. Differentiation shifts to logistics reliability, emergency fulfillment, and kitting, while tiered pricing and dynamic availability data can preserve margins.
Core & Main’s value-added services — meter/AMI support, takeoffs, fusion, hydrant assembly — embed the company in municipal and contractor workflows, materially raising switching costs and reducing buyer power; Core & Main reported $8.5 billion in net sales in 2024, reinforcing scale advantages. Emergency response capability and local stocked inventory add further stickiness, while dedicated account management and data integration deepen customer lock-in.
Buyers wield strong price leverage on commodity SKUs via public bids and digital marketplaces, but service, emergency fill and local inventory shift negotiations toward premiums. Long-term contracts and approved-vendor lists stabilize demand and reduce buyer power. Core & Main scale and embedded services raise switching costs, supporting margins amid high procurement intensity.
| Metric | 2024 | Impact |
|---|---|---|
| Core & Main net sales | $8.5B | Scale, approval power |
| US construction spend | $1.9T (2023) | Procurement demand |
| US water need | $625B/20yr | Long-term contracts |
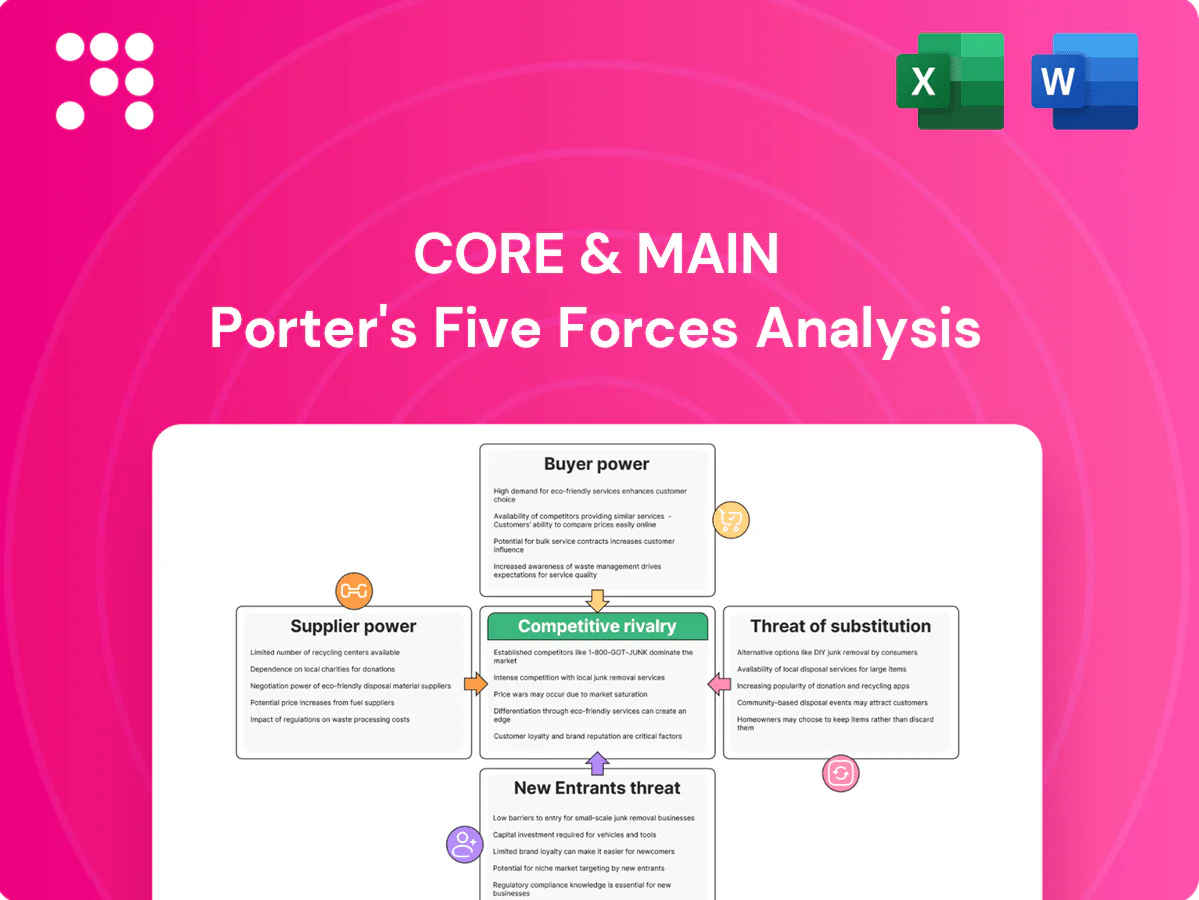
This Core & Main Porter’s Five Forces Analysis preview is the exact, fully formatted document you’ll receive immediately after purchase, with no placeholders or mockups. It contains the complete competitive assessment, supplier and buyer power, barriers to entry, substitute risks, and rivalry analysis. The file is ready for download and use the moment you buy. No surprises—what you see is what you get.
Rivalry is intense as Core & Main (NASDAQ: CNM) faces national players like Ferguson and HD Supply Waterworks alongside strong regionals and independents in 2024. Competition centers on price, product breadth, branch proximity, and service, with consolidation increasing scale but forcing large peers head-to-head. Local relationships and service reputation often decide awards in tight bids.
Service-led differentiation at Core & Main shifts competition from unit price to total cost by bundling fabrication, jobsite staging, meter/AMI solutions and emergency response—critical as US AMI deployments surpassed 35 million meters by 2024. Core & Main’s ~4.0 billion USD revenue and ~470 branches in 2024 show scale enabling widespread value-added services. Investment in technical staff deepens a moat by reducing project cycle time and warranty costs, raising switching costs for customers.
Availability during supply tightness wins projects and loyalty, as firms with stocked SKUs capture time-sensitive bids while competitors miss contract windows; carrying deep, diverse inventory is capital intensive, often representing 20–30% of distributors’ current assets and incurring 20–30% annual carrying costs. Competitors that stock less lose responsiveness but lower capital and obsolescence risk; data-driven replenishment can raise fill rates sustainably and reduce stock levels.
Core & Main operated about 620 branches in 2024, where branch density reduced last-mile cost and improved fill rates, with route density and shared warehousing trimming distribution cost roughly 10–15% and elevating same-day fill performance. Markets with overlapping branches show sharper price competition, and greenfield openings plus M&A activity in 2023–24 intensified regional rivalry.
Back-end rebates, national pricing and project quotes drive Core & Main rivalry; aggressive rebate programs in 2024 pushed distributors to sacrifice margin to secure volume, eroding pricing power while long-term municipal contracts awarded alongside the Bipartisan Infrastructure Law’s water funding sustained share where won.
Rivalry is intense in 2024 with Core & Main (revenue $4.0B; ~620 branches) facing national and regional rivals competing on price, service and proximity; AMI deployments >35M meters shift value to bundled services. Inventory intensity (20–30% of current assets) and rebate-driven margin pressure force scale and fill-rate advantages. Branch density cuts last-mile costs ~10–15%.
| Metric | 2024 |
|---|---|
| Revenue | $4.0B |
| Branches | ~620 |
| AMI meters | >35M |
| Inventory % current assets | 20–30% |
| Last-mile cost cut | 10–15% |
PVC, ductile iron, HDPE, and steel can substitute based on pressure, soil and lifecycle; industry reports show HDPE growing (~5–6% CAGR) while PVC remains volume leader and ductile iron holds value share in high-pressure mains. Shifts alter SKU mix but not total distribution demand, so distributors must stock and support multiple materials to retain relevance. Core & Main’s technical guidance is positioned as solution-agnostic, advising material selection by application and lifecycle cost.
Trenchless rehab methods like CIPP lining, pipe bursting and sliplining can displace new pipe demand, with trenchless solutions accounting for an estimated 35% of sewer rehab projects in mature US markets by 2024; they substitute categories such as PVC and ductile iron while requiring specialized resins, liners and bursting heads. Stocking trenchless consumables—often 15–25% of project spend—protects distributor participation, while advisory capability captures higher-margin rehab budgets and repeat service revenue.
Large projects may attempt factory-direct procurement, but OEMs generally prefer distributor channels for credit, logistics and service; Core & Main reported net sales of $6.1 billion in 2024, underscoring distributor scale. Direct models can bypass distributor margin on select items, yet bundled services, local inventory and field support reduce that substitution risk. Distributors remain entrenched for complex, credit-heavy installs.
Digital marketplaces increasingly substitute basic distributor functions for commodity SKUs, capturing an estimated >20% of small-ticket distributor transactions by 2024; however, complex, spec-driven orders still require expert coordination and technical support. Marketplaces erode pricing but struggle with emergency fulfillment and jobsite staging, where same-day delivery and logistics matter. Integrating e-commerce with value-add services preserves share.
Engineers and contractors increasingly bundle materials with design-build services, reducing demand for standalone distribution channels in 2024 while still relying on dependable sourcing and logistics.
Core & Main can retain a role by partnering on design-build projects, supplying durable procurement and last-mile delivery capabilities.
Offering takeoffs, kitting, and vendor-managed inventory strengthens integrated delivery and preserves margin capture within the value chain.
Substitutes (HDPE, PVC, ductile iron, steel and trenchless rehab) shift SKU mix but rarely eliminate distributor demand; HDPE growing ~5–6% CAGR while trenchless was ~35% of sewer rehab by 2024. Digital marketplaces took >20% of small-ticket orders in 2024, but complex, credit-heavy projects favor distributors like Core & Main (net sales $6.1B, 2024).
| Metric | 2024 |
|---|---|
| Core & Main sales | $6.1B |
| HDPE CAGR | 5–6% |
| Trenchless share | 35% |
| Online small-ticket | >20% |
High working capital—inventory and receivables representing about 25–35% of annual sales in wholesale construction distribution in 2024—deters entrants. Building branch networks, fleets and yards requires millions per region, raising upfront CAPEX. Newcomers without volume face weaker OEM terms and pay 5–15% higher purchase prices. Procurement and logistics scale synergies lower unit costs, raising the entry hurdle.
Entrants must secure top OEM lines and municipal approved-vendor status, with approval cycles typically taking 6–12 months in 2024, delaying revenue generation. Established supplier relationships and brand allocations held by incumbents like Core & Main constrain new entrants’ access to marquee lines. Without recognized brands, bidders lose competitiveness on price and specification, increasing time and cost to win contracts.
Operational complexity—deep technical expertise in fabrication, fusion, and emergency response is hard to replicate, reinforced by the Bipartisan Infrastructure Law allocating 55 billion for water infrastructure upgrades through 2026; stringent safety, compliance, and documentation standards raise entry costs. Integration with customer IT/SCADA systems and execution risk penalize inexperienced entrants, increasing time-to-market and warranty exposure.
Embedded services, extended credit terms, and deep local relationships make Core & Main accounts highly sticky, forcing new entrants to offer steep discounts to win business. Project risk and potential performance penalties restrain trials, so newcomers need reference projects and performance guarantees to compete effectively.
Online-only sellers nibble at commodity SKUs by undercutting overhead; McKinsey 2024 found roughly 70% of B2B buyers use digital channels, accelerating pressure on distributors. Local niche players penetrate municipalities or product lines but lack the service depth and inventory breadth of incumbents. Core & Main and peers counter with expanded e-commerce platforms and specialty teams, blunting most share shifts.
High working capital (25–35% of annual sales in 2024), multi‑million regional CAPEX and 5–15% higher purchase prices deter entrants; procurement and logistics scale widen unit‑cost gap.
OEM/vendor approvals take 6–12 months and incumbents hold allocations; Bipartisan Infrastructure Law funds $55B for water upgrades through 2026 favor established players.
Digital adoption (~70% of B2B buyers use digital channels, McKinsey 2024) pressures commodity SKUs, but online sellers lack service breadth.
| Barrier | 2024 Metric | Impact |
|---|---|---|
| Working capital | 25–35% of sales | High liquidity need |
| CAPEX | Millions per region | High entry cost |
| Supplier terms | 5–15% higher price | Margin disadvantage |
| Approvals | 6–12 months | Delayed revenue |
| Market shift | 70% digital buyers | Commodity pressure |


