
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
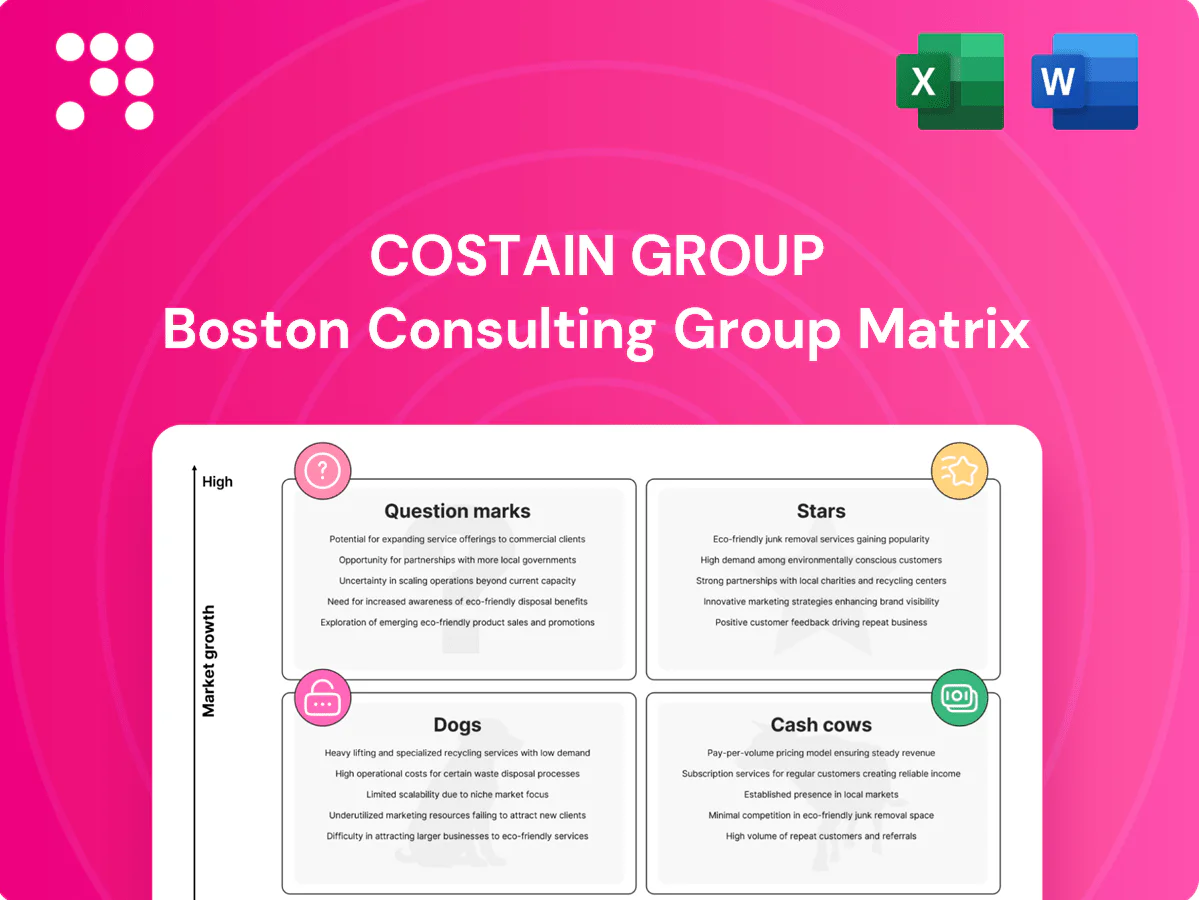
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Costain Group’s services fall on the BCG Matrix—market leaders, underperformers, or promising bets? This snapshot hints at strategic priorities, but the full BCG Matrix gives you quadrant-by-quadrant placement, data-backed recommendations, and clear capital-allocation moves. Buy the complete report for a ready-to-present Word analysis plus an editable Excel summary that saves you hours of work. Get instant access and start making smarter investment and product decisions today.
Costain holds strong positions on major UK road and rail frameworks, capturing high-share, high-visibility work across government-sponsored programmes with a steady pipeline of repeat framework wins.
These flagship projects keep the flywheel spinning, but sustaining growth requires heavy cash deployment and skilled delivery teams to convert opportunities at pace.
Continue targeted investment in talent and working capital to defend leadership and accelerate pipeline conversion.
Costain’s integrated digital design, data platforms and BIM-led delivery occupy a hot, growing niche where clients demand delivery certainty and carbon reductions, so the tech-led offer is winning share.
That capability burns cash in R&D and capability build but increases margins and client stickiness as projects standardise on digital workflows.
As the category scales in 2024, doubling down on investment preserves momentum and market position while payback emerges through higher margin, repeatable delivery models.
Regulated water upgrades are accelerating ahead of AMP8, with UK water companies planning c.£56bn capex for 2025–30; Costain is a go-to on complex, digitally enabled programs and holds high share across key clients. Growth is brisk but working capital swings can be chunky quarter-to-quarter. Fund delivery excellence is critical to lock in the next AMP and capture rising resilience spend.
Connection upgrades, flexibility assets and system integration are racing ahead and Costain is already embedded, leveraging its engineering credentials to secure seats at major UK grid and storage programmes aligned with the UK net-zero by 2050 pathway. Strong project pedigree drives market share, but Costain needs capital, specialist skills and partnerships to keep pace; invest now to cement category leadership amid rapid storage and grid modernisation.
Program management for defence estates is a growth pocket as secure, complex programmes with multi-decade horizons and rising UK defence spend (~£50bn in 2024) expand; Costain’s lifecycle capability and reported FY2024 revenue near £1.2bn give leverage for repeat work, but scaling clearance, digital twin and supply-chain depth is essential to keep high-entry-barrier share durable.
Costain holds high-share positions on UK road/rail frameworks, water AMP and grid/storage, driving high-growth, high-visibility revenue but requiring heavy cash and skilled delivery to convert pipeline.
Digital/BIM-led delivery and defence PM boost margins and client stickiness; sustained investment in talent, working capital and partnerships is required to defend and scale.
| Metric | 2024 | Note |
|---|---|---|
| Costain FY2024 rev | £1.2bn | reported |
| UK MOD spend | ~£50bn | 2024 |
| UK water capex | £56bn | 2025–30 plan |
 Detailed Word Document
Comprehensive BCG Matrix review of Costain Group’s units, identifying Stars, Cash Cows, Question Marks, Dogs and strategic moves.

 Customizable Excel Spreadsheet
One-page Costain BCG Matrix pinpointing stars and dogs to simplify portfolio decisions for faster, clearer action.
Highways framework maintenance sits in a mature, low-growth segment for Costain with stable 2024 spend profiles driven by long-term National Highways frameworks where Costain already holds key positions. Volumes are steady and cash generation predictable, requiring limited promotion — focus is on execution and continuous optimization. Milk returns via operational excellence and strict working-capital discipline to protect margins.
Rail asset renewals are a recurring, established share of Costain’s workstream, rolling year after year and not a blistering growth story; in 2024 they helped sustain group revenue of about £1.1bn. Margins on renewals are modest but tidy with good planning, typically mid-single digits, letting operating cash generation exceed cash consumption. Maintain capability, trim overhead and bank the cash.
Bespoke consultancy and design services are a Cash Cow for Costain, with existing clients in 2024 returning for front-end design and advisory, producing steady revenue and modest growth. Outcomes hinge on utilization rates and delivery efficiency rather than sales volume. Marketing spend remains light as long-term client relationships and repeat engagements drive demand. Targeted investment in productivity tools can lift yield and margins.
Long-term operations and maintenance contracts deliver recurring cash with low capex and in 2024 formed a larger proportion of Costain’s secured revenues as the UK utilities market matured. Costain’s O&M share is sticky, underpinned by multi-year frameworks and renewals. Margins improve through efficiency gains and digital tooling; continued automation of routine tasks and maintaining service levels drive incremental margin expansion.
Regulatory must-dos for safety and carbon drove steady 2024 orders for Costain, sustaining an order book ~£1.1bn and delivering predictable, low-growth cash flow rather than explosive expansion.
Costain’s credibility and repeat scopes keep selling costs low; reported 2024 cash conversion remained strong near 80%, supporting free cash generation.
Standardizing delivery across compliance-led upgrades can widen margins by reducing variability and overhead on recurring scopes.
Highways maintenance, rail renewals, consultancy and O&M are Costain Cash Cows in 2024: stable volumes, low capex, high cash conversion (~80%) and orderbook/revenue around £1.1bn; focus on execution, efficiency, automation and standardised delivery to defend margins and fund growth areas.
| Metric | 2024 |
|---|---|
| Orderbook/revenue | ~£1.1bn |
| Cash conversion | ~80% |
| Capex intensity | Low |
The file you're previewing is the final Costain Group BCG Matrix you'll receive after purchase. No watermarks or demo notes—just a professionally formatted, analysis-ready report tailored to Costain's portfolio. It reflects market insights and strategic positioning, ready to edit, print, or present. Purchase delivers this exact document—no surprises, immediate download.
Dogs: Legacy fixed-price civils packages sit in low growth, low share territory with outsized risk on lumpsum contracts, and in 2024 continued to trap cash in claims and overruns; turnarounds are costly and rarely justify reinvestment. Exit as contracts complete and avoid new like-for-like work to stop further margin erosion and cash drag.
One-off general building outside core is a commodity segment with little differentiation or scale, typically delivering razor-thin operating margins of around 1–3% and facing crowded competition and no growth tailwind. Such projects distract leadership, soak up working capital and limit free cash flow. Discontinue these bids and redeploy teams and capital into Costain’s core infrastructure markets to lift margin and strategic focus.
Small reactive works without frameworks sit in the Dogs quadrant: low share, price-led with sporadic demand and revenue pressure, evident in 2024 when group revenues remained subdued and margin compression persisted. Admin-heavy and cash-light operations have produced working-capital strain, creating a classic value trap that's hard to fix structurally. Recommend pruning non-core projects and channeling bid flow into framework routes only to restore predictability and protect margins.
Isolated international pursuits deliver low share and weak synergies for Costain; 2024 filings indicate international revenue remained a minor portion of group income, with unclear pathways to scale and margin recovery as overheads rise faster than returns.
Non-differentiated plant hire is capital-intensive and commoditized in 2024, offering no growth vector for Costain; market dynamics favor specialists, squeezing margins and leaving Costain with low share versus niche providers.
Little strategic edge exists—recommend run-down or outsource to trusted partners to reallocate capital to higher-return engineering and services.
Legacy fixed-price civils, one-off general building and reactive small works sat in low-growth, low-share Dogs in 2024, trapping cash in claims and compressing margins; recommend exit or redeploy. Non-differentiated plant hire and isolated international pursuits lack scale and synergies—divest or partner only where clear scale exists.
| Segment | 2024 status | Margin |
|---|---|---|
| Fixed-price civils | Exit/complete contracts | Cash negative |
| General building | Commodity | 1–3% |
Hydrogen and CCUS are high-growth adjacencies for Costain given the UK targets of 10 GW low-carbon hydrogen by 2030 and CCUS scale-up aiming for 20–30 MtCO2/yr by 2030, but Costain’s market share is early-stage. Large capex cycles are imminent; landing anchor projects could flip these from Question Marks to Stars. Success requires heavy investment in alliances, skills, demos and selective bets where client pull and funding are confirmed.
Exploding interest in AI-driven asset performance platforms is reflected in McKinsey 2024 data showing 26% of firms have scaled at least one AI use case, yet competition remains fragmented with many niche players and nascent share; Costain can lead if it proves measurable savings at scale. Success requires data rights, productization, and client adoption; invest to win lighthouse cases and kill pilots that stall; predictive maintenance market is forecast to reach ~$18B by 2028.
Modular/offsite infrastructure is a Question Mark: market growth driven by speed, safety and carbon benefits (2024 forecasts show c.6–8% CAGR) but Costain’s share is unproven. Differentiation depends on design-for-manufacture capabilities and strategic partners; modular can cut build time up to 50% and cut embodied carbon up to 60%. High setup costs (often tens of millions) and uncertain near-term returns mean commit to a focused niche or step back.
EV charging and roadside energy hubs are high-growth Question Marks for Costain: UK policy targets 300,000 public chargers by 2030, creating network-scale opportunity, but Costain’s role in the value chain is still forming and market share remains small. If Costain secures large-scale rollout contracts, share could surge; success depends on developing financing models and durable O&M propositions and proving them with pilot programs for strategic clients before scaling.
Nature-based flood and water resilience sits as a Question Mark for Costain: demand is rising under climate pressure (5.2m properties at flood risk in England) and AMP8 (2025–30) sets new investment windows, but market structures and procurement models are shifting. Early pilots can scale into frameworks or fizzle; evidence shows local peak flow reductions of 20–30% from natural measures. Costain needs capability build, robust outcome metrics, and pilots aligned to AMP8 procurement timelines.
Costain faces multiple Question Marks: hydrogen/CCUS (UK 10 GW H2 by 2030; 20–30 MtCO2/yr CCUS), AI-driven asset platforms (26% firms scaled an AI use case, 2024), modular/offsite (6–8% CAGR; build time −50%, embodied carbon −60%), EV charging (300,000 public chargers by 2030) and nature-based resilience (5.2m properties at flood risk; AMP8 2025–30); each needs targeted investment, pilots and anchor contracts.
| Segment | 2024/Target | Key metric |
|---|---|---|
| Hydrogen/CCUS | 10 GW / 20–30 MtCO2/yr by 2030 | Anchor projects needed |
| AI platforms | 26% scaled use case (McKinsey 2024) | $18B market by 2028 (predictive maint.) |
| Modular | 6–8% CAGR | −50% time, −60% embodied CO2 |
| EV charging | 300,000 chargers by 2030 | Financing/O&M models |
| Nature-based resilience | 5.2m flood-risk props; AMP8 | 20–30% peak flow reduction |


