
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Cryoport faces strong supplier and buyer dynamics, moderate threat of new entrants, and evolving substitute and rivalry pressures in the cold-chain biotech niche. This snapshot highlights key risks and positioning but only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore force-by-force ratings, visuals, and strategic implications for Cryoport.
Supplies like liquid nitrogen, dry ice and certified cryo shippers are concentrated among a few majors (Linde, Air Liquide, Messer) and specialist logistics providers such as Cryoport, which gives suppliers outsized pricing and allocation power in tight markets; the global industrial gases market was valued near 70–80 billion USD in 2024. GxP requalification of alternatives is slow, so multi-sourcing and 1–3 month inventory buffers can mitigate but not eliminate supply risk.
Specialized cryogenic freezers, dewars and sensors are produced by a small pool of compliant manufacturers, giving suppliers elevated leverage; industry lead times commonly run 12–20 weeks and customization drives higher margins. Validated equipment swaps trigger requalification cycles that can cost $100k–$500k and take months, locking buyers in. Long-term supply agreements are therefore used to stabilize pricing and availability.
Global life-science lanes depend on a handful of carriers and integrators—DHL, FedEx and UPS dominate express pharma corridors—so slot scarcity, disruptions and surcharges can quickly shift terms toward carriers; pharma-grade GDP requirements further narrow usable options, while diversified lane design and on‑demand charters provide practical ways to reduce exposure.
Telemetry, data platforms and calibration services are essential to chain-of-custody for biologics cold chain; proprietary devices and data schemas create vendor lock-in and long-term dependency. Cybersecurity and validation protocols add switching friction, highlighted by 2024 regulatory emphasis on supply‑chain resilience. Co-developing open APIs with vendors can rebalance power and lower integration costs.
GMP-compliant packaging and reagents require strict specs and full lot traceability, so batch failures or recalls concentrate operational and regulatory risk onto a small set of approved suppliers. Requalification typically incurs six-figure costs and 6–12 month timelines, deterring rapid supplier switches. Strategic safety stocks and dual-qualification of suppliers are therefore essential risk mitigants.
Suppliers hold high bargaining power: industrial gases market ~70–80B USD (2024), few major players, and 12–20 week lead times for cryogenic equipment. Requalification costs commonly USD100k–500k and 6–12 months, deterring switching; DHL/FedEx/UPS cover ~70–80% of pharma express lanes, concentrating carrier power.
| Metric | Value |
|---|---|
| Industrial gases (2024) | 70–80B USD |
| Lead times | 12–20 weeks |
| Requalification cost | 100k–500k USD |
| Carrier share | ~70–80% |
 Detailed Word Document
Tailored Porter's Five Forces analysis for Cryoport that uncovers key drivers of competition, supplier and buyer power, and barriers to entry, identifying disruptive threats, substitutes, and strategic levers that influence pricing, profitability, and market positioning.

 Customizable Excel Spreadsheet
A clear, one-sheet summary of Cryoport’s five competitive forces—perfect for quick strategic decisions and investor decks, with customizable pressure levels to reflect evolving cold-chain and regulatory dynamics.
Concentrated big‑pharma and CGT sponsors exert significant bargaining power, with the top 10 sponsors driving roughly 40% of development procurement spend in 2024 and using validated vendor lists to limit suppliers. Their volume allows negotiation of price and service tiers, yet mission‑critical cold‑chain logistics dampen pure price sensitivity. Contracts increasingly hinge on performance KPIs and SLAs, with penalties commonly reaching mid‑single digits of contract value.
Process validation, lane mapping and regulatory filings typically require 6–18 months and can cost millions, making provider switches costly. The risk of compromising product viability or regulatory approval discourages change, damping buyer power even for large pharma. Multiyear MSAs, commonly 3–5 years, further codify continuity and reduce negotiation leverage.
Clinical-to-commercial transitions create uneven shipment patterns, amplified by over 2,000 active cell and gene therapy trials worldwide in 2024, driving spikes and lulls in demand. Buyers press Cryoport for flexible pricing and capacity guarantees, pushing contracts toward take-or-pay or tiered rates. Accurate forecasting—often tied to milestone-based volumes—becomes a key negotiation lever to allocate risk and pricing.
Clients demand real-time monitoring, audit trails and deviation management; a 2024 industry survey found ~78% of life-science shippers prioritize end-to-end visibility, letting providers with superior data charge premiums while weak transparency strengthens buyer pushback.
Large pharma/CGT sponsors (top 10 ~40% of procurement spend in 2024) hold strong leverage but mission‑critical cold chain and high switching costs (6–18 months, multi‑million validation) limit pure price pressure; contracts favor KPIs/SLAs with mid‑single‑digit penalties. Dual vendors per lane common; Cryoport earns premiums for real‑time visibility and low excursion rates amid ~2,000 active CGT trials and a ~$17.2B cold‑chain market (2024).
| Metric | 2024 Value |
|---|---|
| Top 10 sponsor spend | ~40% |
| Active CGT trials | ~2,000 |
| Cold‑chain market | $17.2B |
| SLA penalties | Mid‑single‑digit % |
| Validation time/cost | 6–18 months; ~$M+ |
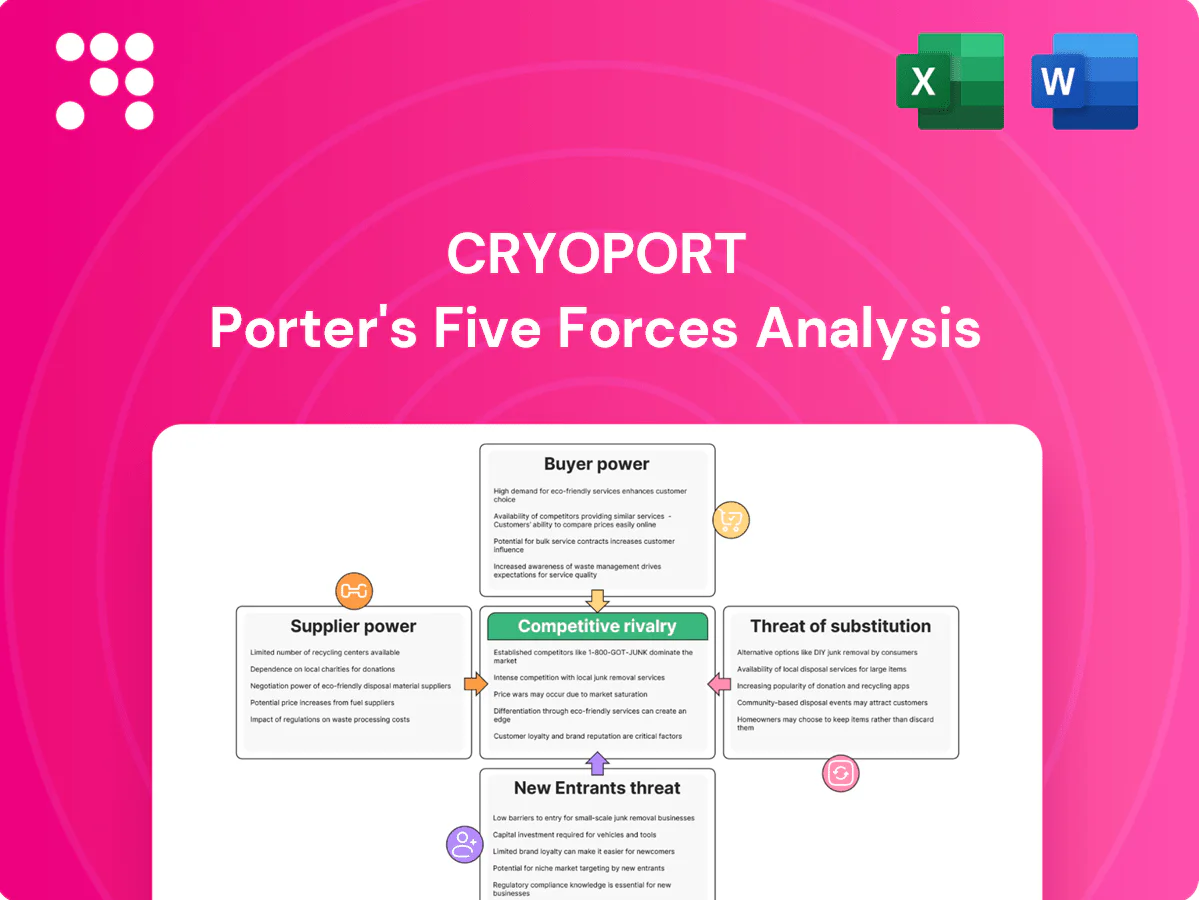
This preview displays the complete Cryoport Porter’s Five Forces analysis you will receive—no samples or placeholders. It is the exact, professionally formatted document available for instant download upon purchase. Use it immediately for decision-making, presentations, or research.
UPS/Marken and DHL each operate in over 220 countries and territories while World Courier, now part of Cencora, maintains operations across 50+ countries, concentrating on life‑science cold‑chain at scale. Their expansive networks intensify rivalry on coverage and speed; differentiation rests on CGT expertise and lane‑validation depth. Price pressure exists, but validated service quality and regulatory compliance remain decisive.
Specialist cryo providers compete on proprietary cryogenic know-how and white-glove handling for high-complexity therapies and clinical trials, servicing a market with over 2,000 active cell and gene therapy trials by 2024. Rivalry centers on minimizing failure rates—industry targets often cite ≤0.1% shipment loss—and stringent temp-excursion control and QA protocols. Strategic partnerships with CMOs and CROs drive share allocation and bundled service wins.
Sensor accuracy, predictive alerts, and analytics drive wins as providers report up to 30% fewer shipment failures when advanced monitoring is deployed; Cryoport and peers are investing heavily in IoT, AI route optimization, and digital quality systems to capture this value.
Cryoport (NASDAQ: CYRX) faces intensified rivalry as integrated packaging, biostorage and regulatory support create client stickiness; bundles can undercut standalone vendors and lock long-term contracts. Competitors race to offer one-stop solutions to capture share amid a market supporting over 20 FDA-approved cell and gene therapies by 2024. Cross-selling shifts competition to scope and service depth, not just price.
Quality and compliance differentiation centers on GDP/GMP adherence, audit outcomes, and certifications as primary battlegrounds; strong audit results and ISO/GDP certifications reduce buyer switching and claims. Lower excursion rates demonstrably cut client risk and liability, and superior CAPA systems plus thorough documentation drive RFP wins and contract renewals.
Global integrators (UPS/DHL 220+ countries; World Courier 50+ countries) intensify coverage/speed rivalry; differentiation is CGT expertise and validated lanes. Specialist cryo firms compete on cryogenic know‑how for 2,000+ CGT trials (2024) with industry failure targets ≤0.1% and up to 30% fewer failures using advanced monitoring. Bundled one‑stop solutions (20+ FDA cell/gene approvals in 2024) raise switching costs and shift competition to scope and compliance.
| Metric | Value (2024) | Competitive Impact |
|---|---|---|
| Integrator reach | 220+ countries | Scale advantage |
| Specialist footprint | 50+ countries | CGT focus |
| Active CGT trials | 2,000+ | Service demand |
| Failure target | ≤0.1% | Quality battleground |
| Monitoring benefit | ≈30% fewer failures | Tech differentiation |
Larger sponsors increasingly build internal cryo logistics and storage, with dedicated GMP cryo facilities typically requiring capex often exceeding 10 million dollars per site. Internal networks can substitute outsourced lanes in core geographies, but required expertise and continuous 24/7 coverage—which can raise operating costs by roughly 15–25%—remain major hurdles. Many adopt hybrid models, yet complex international routes and specialty shipments still favor experienced third-party specialists.
Therapies engineered for 2–8°C or ambient stability erode demand for deep‑cold logistics by enabling standard cold chain transport and storage. Lyophilization and stabilizing reagents can shift requirements from cryogenic to refrigerated or dry formats, but many cell and gene therapies remain incompatible with such reformulation. Long reformulation timelines and regulatory retesting slow adoption, limiting near‑term substitution risk.
Near-patient or point-of-care decentralized manufacturing can shorten or eliminate shipments, cutting long-haul cryogenic moves and transit times from days to hours; by 2024 pilots expanded across dozens of hospitals globally. Site standardization and QC remain challenging, requiring validated processes and qualified personnel. Despite momentum, centralized supply chains still dominate many indications and commercial launches.
Novel vitrification and emerging non-cryogenic preservation approaches (room-temperature or desiccation-based) could dilute demand for Cryoport if validated; vitrification already drives >90% embryo survival in IVF, showing tech can shift standards. Broad logistics tolerances would reduce cold-chain costs, but clinical proof and regulatory acceptance are likely 5–10 years away and early use cases remain narrow (IVF, small tissue samples).
Largely medium threat: internal GMP capex (> $10M/site) and 24/7 ops (+15–25% Opex) limit insourcing; hybrid models persist. Reformulations (lyophilization) and ambient-stable therapies reduce cryo demand but slow regulatory timelines—impact 5–10 years. Point‑of‑care pilots rose in 2024 but centralized CGT ($6.9B in 2024) keeps specialist demand; passive couriers ~30% cheaper on some lanes.
| Metric | Value |
|---|---|
| GMP capex/site | > $10M |
| Opex insourcing uplift | +15–25% |
| CGT market (2024) | $6.9B |
| Passive courier cost | ≈30% cheaper |
| Impact timeline | 5–10 yrs |
GDP/GMP compliance, mandatory audits and certified quality systems create high entry hurdles for Cryoport competitors; industry validation cycles commonly span 9–18 months and customer qualification adds another 6–12 months, while extensive documentation and operator training (often hundreds of hours) sharply slow market entry, deterring fast entrants.
Capital-intensive infrastructure for cryogenic logistics—cryofleets, biostorage, sensors and redundant systems—demands substantial capex, creating a high barrier to entry. Global depots and long-term LN2 supply contracts further raise fixed costs and operational complexity. Mandatory insurance and liability coverage increase capital and underwriting hurdles. Scale economies in deployment and network density favor incumbents.
Proven, low-excursion lanes spanning regions are costly and time-consuming to replicate, giving Cryoport an operational moat. Data from thousands of validated shipments compounds this advantage, enabling predictive performance and contract-winning metrics. New entrants lack the historical performance records buyers demand in RFPs, limiting market access. Building the requisite trust and validation across lanes typically takes years.
Experienced QA, regulatory, and CGT operations staff are scarce, with industry reports in 2024 noting biopharma skilled labor vacancy rates near 15% and onboarding to competency often requiring 6–12 months. Mistakes carry high clinical and financial risk—clinical program setbacks commonly exceed $100M in lost value—while incumbent playbooks, built on tacit process knowledge, are difficult for new entrants to replicate.
Sponsor organizations in 2024 continue to resist changing validated cold-chain vendors because perceived regulatory risk and transition costs undermine therapy timelines and patient safety, reinforcing incumbent advantage. Master service agreements and integrated SOPs create contractual and operational lock-in, while pilot-to-scale validation pathways bias procurement toward existing providers. New entrants must deliver clear step-change value in reliability, regulatory assurance, or cost to displace established partners.
High regulatory and validation barriers (9–18 months) plus operator training (6–12 months) and 2024 skilled-labor vacancy ~15% create steep entry costs and delays. Proven low‑excursion lanes, thousands of validated shipments and MSAs lock sponsors in; clinical setbacks often exceed $100M, reinforcing Cryoport incumbency.
| Metric | 2024 |
|---|---|
| Validation time | 9–18 months |
| Training to competency | 6–12 months |
| Skilled‑labour vacancy | ~15% |
| Clinical setback cost | >$100M |


