
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock the full strategic blueprint behind China National Building's business model in an actionable Business Model Canvas. This concise analysis exposes value propositions, partnerships, and revenue levers. Purchase the complete editable canvas to benchmark, plan, and implement proven growth strategies.
Central and local governments award major infrastructure and housing contracts and set regulatory frameworks; in 2023 local government special bond issuance reached about 3.65 trillion yuan, fueling projects. Long-term ties enable PPPs and concessions, giving priority access to strategic programs. Collaboration reduces permitting risk, aids land acquisition and urban renewal amid China’s ~65.2% urbanization rate (2023).
Banks, insurers and MDBs provide construction finance, guarantees and project bonds that enable CNB to underwrite large-scale and cross-border projects; the World Bank Group committed about $86 billion in FY24 to development finance, underscoring available MDB liquidity. Structured financing and project bonds unlock mega-projects and improve capital efficiency. Risk-sharing via guarantees and insurance boosts bid competitiveness and supports client affordability through deferred-payment and PPP models.
Specialist design institutes and engineering consultants boost survey, design and complex engineering capabilities, supporting China National Building as the Chinese construction output exceeded RMB 28 trillion in 2023. Joint multidisciplinary teams accelerate regulatory approvals and improve lifecycle performance, with prefabricated construction representing roughly 30% of new build area in 2023. Collaboration ensures international code compliance and drives innovation in BIM, modular methods and green standards.
Trusted supply chains secure cement (>2 billion tonnes annually) and steel (>1 billion tonnes) plus advanced materials at scale, while OEMs supply cranes, TBMs and precast systems with integrated maintenance support. Strategic sourcing and long‑term contracts stabilize costs and schedules, enabling consistent quality and delivery across domestic and overseas projects.
Local contractors and JV partners provide market entry, labor and permitting know-how, leveraging China’s BRI footprint across 140+ countries in 2024. JVs help meet localization quotas and social license requirements while shared execution reduces operational risk and improves cost benchmarks. Partnerships also expand after-sales and O&M footprints, supporting lifecycle revenues and warranty performance.
Key partners: central/local governments provide contracts and 2023 local government special bonds ~3.65 trillion yuan, enabling PPPs; banks, insurers and MDBs (World Bank Group ~$86bn FY24) supply project finance; suppliers and OEMs secure cement >2bn t, steel >1bn t and prefabrication (~30% new area 2023); JV/local contractors leverage BRI presence in 140+ countries (2024).
| Partner | Role | Metric |
|---|---|---|
| Governments | Contracts/permits | 3.65T CNY bonds (2023) |
| MDBs/Banks | Finance | $86B WBG FY24 |
| Suppliers | Materials/OEMs | cement>2bn t; steel>1bn t |
| JVs | Market entry | BRI 140+ countries (2024) |
 Detailed Word Document
A comprehensive Business Model Canvas tailored to China National Building, detailing customer segments, channels, value propositions and the 9 classic BMC blocks with actionable narratives and competitive advantages; includes SWOT-linked insights and validation-ready data for presentations, investor pitches, and strategic decision-making.

 Customizable Excel Spreadsheet
High-level view of China National Building’s business model with editable cells—quickly identify core components and relieve strategic planning and investor-communication pain points.
End-to-end EPC integrates engineering, procurement and construction to unify schedule and cost control, supporting China National Building’s standardized workflows and a 2024 EPC backlog exceeding CNY 800 billion. Turnkey delivery shifts execution risk to the contractor and simplifies client management, with reported on-time delivery rates above 90% on major programs. Standardized processes scale across sectors and drive predictable outcomes on complex builds.
Survey, design, and BIM-led engineering create front-end studies and digital twins that cut rework and lifecycle costs through clash detection and simulation; integrated design accelerates permitting and enables value engineering. Data-rich BIM models directly feed prefabrication and modularization workflows, supporting China’s MOHURD target of 30% prefabrication in new buildings by 2025. They also streamline facilities-management handover with as-built data and asset tagging.
Land assembly, development, sales and leasing diversify China National Building’s revenue streams, with mixed-use and urban renewal projects leveraging scale to improve margins — China urban redevelopment projects accounted for roughly 30% of major developers’ project pipelines in 2024. Property services sustain asset value and tenant satisfaction; the Chinese property management market exceeded RMB 1.9 trillion in 2023 and is growing into 2024. Post-delivery O&M generates recurring cash flow, supporting liquidity amid cyclic sales periods.
In-house precast, green materials and integrated facade systems improve product quality and shorten lead times for rapid delivery; vertical integration buffers supply volatility and pricing to stabilize margins; innovation in low-carbon materials supports 2024 ESG reporting and aligns with China’s 2060 carbon neutrality commitment.
Developing, financing and operating infrastructure via PPP concessions delivers long-duration income with typical concession terms of 15–30 years and predictable cashflows. Concessions align interests through availability- or demand-based payments, reducing traffic and revenue risk transfer. Active asset management lowers lifecycle costs and, in 2024, CNBM-style operators report O&M savings of 8–12% vs. legacy benchmarks, strengthening public-client relationships.
End-to-end EPC (backlog >CNY 800bn) and turnkey delivery (on-time >90%) unify cost/schedule control; BIM-led design and 30% prefabrication targets cut rework and lifecycle costs; vertical integration (in-house precast) stabilizes margins; PPP concessions (15–30 yr) and O&M (savings 8–12% in 2024) provide recurring cashflow.
| Metric | Value |
|---|---|
| EPC backlog | CNY 800bn+ |
| On-time delivery | >90% |
| Prefabrication target | 30% (2025) |
| Prop mgmt market | RMB 1.9tn (2023) |
| O&M savings | 8–12% (2024) |
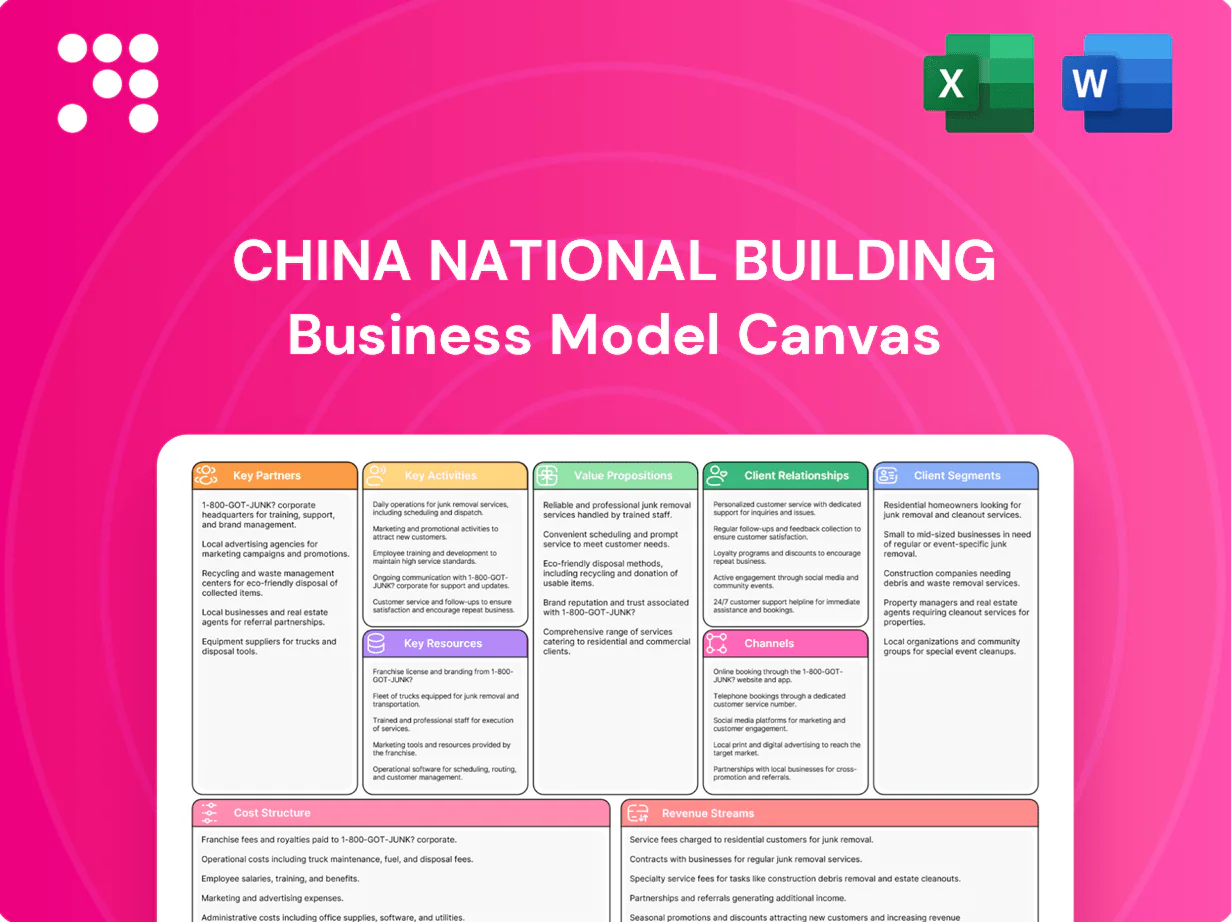
The China National Building Business Model Canvas shown here is the actual deliverable, not a mockup, and presents real content you’ll receive after purchase. When you complete your order you’ll immediately get this same file—fully formatted and editable in Word and Excel. It’s ready for presenting, customizing, and implementing with no hidden sections or placeholders.
Large, experienced teams — China State Construction Engineering Corporation, ranked number one in ENR Top 250 Global Contractors in 2023–2024, employ over 300,000 staff to execute complex multi-country programs. Robust PMO frameworks drive schedule, cost and quality control across projects. A documented safety culture and compliance practices reduce incidents and downtime. Institutional knowledge accumulated on billions-dollar projects compounds competitive performance advantages.
A robust capital base enables bid bonds, working capital and equity in PPPs, and as of 2024 China State Construction (largest peer) reported 2023 revenue about $146.4bn, underpinning large bid capacities. Access to diversified funding—bank loans, bonds and policy financing—lowers WACC and boosts competitiveness on mega-projects. Financial strength raises win rates and stabilizes operations across cyclical downturns.
Owned heavy machinery and yard networks enable rapid mobilization, cutting typical site setup time by weeks; China’s leading contractors reported mobilization efficiencies improving in 2024 as modular projects grew. Fabrication plants support precast and modular production, with modular output rising sector-wide in 2024 amid policy pushes for industrialized construction. High asset availability reduces rental costs and schedule delays, enhancing control over critical-path activities and improving on-time delivery metrics.
Proprietary methods, BIM libraries and QC systems standardize delivery across China National Building, while process IP shortens regional learning curves and enables repeatable margins. 2024 MOHURD guidance expanded mandatory BIM use in public projects, and compliance frameworks streamline international certifications, protecting quality and brand reputation.
China National Building leverages a diversified supplier network (300+ vendors) and local partnerships to ensure resilience and 5–8% cost advantages from competitive sourcing; local alliances secure permits and a 120,000-strong regional workforce. Multi-market reach across 50+ countries in 2024 hedges geopolitical and currency risks and enables consistent service to multinational clients.
China National Building commands 300,000+ staff and institutional PMO capacity, reducing delays on mega-projects.
Peer 2023 revenue benchmark $146.4bn; diversified funding and strong balance sheet support large bids and PPP equity.
Owned plant and modular output rose in 2024, cutting mobilization weeks and rental costs.
Supply network 300+ vendors, 50+ markets (2024) and 5–8% sourcing cost edge sustain margins.
| Metric | Value (2024) |
|---|---|
| Staff | 300,000+ |
| Peer rev (2023) | $146.4bn |
| Markets | 50+ |
| Vendors | 300+ |
| Cost edge | 5–8% |
Integrated EPC, development and O&M create single-point accountability, cutting interface risk across phases; China National Building, ranked #1 on ENR Top 250 Global Contractors 2024 and operating in 100+ countries, sustains capacity for mega-projects (regularly executing $1bn+ contracts) and delivers consistent standards and supply-chain scale across geographies.
Standardized processes and vertical integration cut on-site variance, enabling China National Building to deliver projects to fixed scopes and timelines; in 2024 the group’s upstream procurement scale exceeded RMB 100 billion, strengthening price and supply stability. Strong procurement power locks input costs and reduces material volatility. Real-time digital control rooms monitor critical paths and KPIs, giving clients predictable handover dates and measurable schedule certainty.
China National Building Material maintains ISO 9001, ISO 14001 and ISO 45001 certifications and completed third-party audits in 2024, reducing operational incidents and accelerating permitting timelines; robust QA/QC and HSE systems lower compliance costs, protect stakeholders and community trust, and support faster government approvals for projects nationwide.
Integrated EPC-to-O&M single-point accountability reduces interface risk and enables predictable delivery; CNBM ranked #1 on ENR Top 250 Global Contractors 2024, operating in 100+ countries. Vertical integration and RMB100bn+ 2024 procurement scale stabilize input costs and schedule certainty. ISO 9001/14001/45001-certified QA/HSE and digital control rooms cut incidents and accelerate handovers.
| Metric | 2024 |
|---|---|
| ENR rank | #1 |
| Countries | 100+ |
| Procurement scale | RMB 100bn+ |
| Typical mega-contract | $1bn+ |
Long-term key account and framework agreements give CNBM pipeline visibility, with long-term contracts accounting for over 60% of group sales in 2023, ensuring steady cash flow and project scheduling. Frameworks streamline procurement and locked pricing across multi-year projects, cutting procurement cycles by ~30% and stabilizing margins. Dedicated account teams enable proactive planning, deepening trust and driving repeat business.
Shared-risk PPP and concession partnerships align incentives over decades through long-term contracts and performance-linked payments; China’s 2024 local government special bond quota of 3.8 trillion RMB continues to underpin such financing. Transparent, quantifiable performance metrics (availability, uptime, cost per km, etc.) sustain collaboration between sponsors and authorities. Regular governance, quarterly reporting and independent audits maintain accountability and strengthen renewal prospects for 20+ year concessions.
Early contractor involvement refines scope and cost, with industry studies in 2024 reporting ECI can cut cost overruns by up to 15% and change orders by similar margins. Joint design workshops routinely identify ~8–12% tangible savings and innovation opportunities on pilot projects. Open-book contracting has reduced commercial disputes by about 30% in recent implementations, improving outcomes across cost, time, and quality.
Warranties (commonly 1–5 years) plus 12–36 month maintenance and facility-service contracts extend client ties; performance dashboards track availability, MTTR and OEE to keep assets optimized; rapid-response teams target sub-24-hour onsite response to cut downtime; service-quality metrics drive referrals and renewals, with many facility-service providers reporting renewal rates above 80% in 2024.
Client dashboards deliver schedule, cost and ESG metrics in real time, with industry cases reporting up to 30% faster stakeholder approvals; BIM models enable collaborative decisions across design and construction teams, reducing rework. Automated reporting cuts administrative workload by ~40% in pilot projects, and enhanced transparency improves client satisfaction and perceived control.
Long-term key-account/framework contracts drove >60% of CNBM sales in 2023, cutting procurement cycles ~30% and stabilizing margins; PPPs leverage 2024 local govt bond quota 3.8tr RMB; ECI and open-book cut overruns ~15% and disputes ~30%; service renewals >80% (2024).
| Metric | Value |
|---|---|
| Long-term contract share | >60% (2023) |
| Local govt bond quota | 3.8tr RMB (2024) |
| Procurement cycle reduction | ~30% |
| Cost overrun cut | ~15% |
| Renewal rate | >80% (2024) |
Relationship-led outreach sources opportunities early, feeding dedicated bid teams that tailor proposals to client needs and capture complex scope; competitive tenders showcase technical strength and risk management. Direct enterprise sales and bidding remain the primary growth engine for China National Building, aligned with CSCEC ranking first in ENR 2024 global contractors by revenue.
Participation in public e-procurement secures visibility across national portals and local platforms, reaching buyers for millions of projects in 2024. Compliance-ready documentation speeds qualification, aligning with standardized requirements on national systems. Digital workflows cut average cycle times by roughly 30% in regions with mature platforms. It broadens access to both national and local projects, increasing tender wins for registered firms.
Joint ventures combine credentials and local access, enabling China National Building to meet domestic and overseas licensing—China remained the world’s largest construction market in 2024 with annual output exceeding $3 trillion. Consortiums spread risk on mega-projects, commonly used for billion-dollar contracts to limit single-entity exposure. Shared references and pooled balance sheets enhance bid eligibility and open doors in new markets.
Forums and expos in 2024 connected China National Building directly with government and SOE decision-makers, converting thought leadership sessions into measurable leads; MOUs signed across events seeded pipelines exceeding RMB 8.3 billion, while strategic partnerships converted into concrete bids for projects worth over RMB 4.1 billion in the year.
Digital marketing and investor relations showcase case studies and ESG results to attract clients and financiers; global ESG assets reached about $45 trillion in 2024, increasing appetite for green construction partners. Online channels drive B2B lead generation and measurable conversion funnels, while IR strengthens confidence for PPP equity needs and supports fundraising. These channels also bolster corporate reputation and access to institutional capital.
Relationship-led sales and competitive bids drive growth—CSCEC ranked first in ENR 2024; enterprise sales remain primary engine. E-procurement and digital workflows cut cycle times ~30% in mature regions, widening project access. JVs/consortiums enable licensing and risk-share for mega projects in China’s >$3 trillion 2024 market; events/IR seeded RMB 8.3b pipeline, RMB 4.1b bids.
| Channel | 2024 Metric |
|---|---|
| Enterprise sales | ENR #1 |
| E-procurement | −30% cycle |
| JVs/Consortiums | China market >$3T |
| Events/IR | RMB8.3b pipeline,RMB4.1b bids |
National and municipal governments are primary buyers for transport, utilities and public buildings, accounting for over 60% of large public construction procurement; contracts commonly run 3–20 years and favor reliable, compliant delivery at scale. They prioritize partners with financing capacity as local governments rely on special bond issuance exceeding RMB 3 trillion annually. Long-term relationships drive repeat awards and stable revenue streams.
Real estate developers and property funds demand cost-effective, fast, high-quality builds and prize integrated design-build and property services for single-source accountability. Scale enables China National Building to support large mixed-use programs as urbanization surpassed 66% in 2024, driving complex project volume. Robust after-sales services reduce lifecycle risk and protect asset value for institutional owners.
Industrial and energy customers require plants, logistics parks and energy infrastructure with strict safety and uptime targets, commonly aiming for 99.9% SLA. They prioritize rapid commissioning and continuity of production. Modular EPC execution shortens delivery timelines by about 30% per 2024 industry studies, and CNBM’s integrated EPC plus O&M offerings sustain reliability and reduce lifecycle downtime.
Multilateral agencies and SOEs abroad fund and sponsor cross-border infrastructure, with partners like AIIB at 105 members in 2024 and the World Bank Group at 189 members, prioritizing compliance, ESG, and transparent reporting; they prefer experienced global contractors and use financing solutions to enhance project eligibility.
Homebuyers, tenants, and communities are the ultimate users of CNBM's residential and commercial assets; China’s homeownership remains above 90% and urbanization is about 67% in 2024, driving steady demand. They prioritize quality, safety, and amenities; leading developers report resident satisfaction rates above 80%. Continuous property management sustains this satisfaction, while structured community engagement builds social license and reduces disputes.
Governments drive >60% large public procurement; contracts 3–20 yrs and rely on financing (local special bonds >RMB3trn 2024). Developers seek integrated design-build; urbanization ~67% (2024). Industry demands 99.9% uptime; modular EPC cuts delivery ~30%. Multilaterals/SOEs prioritize ESG; AIIB 105, World Bank 189 (2024). Homeownership >90%.
| Segment | Key metric | 2024 data |
|---|---|---|
| Government | Share of procurement | >60% |
| Developers | Urbanization | ~67% |
| Industry | Uptime/SLA | 99.9% |
| Multilateral | Members | AIIB 105; WBG 189 |
| Consumers | Homeownership | >90% |
Cement (~1.9–2.0 billion tonnes in China 2023) and steel (1,018 million tonnes crude steel in 2023) plus specialized components drive roughly half of project costs for China National Building. Strategic sourcing via long‑term contracts and hedges cuts price volatility and secures supply, while standardization and modular design can cut material waste materially. Volume discounts and centralized procurement routinely deliver 2–5% margin uplift per project.
Skilled labor, supervision and specialist subcontractors drive delivery, with labor and subcontracting typically accounting for 30–40% of project costs in China. Productivity and safety programs aim to cut unit labor costs and incidents, targeting 10–20% efficiency gains. Local hiring satisfies regulatory compliance and social-stability requirements. Flexible resourcing allows headcount swings of up to ±30% to match demand cycles.
Capex and Opex for fleets, fuel, and maintenance can represent roughly 15–25% of total project costs, with fuel and routine maintenance driving up to 40% of equipment Opex in 2024.
Efficient logistics in China cut delay risks and can improve on-site productivity by 10–20% through better sequencing and reduced idle time.
Site overheads—temporary works, utilities, security—typically add 5–12% to contract costs and must be budgeted separately.
Maintaining utilization rates above 60% is critical for cost-efficiency; each 5% drop can materially raise per-unit equipment costs.
Bid bonds (1–3% of contract) and performance guarantees (typically 5–10% of contract) plus construction insurance (0.5–2% p.a.) materially raise CNBG’s project costs; 2024 China 1Y LPR at 3.65% and typical working-capital fees of 3–6% add interest expense on PPP equity and loans; strong credit profiles cut borrowing spreads by ~50–150 bps and targeted risk management can lower premiums 20–30%.
Land acquisition and permitting can add months and raise project costs; in 2024 land-related expenses and delays represented about 12% of total project budgets for major Chinese developers. Compliance, audits and certifications (including green credentials) add recurring costs and gate public-project eligibility. Corporate functions and digital governance support risk control; overheads scale with global operations, often 8–12% of revenue for large SOEs.
Materials drive ~50% of costs (cement 1.9–2.0bn t China 2023; crude steel 1,018 Mt 2023), labor/subcontracting 30–40% with 10–20% efficiency potential, equipment Opex 15–25% and land/permitting ~12% (2024). Financial costs include bid bonds 1–3%, performance guarantees 5–10%, insurance 0.5–2% p.a., and 2024 LPR 3.65%.
| Metric | Value |
|---|---|
| Cement (China 2023) | 1.9–2.0bn t |
| Crude steel (2023) | 1,018 Mt |
| Materials share | ~50% |
| Labor | 30–40% |
| Equipment Opex | 15–25% |
| Land & permitting (2024) | ~12% |
| Bid bonds | 1–3% |
| Performance guarantees | 5–10% |
| Insurance | 0.5–2% p.a. |
| 2024 LPR | 3.65% |
EPC contract revenues rely on lump-sum, unit-rate, and cost-plus models, with lump-sum dominating large industrial projects and unit-rate used for repeatable civil works. Milestone payments (commonly 30–40% upfront and staged thereafter) sustain cash flow. Incentives typically range 2–5% of contract value to reward early completion and quality. Variations and change orders provide additional scope-based income, sometimes adding 5–15% to original contract value.
Availability payments, tolls and user fees deliver recurring cash for CNBM PPPs, with concession tenors typically 15–30 years boosting revenue visibility; China’s expressway network reached about 164,000 km by 2024, underpinning toll income. Performance‑linked payments incentivize efficiency and service standards, while asset recycling of mature concessions frees capital to fund new projects.
Residential and commercial sales generate large upfront cashflows—China real estate transaction value was about 13.6 trillion yuan in 2023, underpinning development revenues. Leasing and property management provide recurring income streams, with China’s institutional leasing market expanding in 2024 as operators scale portfolios. Mixed-use assets diversify exposure across retail, office and residential demand. Asset disposals crystallize development gains and free capital for new projects.
Service contracts (O&M, facility management, warranties) deliver steady post-construction income, with China’s facility management market surpassing RMB 1 trillion in 2024 and ~7% CAGR 2019–24. Performance KPIs tie fees to uptime and service levels, while multi-year agreements increase client retention and recurring revenue. Cross-sell of upgrades and retrofits lifts lifetime value per client.
Sales of precast, green materials and facade systems contribute higher product margins and recurring contract revenue for China National Building, while design, survey and consulting lines generate steady fee income separate from construction contracts. Internal manufacturing and technical capabilities are monetizable externally through third-party supply and EPC partnerships, and ongoing R&D in sustainable materials supports premium pricing and differentiation.
EPC: lump-sum/unit-rate/cost-plus; milestones 30–40% upfront; incentives 2–5%; variations add 5–15%. PPP: availability/tolls, concession 15–30 yrs; expressways 164,000 km (2024). Property: sales 13.6 tn RMB (2023); leasing + asset disposals. Services: facility mgmt >1 tn RMB (2024), ~7% CAGR 2019–24.
| Stream | Key metrics |
|---|---|
| EPC | 30–40% upfront; incentives 2–5%; variations 5–15% |
| PPP | Concession 15–30 yrs; 164,000 km expressways (2024) |
| Property | 13.6 tn RMB transactions (2023) |
| Services | Facility mgmt >1 tn RMB (2024); CAGR ~7% 2019–24 |


