
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Daiwa Securities Group’s BCG Matrix peek shows where its businesses sit—market leaders, cash generators, and the ones asking for tougher calls. Want the full map? Purchase the complete BCG Matrix for quadrant-by-quadrant placements, data-backed recommendations, and clear next steps for capital allocation and portfolio pruning. It’s a ready-to-use strategic tool in Word and Excel to help you act fast with confidence.
Japanese green and sustainability bond issuance surpassed ¥1.0 trillion in 2024, and Daiwa already holds strong credentials with local issuers. The franchise is visible, relationships are deep, and mandates keep compounding year-on-year. Continued investment in structuring talent and distribution is needed to stay ahead. If momentum holds, this can mature into a dependable fee engine for Daiwa.
ETFs in Japan kept gaining traction in 2024 as total ETF AUM topped ¥30 trillion and retail accounted for roughly 60% of net flows, positioning Daiwa’s shelf and pipes well for share and velocity. High client adoption plus Daiwa’s tight spreads drive market-making scale and turnover. Push education, digital nudges, and NISA-style tax-advantaged wrappers to keep flows sticky. Scale now, harvest later.
Inbound demand for Japan equities is rising and Daiwa’s research and execution remain front-row, leveraging high-touch sales and smart liquidity sourcing to sustain market share. With MSCI Japan weight near 7.8% in 2024, the flow pool for Japan exposure is materially larger for global institutions. Double down on analytics and expanded corporate access to convert interest into mandate wins. Preserve pricing power while volumes stay elevated.
Daiwa’s mass‑affluent wealth solutions are Stars: client assets are compounding and advice‑led wallets grew 18% in 2024 as more investors seek professional planning.
Daiwa’s brand and ~300 branch advisors amplify distribution as the market pie expands.
Keep modernizing planning tools and model portfolios so incremental share converts into durable, fee‑heavy relationships.
Domestic equity capital markets (IPOs/ABBs) are a star for Daiwa in 2024, driven by a healthy deal pipeline, policy tailwinds supporting listings, and active boards accelerating capital raises; Daiwa sits on multiple key mandates and bookrunner roles to capture this momentum.
Daiwa’s Stars in 2024: green/sustainability bonds >¥1.0tn with growing mandates; ETFs AUM ¥30tn (retail ~60% of flows) driving market‑making scale; inbound Japan equity flows (MSCI Japan ~7.8%) and ECM pipeline fuel fees; advice‑led wealth grew +18% with ~300 branch advisors—priorities: structuring, distribution, planning tools to lock fees.
| Metric | 2024 |
|---|---|
| Green bonds | ¥>1.0tn |
| ETF AUM | ¥30tn (retail ~60% flows) |
| MSCI Japan weight | ~7.8% |
| Advice‑led growth | +18% |
| Branch advisors | ~300 |
 Detailed Word Document
BCG Matrix review of Daiwa Securities: identifies Stars, Cash Cows, Question Marks, Dogs with strategic moves to invest, hold, or divest.

 Customizable Excel Spreadsheet
One-page Daiwa BCG Matrix placing each business unit in a quadrant to clarify priorities and cut analysis time for execs.
Core retail brokerage and margin lending in Japan remains a mature, high-share cash cow for Daiwa in 2024, generating steady fee and interest income without need for heavy reinvestment; pricing discipline and scale operations keep unit costs low. Optimize branch footprint and push clients to digital self-serve to lower cost-to-serve, while milking cash flow and investing selectively in UX to protect retention and ancillary revenue.
Plain‑vanilla domestic bond issuance remains steady rather than sprinting; Japan's bond market had roughly 1,200 trillion JPY in outstanding government and corporate bonds in 2024, underpinning predictable deal flow. Daiwa's entrenched relationships with corporates and public issuers secure repeat mandates, while standardized DCM processes deliver reliable fee streams and low incremental cost; maintain coverage and keep the machine humming.
Asset management fees from flagship mutual funds leverage a multi-trillion yen AUM base, delivering predictable margins in a low-single-digit growth category. Brand trust keeps redemptions in check, supporting fee stability even in volatile markets. Targeted cost tweaks and share-class redesigns (e.g., lower-cost institutional classes) can lift profitability without heavy new investment. Don’t overinvest — refine and retain.
Custody, clearing, and settlement are Daiwa's essential plumbing: low-growth but high-utilization businesses that benefit from scale and client stickiness, driving steady fee income. Automation and straight-through processing have compressed costs and lifted margins, turning incremental volume into outsized cash. These services function as quietly powerful cash generators funding strategic initiatives.
Research-driven corporate access (domestic) is a cash cow for Daiwa: established issuer and investor relationships with recurring annual event cycles sustain steady revenue despite modest market growth (low single-digit in 2024); Daiwa holds an entrenched double-digit domestic corporate access share. Hybrid event formats keep per-event costs lower while preserving reach, and monetization focuses on bundled IR/roadshow services plus execution-related commissions.
Core retail brokerage, margin lending, DCM, asset management and custody are Daiwa cash cows in 2024, yielding steady fees/interest with low reinvestment needs; Japan bond market ~1,200 trillion JPY supports predictable DCM. Flagship funds: multi‑trillion JPY AUM; domestic corporate access holds double‑digit share.
| Category | 2024 Metric | Role |
|---|---|---|
| Retail brokerage | High market share; stable fees | Primary cash generator |
| DCM | Japan bond market ~1,200T JPY | Predictable mandates |
| Asset mgmt | Multi‑trillion JPY AUM | Recurring fees |
| Custody/clearing | High utilization, STP | Low-cost fee base |
| Corp access | Double‑digit domestic share | Stable event revenue |
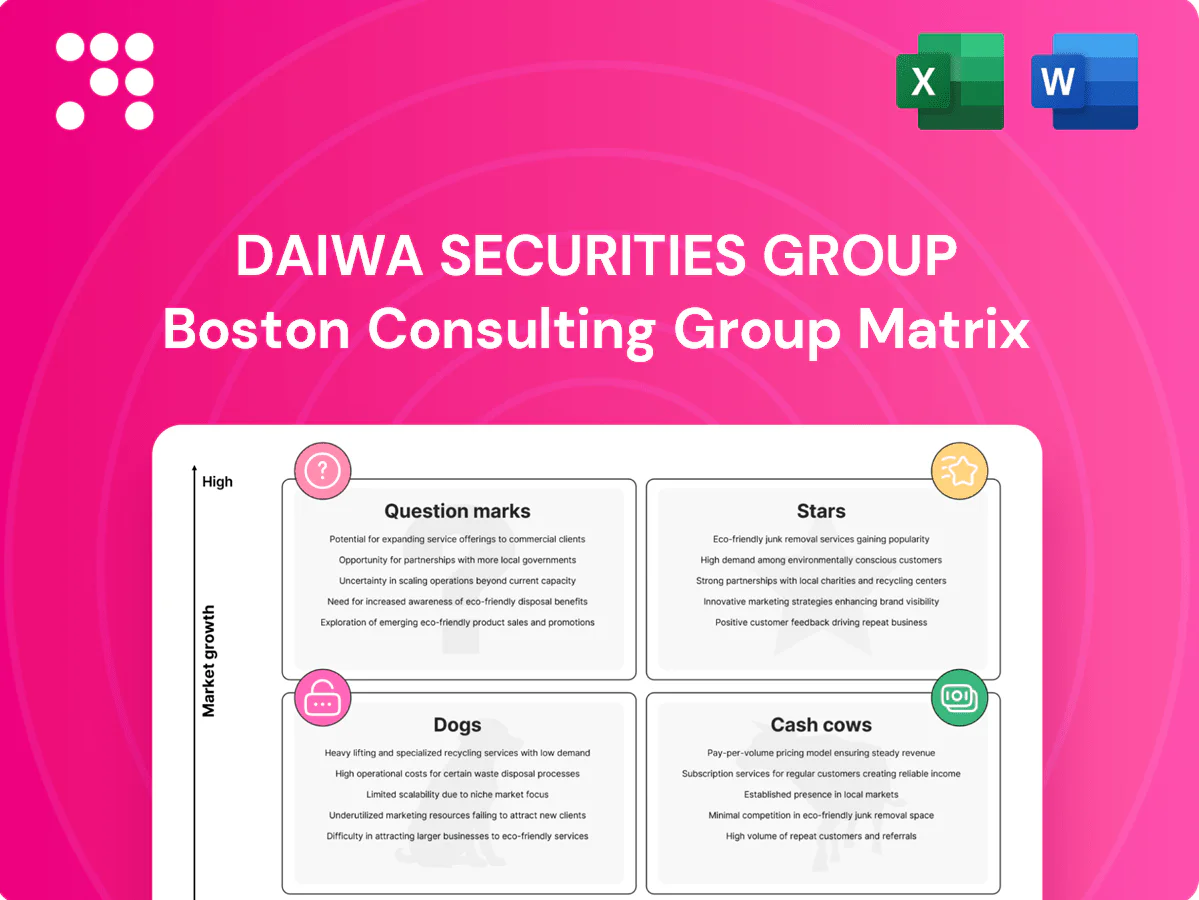
The file you're previewing is the final Daiwa Securities Group BCG Matrix you'll receive after purchase. No watermarks or demo content—just a fully formatted, analysis-ready report tailored to Daiwa's portfolio positions. Delivered immediately and editable, it's prepared for presentations, planning, or board review. What you see is exactly what you'll download.
Underused physical branches in low-density areas show thin client traffic and fixed costs that exceed contributions; in 2024 Daiwa should treat these as low-return assets. Turnarounds and refurbishments historically consume significant budget without materially boosting transactions or AUM. Rapid consolidation or repurposing into advisory hubs or cashless kiosks will free opex for digital platform investment. Redeploy savings to scale online trading, robo-advice and back-office automation.
Legacy on-prem trading stacks demand high maintenance and low agility, with every patch adding measurable cost and risk; cloud-native peers deliver ~2.5x faster release cadence, leaving on-prem speed materially behind. Migrate or sunset — don’t straddle, as delayed decisions compound. The carry cost is a quiet leak: financial firms typically spend ~70% of IT budgets on maintenance, eroding strategic investment capacity.
Small overseas boutiques with minimal league-table presence represent low-share Dogs for Daiwa: fragmented teams and no clear path to scale make them expensive to sustain credibility in each market.
Commoditized money-market and deposit-like products are Dogs: fee caps and ongoing price wars squeeze margins, while clients park cash that generates minimal revenue. Automate servicing, standardize KYC and reporting, and keep operations lean; otherwise cull the line to free capital for higher-return segments.
Niche structured products with poor client uptake are complexity without volume — dead weight on Daiwa’s P&L as support costs can exceed thin fee income; with Japan’s 65+ population at about 29.1% in 2024, shelf real estate must favor proven demand segments. Retire SKUs that fail quantitative hurdle tests and redeploy capital to high-turn offerings.
Underperforming branches, legacy on-prem stacks, small overseas boutiques and commoditized MM products are Dogs for Daiwa in 2024; prune bottom 25–30% SKUs and close low-density branches to redeploy capital to digital (Japan 65+ = 29.1%).
| Item | Metric |
|---|---|
| Branches | Low traffic, high fixed cost |
| IT | ~70% budget on maintenance |
| MM/Deposits | Compressed margins, low yield |
Robo-advisory is a growing category (global AUM ~$1T in 2024), but Daiwa’s share is not yet settled; younger clients (≈65% of Gen Z/millennials prefer digital advice in 2024 surveys) demand simple, low‑fee guidance. Invest in slick onboarding and tax‑smart rebalancing (can cut tax drag ~0.5–1% p.a.) or partner; industry economics typically need ≈$1B AUM to reach profitability, so scale fast or pull the plug.
Refinitiv reported a rebound in cross-border M&A activity in 2024, creating a growing opportunity set, but Daiwa’s offshore brand remains thinner than global bulge peers; targeted sector niches (tech buyouts, renewable infrastructure, healthcare) could drive a breakout. Focused hires and strategic alliances offshore would raise win rates; if win rates fail to approach peer levels within 12–18 months, redeploy capital to higher-return domestic businesses.
Appetite among wealth clients for private markets rose in 2024 as global private capital AUM exceeded $12 trillion (Preqin), but limited access, client education gaps, and compliance constraints slow flows. Packaging via feeder funds and tailored structures can unlock retail and HNW allocations while centralized diligence and rapid client education build trust. If uptake stalls, maintain boutique, high-touch offerings to protect margins and reputation.
SMEs need lighter, faster routes to capital; the global SME financing gap was about 5.2 trillion USD (IFC 2024) and demand is shifting to digital channels. Daiwa holds strong client relationships but lacks dominant platform share, so pilot a streamlined origination-to-investor workflow and track conversion rates and unit economics. Double down only if conversion and IRR targets are met.
Data and analytics monetization via research APIs is a Question Mark: demand for bite‑size insights rose over 50% in 2024, yet repeatable monetization is unproven. Productize datasets, run pricing A/B tests, and enforce conflict controls to protect broking/advice. If attach rates surpass ~10% this can become a scalable engine; if not, sunset experiments quickly.
Robo AUM ~1T (2024); need ≈1B AUM to break even, scale or exit. Private capital AUM >12T (2024); feeder funds can lift flows if uptake >target. SME financing gap ~5.2T (IFC 2024); pilot digital origination and measure CAC/payback. Data demand +50% (2024); productize if attach >10%.
| Opportunity | 2024 stat | Go/no-go metric |
|---|---|---|
| Robo | ~1T AUM | Reach 1B AUM |
| Private | >12T AUM | Feeder uptake |
| SME | 5.2T gap | CAC/payback, IRR |
| Data | +50% demand | Attach >10% |


