
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want to know which of Darling Ingredients’ products are pulling their weight and which are burning cash? Our BCG Matrix preview shows the shape of the portfolio — but the full report maps every product into Stars, Cash Cows, Dogs and Question Marks with the data to back it up. Purchase the complete BCG Matrix for quadrant-by-quadrant analysis, actionable recommendations, and ready-to-use Word and Excel files you can present to your board tomorrow. Skip the guesswork—get clarity fast.
Renewable diesel sits in Stars: 2024 demand for decarbonization fuels is high, and Darling leverages a leading waste‑lipid supply position and scale to capture share. The platform is capital intensive but the feedstock, logistics network and offtake agreements create a scaling flywheel. Continued feedstock access and capacity expansions are required to maintain leadership and the business can become a cash geyser as category growth normalizes.
Collagen and gelatin specialties sit in a high-growth quadrant as beauty, wellness and pharma demand climbs rapidly, with the global collagen market near 5 billion USD in 2024 and a ~6.5% CAGR forecast to 2030. Brand/spec trust and certified specs support pricing power versus commodity players. Prioritize R&D into bioactive formats, clean-label variants and clinical trials; maintain top-tier quality certifications to cement leadership.
Premium pet food remains a rocket ship, with premium products capturing over half of US pet food value sales in 2024 and outpacing total market growth by several percentage points as brands chase higher margins.
Nutritional specs plus sustainability stories resonate with major CPGs, enabling Darling to secure multi‑year supply and co‑development deals that lock in volume and improve EBITDA visibility.
Embedding traceability tech such as blockchain-enabled provenance and QR-backed audits wins RFPs, shortens sales cycles, and preserves margin integrity amid rising ingredient scrutiny.
Waste tallow and used cooking oil sit in the Stars quadrant as policy tightening in 2024 drove stronger low‑CI fuel demand; Darling’s control of feedstock sourcing and on‑site blending to spec gives a substantial commercial and compliance edge against refiners and traders. Competition for inputs is intense as market expansion attracts new entrants, raising collection and price pressure. Continued CAPEX in collection density and pre‑treatment protects margins and market share.
Renewable diesel, collagen, premium pet food and feedstock collection are Stars: Darling leverages 200 plants in 25 countries, renewable fuels scale and feedstock control. Collagen market ~5B USD (2024); premium pet >50% US value (2024). Continued CAPEX and long‑term offtakes required to sustain rapid growth and margin expansion.
| Segment | 2024 stat | Priority |
|---|---|---|
| Renewable diesel | High demand; scale | Expand capacity, secure feedstock |
| Collagen | ~5B USD market | R&D, certifications |
| Pet food | >50% US value | Premium SKUs, contracts |
 Detailed Word Document
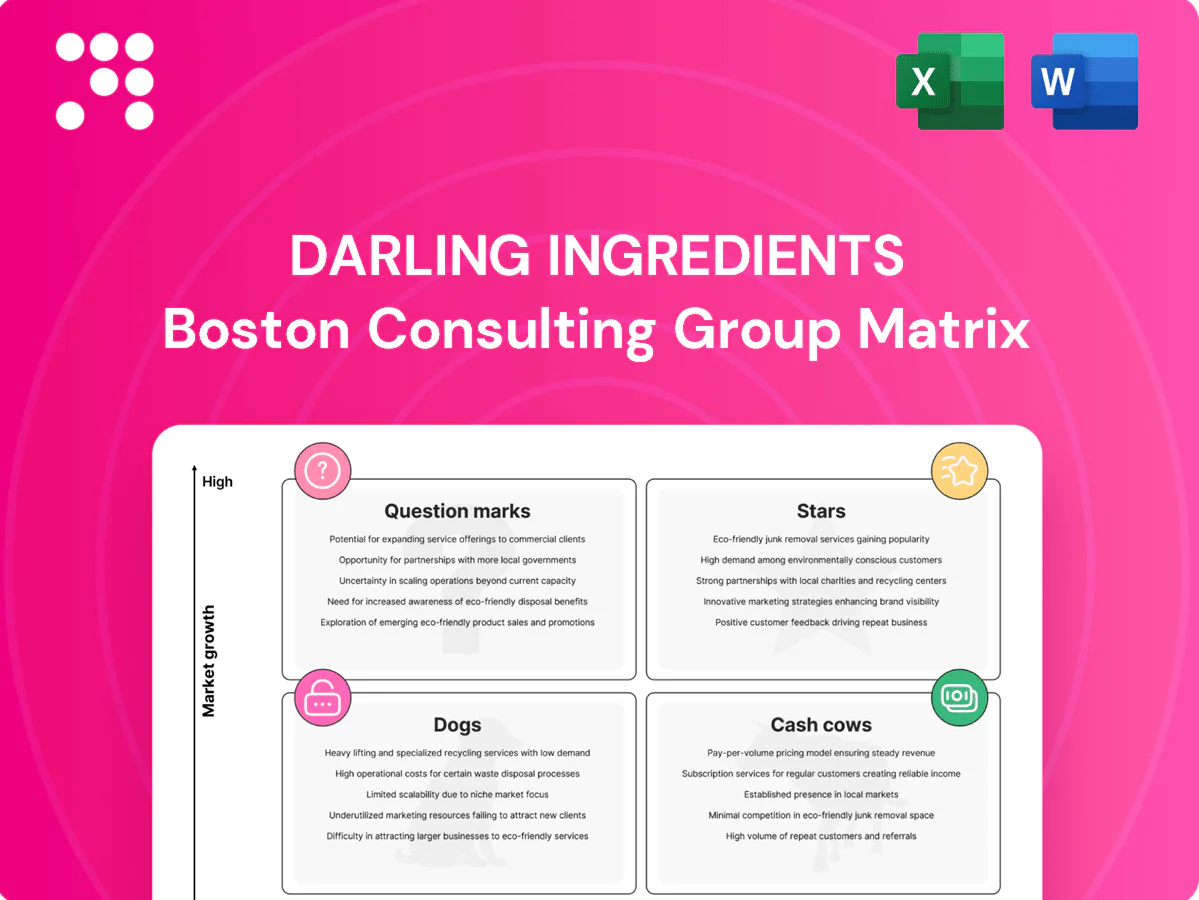
BCG analysis of Darling Ingredients' portfolio: identifies Stars, Cash Cows, Question Marks, and Dogs with strategic investment guidance.

 Customizable Excel Spreadsheet
One-page BCG matrix placing Darling Ingredients units in quadrants; clean, export-ready layout for C-level sharing and PowerPoint.
Edible tallow and shortening sit in Darling Ingredients BCG Cash Cows (DAR on NYSE): mature markets with steady volumes and entrenched processor relationships require low promotion and drive consistent free cash flow. High asset utilization and scale advantage keep margin stable, so prioritize logistics and energy efficiency to squeeze incremental cash. Maintain planned maintenance spend—milk the asset base but do not starve upkeep to avoid production downtime. Keep reinvestment focused on yield and cost per ton improvements.
Feed-grade proteins and meals serve as a cash cow for Darling, driven by stable demand from livestock and aquaculture tied to global compound feed production of roughly 1 billion tonnes annually; growth is low single digits (~1–2% a year). The business is contract-heavy with margin sensitivity—pennies per ton shift profitability—so throughput and yield optimization are priorities. Automation and heat-recovery projects increasingly raise free cash flow by lowering energy and labor costs.
Glycerin and oleochem by‑products are commodity but Darling’s scale (global rendering and fats network) hedges price swings; in 2024 these streams sustained mid‑teens EBITDA margins versus corporate average. Established buyers and indexed off‑take contracts deliver predictable cash flow and working capital. Strategy: maintain cost leadership, lock supply with indexed pricing, and only invest in debottlenecking rather than large expansions.
Pharma‑grade gelatin niches in Darling Ingredients are regulated, with sticky customers and slow category growth; high qualification hurdles and audit readiness keep rivals out, enabling pricing for reliability — the moat. Industry reports show the global gelatin market ~3.1B USD (2023) with low‑single‑digit growth into 2024, emphasizing uptime and compliance as value drivers.
Collection and logistics services are a cash engine for Darling Ingredients due to high route density and long-term contracts that secure predictable cash flow while the market itself is mature with incremental growth.
Continuous routing and fleet efficiency drive margins; harvesting operational savings and maintaining tight service levels protect profitability and customer retention.
Cash cows: mature, high‑utilization streams (tallow, feed proteins, glycerin, pharma gelatin, logistics) generating steady FCF; focus on yield, energy, uptime, indexed contracts and targeted debottlenecking to protect mid‑teens margins in 2024.
| Segment | 2024 stat | Margin | Growth |
|---|---|---|---|
| Tallow/shortening | Entrenched processors | Stable | Low |
| Feed proteins | Global feed ~1bn t | Stable | 1–2% |
| Glycerin/oleochem | Indexed contracts | Mid‑teens EBITDA | Low |
| Pharma gelatin | Market $3.1B (2023) | Premium | Low |
The file you’re previewing of the Darling Ingredients BCG Matrix is the exact document you’ll receive after purchase — no watermarks, no placeholders. It’s a fully formatted, analysis-ready report built for clarity and decision-making. Once purchased, the same editable file is delivered instantly to your inbox for printing or presenting. No surprises—just strategic insight you can use right away.
Low‑margin commodity fats are price‑taker segments with little differentiation, and in 2024 volumes showed flat-to-declining demand as customers shifted to higher‑spec bio‑ingredients. Capital is tied up in processing and storage for thin returns, compressing segment profitability versus Darling Ingredients’ specialty lines. These units are prime candidates for pruning or bundling only when such actions protect core customer contracts and margins.
Small, non-core regional by-product lines run in small plants chasing niche outputs without scale; Darling Ingredients operates more than 200 processing facilities worldwide, exposing many locations to subscale economics. Local competition and freight can quickly erase margins on low-density products. Turnarounds are pricey and distract management from core growth initiatives. Divestment or consolidation into nearby hubs preserves scale and reduces unit cost.
Odd lots that miss premium specs linger and leak cash, adding to Darling Ingredients’ FY2024 inventory burden amid $5.9B revenue. Rework and extra storage drive P&L pressure, often eroding 150–300 basis points of margin on affected SKUs. Better is to prevent, not fix: tighten QA gates to stop leaks early and shut down chronic low-turn SKUs to reclaim cash and margin.
Legacy contracts with fixed low pricing were written under different input economics and, after recent inflationary pressure, now often only cover variable costs, leaving margins near zero.
Priority is to renegotiate at the earliest contractual window or exit to prevent cash erosion; avoid chasing volume that masks unprofitable throughput.
Commoditized biodiesel sub‑segments are Dogs: where policy support is weaker margins often erode to near breakeven or negative in 2024, and production competes head‑to‑head with cheaper fossil diesel or imports, triggering cash‑trap dynamics in downturns; Darling should reduce exposure or pivot feedstock to higher‑value outlets like proteins or specialty fats.
Dogs: low‑margin commodity fats and commoditized biodiesel showed flat-to-declining volumes in 2024, tying up capital and eroding margins by 150–300 bps; FY2024 group revenue was $5.9B. Priority: prune, divest or repurpose feedstock to specialty lines and renegotiate weak legacy contracts to stop cash erosion.
| Segment | 2024 metric | Impact | Action |
|---|---|---|---|
| Commodity fats/diesel | FY2024 rev context: $5.9B | -150–300 bps margin | Divest/repurpose/renegotiate |
SAF feedstocks sit as a Question Mark for Darling: demand is ramping globally while Darling’s merchant share remains early-stage. Technology pathways and policy shifts (e.g., SAF blending mandates and incentives) are converging but capital needs are substantial. With strategic partners and secured offtakes Darling can move toward Star status. Validate via test offtakes, then scale with capital discipline.
Rapid consumer pull for upcycled beauty is creating a fast-growing Question Mark for Darling Ingredients, with the space still fragmented and share outside core collagen low. Brand partnerships and IP-led formulations can unlock premium pricing and margin capture. Invest in applications labs and substantiation of claims to scale—move quick or move on.
Category growth has been choppy but could rebound as alt‑protein investment totaled about $1.6 billion in 2023, signaling continued interest. Darling Ingredients leverages low‑cost hydrolyzed proteins and binders from rendering by‑products to supply texture and binding solutions. Market presence is early with uncertain payback timelines. Recommend small, targeted bets with co‑development milestones and pilot volume triggers to de‑risk exposure.
Biomaterials and bioplastics are a Question Mark for Darling Ingredients: regulatory tailwinds support growth, but industry scale and performance specs are still forming; bioplastics represented about 1% of global plastics production in 2023. Darling’s feedstock story aligns with circular narratives and could lower raw-material risk, yet market share is nascent and commercial volumes remain limited. Recommend pilots with anchor customers to de-risk before major capex.
Ag methane is a headline issue—livestock account for roughly 32% of anthropogenic methane—making feed additives a heated market where Asparagopsis trials have shown up to 80% enteric CH4 reductions; Darling Ingredients has feedstock precursors and distribution channels but holds only a tiny share today. Science, regulatory approvals and farmer adoption will define the slope; fund trials and kill fast if efficacy or uptake stalls.
SAF, upcycled beauty, alt‑protein, bioplastics and ag‑methane additives are Question Marks for Darling: high growth but nascent share, technology and capital risk. 2023–24 signals: alt‑protein VC $1.6B (2023), bioplastics ~1% of plastics (2023), seaweed trials up to 80% CH4 cut. Recommend pilots, offtakes, staged capex.
| Segment | 2023/24 metric | Status |
|---|---|---|
| Alt‑protein | $1.6B VC (2023) | Early |


