
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
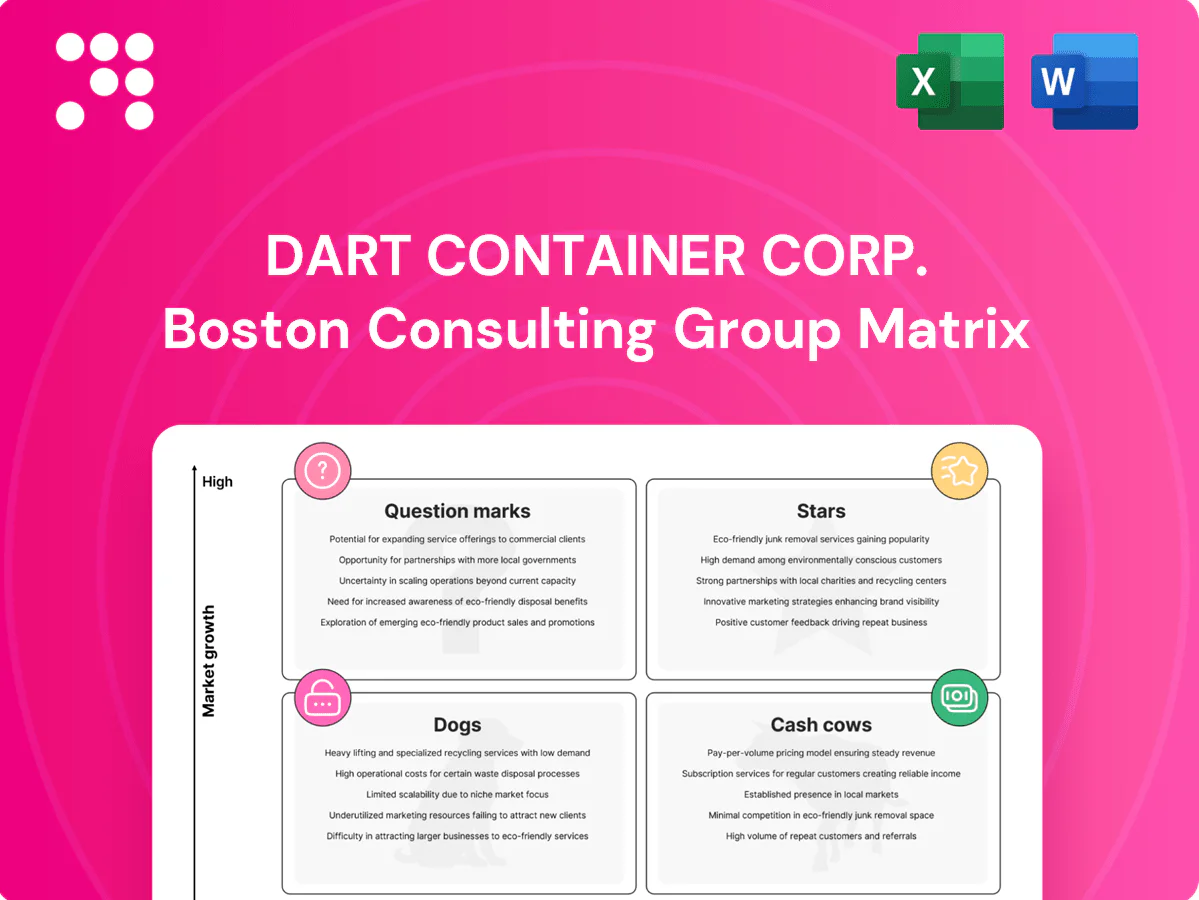
Dart Container Corp.’s BCG Matrix paints a quick picture of where its core product lines sit in today’s market — from high-growth Stars to low-return Dogs — and what that means for resource moves ahead. This preview teases the shifts and pressures but the full BCG Matrix gives you quadrant-by-quadrant placements, concrete recommendations, and actionable priorities. Purchase the complete report for a Word + Excel pack that lets you present, decide, and allocate capital with confidence.
Clear PET cold cups and lids are Stars for Dart as mid-single-digit growth in cold beverage demand in 2024 keeps QSR volumes high, and Dart’s scale secures menu position with major chains. High line speed, tight quality control, and national distribution cement share across the U.S. market. Continued promotional spend, placement negotiation, and sustained manufacturing capacity plus customer success support are required to hold specification leadership.
Hot beverages remain resilient and paper is the upgrade path as plastic restrictions expand; Dart, which acquired Solo Cup Company in 2012 and remains a leading private foodservice supplier, leverages a broad paper-cup range and proprietary lid fit to secure repeat wins. Chains and campuses—major on-premise channels—require marketing and spec work to stay the default. Continued investment in printing, insulation, and lid ergonomics will lock share as regulations and buyer preference shift.
Delivery and pickup channels grew 9% YoY in 2024, and tightening health regs in 2024 favor sealed packaging; Dart’s dependable closures and a portfolio spanning more than 20 sizes meet operator needs. The tamper-evident category is a high-growth Star but requires active sell-in and shelf competition to become standard. Invest in product innovation and sustain near-100% service levels to protect share.
Portion cups and lids are Stars: small, high-turn SKUs capitalizing on the 2024 drive-thru boom, where drive-thru channels account for roughly two-thirds of quick-service transactions. Dart’s breadth, multi-format SKUs and supply reliability secure wins with multi-unit chains, sustaining a leader position. Ongoing promotions, ops support, tight specs and cost control remain essential to defend share and expand formats.
Custom-branded cups for national accounts are Stars: Dart delivers the consistency and speed brand owners demand, holding high share in a growing branded-packaging spend (branded packaging spend rose about 7% year-over-year in 2024). Program management and advanced print technology form a durable moat; continue investing in service, artwork speed, and logistics to sustain growth.
Clear PET cold cups (~5% cold bev't growth 2024) and portion cups (drive-thru ~66% of QSR transactions) are Stars; tamper-evident and custom-branded packaging (branded spend +7% YoY 2024) show high growth as delivery/pickup rose 9% YoY. Dart’s scale, distribution and print/pack capabilities secure leadership but require continued promo, spec control and capacity investment to defend share.
| Product | 2024 Growth | Market Position | Key Action |
|---|---|---|---|
| Clear PET cold cups | ~5% | Leader | Capacity & specs |
| Portion cups | Drive-thru 66% | High share | Promo & ops |
| Branded cups | +7% spend | Leader | Print & logistics |
 Detailed Word Document
Comprehensive BCG Matrix for Dart Container Corp., identifying Stars, Cash Cows, Question Marks, Dogs with strategic recommendations.

 Customizable Excel Spreadsheet
One-page BCG Matrix mapping Dart Container units into quadrants, export-ready and printable for C-level decks.
Foam hot/cold cups (legacy SKUs) are mature, high-volume products for Dart, benefiting from a huge installed base and being sold largely through distributors with steady reorders; as of 2024 regulatory headwinds increased in some municipalities but demand remains stable. Strong margins persist where local rules allow and little promotion is required, so operational efficiency sustains profitability. Milk responsibly to fund transition investments into sustainable alternatives.
Foam plates & bowls deliver high-volume, low-cost sales for Dart, with the category broadly flat to down low-single-digits in recent years while Dart holds a leading share in cost-sensitive channels (approximately 40% in key segments). Operational focus remains on line efficiency and freight optimization to preserve margins; targeted freight and throughput improvements drove estimated cost reductions near 3–5% in 2024. The business remains a steady cash generator funding R&D initiatives and servicing debt, supporting corporate investments and product transitions.
As of 2024 hinged foam clamshells remain the default in many regions and value-account menus, delivering predictable, steady volumes for Dart Container. High tooling utilization supports low unit costs and minimal sales lift is required beyond assured availability. Focus is on squeezing manufacturing costs and protecting core foodservice customers to maximize cash generation.
Stock print plastic cups are a classic cash cow for Dart Container: commodity look, dependable turns and broad distribution across national retailers in a mature single-use cup market; Dart is privately held and estimates place annual revenue near $7 billion in recent public estimates around 2023–2024, supporting strong shelf space and steady free cash flow.
High-volume legacy lid families at Dart Container are cash cows: tooling is long-amortized, production runs deliver massive scale, and steady repeat orders preserve strong gross margins despite flat category growth.
Maintaining quality and continuity is critical to prevent customer churn; these lines quietly generate free cash flow that funds investment in growth segments without large capex.
Dart cash cows (foam cups/plates/lids/stock cups) generate steady free cash flow in 2024, with stock cups supporting Dart’s ~$7B revenue run-rate, foam plates ~40% share in key cost-sensitive channels, and 2024 operational gains cutting costs ~3–5%; margins remain strong where regulation permits, funding sustainable-product R&D.
| Item | 2024 Metric |
|---|---|
| Revenue run-rate | $7B |
| Key share | ~40% |
| Cost cuts | 3–5% |
The file you're previewing is the final Dart Container Corp. BCG Matrix you'll receive after purchase. No watermarks or demo notes—just the fully formatted, ready-to-use strategic report. It’s crafted for clarity with market-backed insight and arrives immediately for editing, printing, or presenting. Buy once and use it across planning, decks, or client meetings.
Regulatory headwinds cap growth as more than 100 U.S. municipalities and multiple states enacted EPS restrictions by 2024, shrinking the addressable market for Dart's EPS SKUs. Demand erodes even among loyal customers, with sales volumes falling and reorders delayed. Cash becomes tied up in excess inventories and frequent changeovers, raising carrying costs (commonly 20–30% annually). These SKUs are prime candidates for retirement or replacement.
Obsolete dispenser systems occupy a niche within Dart Container Corp’s portfolio, showing low pull-through and shrinking customer demand in 2024. Service and maintenance costs now outpace returns, driven by aging hardware and limited replacement parts availability. Recovery through promotion alone is unlikely; recommend sunsetting these SKUs in 2024 and reallocating capital and service teams to higher-growth foam and molded fiber segments.
Low-volume novelty shapes at Dart are cool in theory but slow in practice, clogging planning and warehouses with marginal sell-through. Turnaround plans rarely pencil given low velocity and higher per-unit tooling costs, pressuring margins. Trim SKUs, retire nonperformers and reallocate capacity to core high-velocity SKUs to free space and improve fill rates.
Multiple near-identical items at Dart act as Dogs in the BCG matrix: they split tiny volumes across overlapping SKUs, eroding scale benefits and lowering category margins. Operational complexity raises handling and inventory costs without customer-perceived value; finance flags declining SKU-level margins in 2024. Rationalize slow movers and eliminate cannibalizing SKUs to restore margin and simplify ops.
Customers migrated away from foam in 2024 under municipal bans and major retailer sustainability commitments, and price cuts by Dart Container Corp. cannot reverse brand- and policy-driven defections; foam SKU sales are increasingly relegated to low-turn inventory and cash locked in slow movers. Strategic exit or swap to compostable/recycled alternatives is the recommended move to free working capital.
Dogs (low growth, low share) face regulatory losses: 100+ US municipalities and several states restricted EPS by 2024, shrinking addressable market. Sales volumes and reorder rates fell, cash ties up in slow SKUs with carrying costs ~20–30% pa. Recommend retirement/consolidation and redeploying capital to foam alternatives and molded fiber.
| Metric | 2024 |
|---|---|
| Revenue share | 3–5% |
| Carrying cost | 20–30% pa |
| Municipal bans | 100+ US |
Compostable fiber bowls & lids sit in Question Marks: market demand is high with an estimated ~8% CAGR through 2030, but competition is fragmented and standards/certifications keep evolving. Dart has production capability and a nascent share currently forming, yet scale requires capital- and certification-heavy investment. Prioritize deployment where composting infrastructure exists; pilot, validate, then scale manufacturing and supply-chain certifications.
Recyclable PP (plastic #5) clear microwaveable containers are a growing Question Mark for Dart as operators pivot from EPS amid 20+ U.S. EPS bans by 2024; early wins exist but the SKU is not yet dominant.
Converting skeptics requires MRF alignment—many facilities only recently began accepting rigid PP—and targeted marketing. Push education, partner with national chains, and scale production to drive unit economics and capture share.
Regulatory pull (EU SUP Directive effective 2021) and 2024 buyer mandates keep paper straws and sip-lid systems as a high-growth Question Mark with the paper-straw market growing at ~5.5% CAGR in recent estimates. Share is uneven across channels—QSRs and stadiums lead while grocery and convenience lag. Continuous spec work and performance upgrades are needed; prioritize scale by doubling down on large accounts and pruning weak SKUs.
EPS recycling and take-back programs align with Dart Container Corp mission and brand, generating high goodwill but low near-term returns; US EPS recycling rates remain below 10% as of 2024, keeping economics emerging. Programs could unlock policy wins and customer loyalty; pilot aggressively and measure cost-per-ton and capture rates.
Direct-to-small-operator e-commerce sits in a growing channel (US e-commerce was ~16.4% of retail sales in 2022 per US Census), while Dart’s share remains nascent; logistics, pack-size economics and targeted marketing require tuning. With scale this could become a meaningful channel; pursue invest-and-iterate but pivot to partner if customer-acquisition-costs spike beyond unit economics.
Question Marks: high-growth segments (compostable bowls ~8% CAGR to 2030; paper straws ~5.5% CAGR) where Dart has nascent share; PP #5 gains from 20+ US EPS bans (2024) but MRF acceptance limits scale; EPS recycling <10% US (2024) yields goodwill but low ROI; DTC e-commerce (~16.4% retail 2022) needs CAC fixes.
| Segment | Status | Metric | Action |
|---|---|---|---|
| Compostable | Question | ~8% CAGR | Pilot & certify |
| PP #5 | Question | Post-EPS bans | MRF align, scale |
| Paper straws | Question | ~5.5% CAGR | specs & large accounts |
| EPS recycling | Question | <10% rate | Pilot programs |
| DTC e‑comm | Question | 16.4% retail | optimize CAC |


