
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
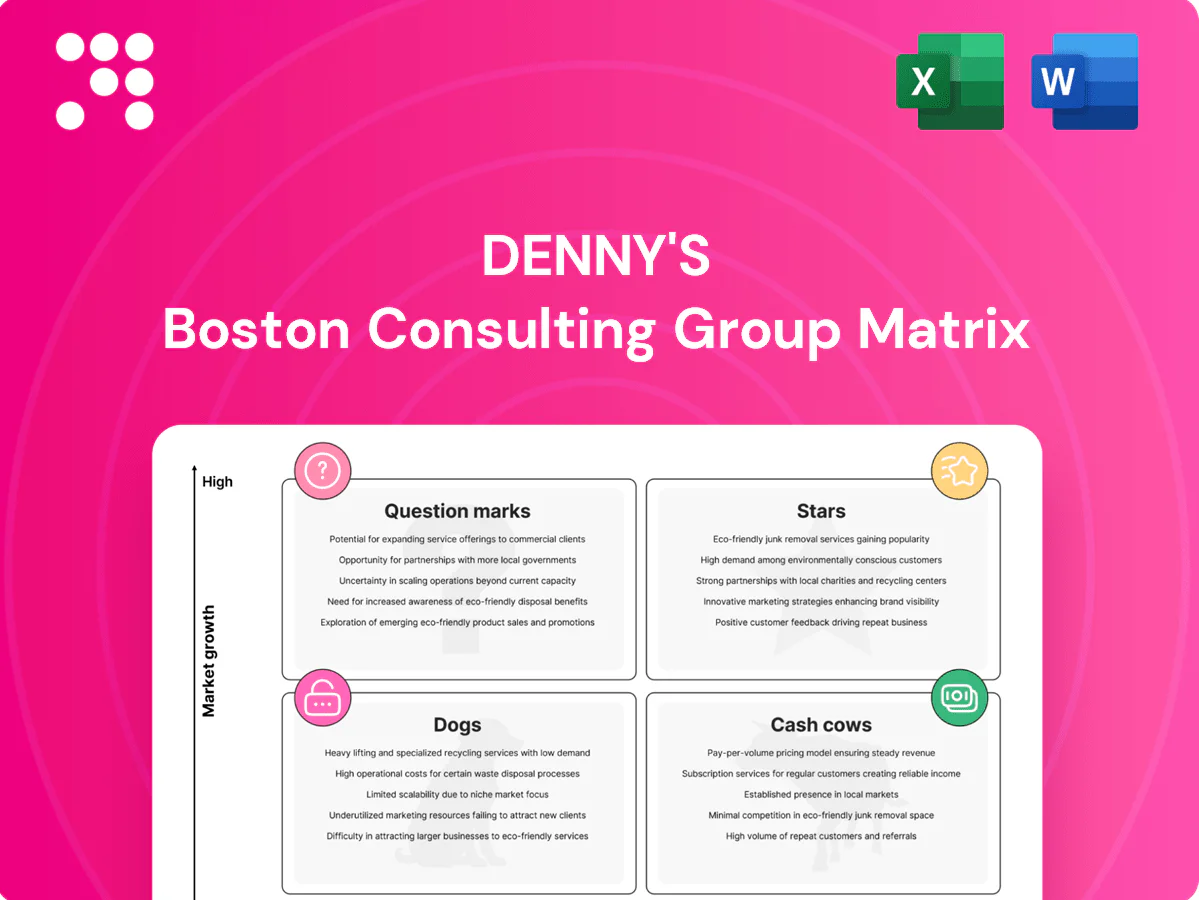
Want the straight story on Denny’s portfolio — what’s winning, what’s bleeding margins, and what needs a rethink? This quick peek shows the shape of their BCG Matrix; buy the full report for quadrant-by-quadrant placements, data-backed recommendations, and a ready-to-use Word report plus an Excel summary. Get instant access and stop guessing—use a clear strategic roadmap to guide investment and product moves now.
24/7 Breakfast Core is Denny’s signature advantage: with over 1,600 restaurants worldwide (2024) it captures high share in the anytime-breakfast niche as routines shift toward flexible schedules. It leads the category but requires continuous promotion and strategic placement to stay top-of-mind. Sustained marketing and menu optimization can mature this Star into an even bigger cash engine.
Iconic Grand Slam and value bundles pull traffic, defend share and travel well across Denny's portfolio—leveraging over 1,600 restaurants worldwide as of 2024 to amplify national awareness. They consume promotional cash but consistently drive new-guest trials and repeat visits, outperforming non-bundle occasions on visit frequency. As the market normalizes these offers are positioned to hold share and pivot from traffic drivers to margin leaders.
Delivery and late-night demand are a Stars for Denny’s as off-premise channels and overnight dining accelerate; Denny’s operated about 1,500 restaurants worldwide in 2024, giving scale to capture late-night share. Partnerships with third-party delivery platforms and tight ops support are required to keep service reliable and costs controlled. Consistent execution across stores compounds over time into durable market share gains.
Decades of brand awareness position Denny's as a leader in the family-diner lane, with about 1,600 locations worldwide (2024). Equity is maintained through menu innovation, remodel programs and targeted media spend. Continued same-store momentum and franchise growth investments aim to convert Stars into tomorrow's cash cow.
Urban, travel-corridor, and college-adjacent Denny's stores are Stars in the BCG matrix, driving outsized transactions in expanding micro-markets; in 2024 Denny's operated roughly 1,600 restaurants with these locations often delivering the highest unit-level sales. They need targeted staffing, upgraded POS/online-order tech, and remodel capital to sustain volume and margins. Protect and invest in them and they will anchor system-wide growth.
Stars: 24/7 breakfast, delivery/late‑night and urban/college locations drive higher share and frequency; investments in remodels, POS/online and targeted marketing aim to convert these Stars into cash cows. Denny’s operated about 1,600 restaurants worldwide (2024) and leverages scale to defend and grow these segments. Continued capex and promo discipline are required.
| Metric | 2024 | Note |
|---|---|---|
| Locations | ~1,600 | systemwide |
| Key Stars | Breakfast/Delivery/Urban | high share drivers |
| Investment | Remodels/Tech/Marketing | to sustain growth |
 Detailed Word Document
Clear BCG Matrix for Denny’s: identifies Stars, Cash Cows, Question Marks, Dogs and recommends invest, hold or divest per unit.

 Customizable Excel Spreadsheet
One-page Denny's BCG Matrix placing units in quadrants for quick portfolio decisions; export-ready for slides and C-level decks.
Franchise royalties and fees are a high-share, low-growth cash cow for Denny's, generating steady cash from a system-wide sales base that exceeded $3 billion in 2024 and requiring minimal incremental investment beyond brand support and standards enforcement.
Legacy highway and suburban Denny's units benefit from stable traveler and family demand, delivering consistent cash flow even as category growth is modest. Operational tune-ups and selective remodels have shown measurable flow-through, improving unit-level margins without heavy capital. With roughly 1,600 restaurants in 2024, prioritize milking these assets and avoid overinvestment in full-scale expansion.
Coffee and beverage attach are high-margin add-ons with predictable velocity, often delivering gross margins near 60% and contributing 10-15% of incremental store-level profits. Simple operations and low complexity drive strong contribution with modest labor impact and minimal equipment cost. Maintain sharp pricing and tight bundles to protect margin and sustain attach rates around 15-25%.
Pancakes, eggs and burgers are Denny’s core All-Day Staples: high-volume SKUs with standardized recipes, bulk purchasing and rapid prep that generate steady margins despite low category growth.
These items drive frequent repeat visits and predictable cash flow; small efficiency gains in prep or supply chain typically produce outsized EBITDA uplift.
Gift Cards & Light Loyalty deliver recurring, low-CAC revenue in mature channels, converting steady purchase flows into cash with minimal marketing spend; industry U.S. gift card sales exceeded 200 billion dollars in 2023, underpinning predictable volume. Breakage economics (industry average ~4–6% unredeemed) produce margin-accretive revenue with limited upkeep. This reliable cash funds heavier marketing and remodel investments across the system.
Franchise royalties, legacy highway/suburban units and All-Day Staples (pancakes, eggs, burgers) are high-share, low-growth cash cows for Denny’s, delivering steady cash from system-wide sales >$3B and ~1,600 restaurants in 2024. Coffee/beverage attach (gross margins ~60%, 15–25% attach) and gift cards (breakage ~4–6%) boost store-level profits with minimal capex, funding remodels and marketing.
| Asset | 2024 Metric | Role |
|---|---|---|
| System sales | >$3B | Core cash |
| Units | ~1,600 | Stable cash flow |
| Coffee attach | ~60% GM, 15–25% attach | High-margin add-on |
| Gift cards | Breakage 4–6% | Low-CAC revenue |
The file you're previewing here is the exact BCG Matrix report you'll receive after purchase. No watermarks, no demo content—just a fully formatted, analysis-ready document built for strategic decision-making. After buying, the same file is available instantly for editing, printing, or presenting. It’s professionally designed and market-informed, ready to plug into your planning or client decks.
Dogs: Chronic underperforming units have low share in stagnant trade areas that rarely rebound; as of 2024 Denny's operates primarily via franchising, concentrating exposure in mature markets. Turnarounds consume capital and management time, with remodels and marketing often requiring six-figure investments per unit. These units are prime candidates for closure or refranchising to protect margins and redeploy capital.
Heavily dated boxes at Denny's (≈1,650 restaurants) depress guest experience and slow labor throughput, raising operating costs. Remodels typically run $200k–$500k per unit while casual-dining same-store sales hovered around 0–1% in 2024, making payback periods long. In flat markets, capex often outruns incremental revenue, so strategic exits can outperform sunk-capex remodels.
Slow-selling niche SKUs at Denny's—menu items with low turns and long prep—clog the line and increase ticket times. These items neither drive traffic nor margin: 2024 industry analyses show peripheral SKUs can comprise ~15% of menus while contributing <5% of sales. Trimming tails can free roughly 8–12% of labor hours and reduce inventory carrying by about 10%, improving throughput and margins.
Late-Night High-Risk Sites: security, shrink, and staffing often drive a 10–15% incremental cost burden on late-night shifts in weak local demand areas; Denny’s internal operations reviews in 2024 show late-night shifts break even at best and frequently run at negative contribution margins, so reduce hours or exit the trade area.
Print-heavy couponing is a Dog for Denny's: it discounts traffic without improving menu mix, sustaining costs while reducing spend quality; Denny's 2024 marketing review flagged declining print ROI versus digital pilots.
Costs linger in postage and production as guest value shifts; targeted digital channels in 2024 showed higher measurable ROI and better customer segmentation.
Dogs: underperforming Denny's units in mature markets drag margins; remodels $200k–$500k versus casual-dining SSS ~0–1% in 2024, making paybacks long. Late-night/print-heavy sites add 10–15% cost burdens and weak ROI; refranchising, closures, cut hours, and shift to digital improve returns.
| Metric | 2024 | Action |
|---|---|---|
| Units/Remodel | ≈1,650; $200k–$500k | Refranchise/close |
International franchising sits in Denny’s Question Marks: global systemwide restaurants total roughly 1,600, but international locations represent a single-digit share, indicating high growth potential yet low current market share.
Success hinges on rigorous partner selection, localized menus and brand seeding; prioritize markets where unit economics—AUVs, EBITDA margins and payback periods—meet benchmarks and scale quickly.
Allocate measured investment to prove unit-level economics (target franchisee IRR thresholds) and divest rapidly where KPIs underperform; leverage franchise royalties and development fees to fund further expansion.
Off-premise and delivery demand is rising—US online food delivery market reached about $52.7 billion in 2023—making virtual brands a Question Mark for Denny’s as share remains nascent versus incumbents. These concepts can boost late-night and fill delivery radii, but introduce real operational complexity and unit-level cost pressure. Run strict test-and-scale pilots with clear contribution-margin hurdles before wide rollout.
Consumer growth is clear—the global plant-forward market is growing at roughly a 10% CAGR toward 2030 and over 40% of consumers report trying plant-forward options. Denny’s share remains nascent with only limited pilots to date, so win by scaling a few hero items with verifiable sourcing and supply-chain transparency. If adoption lags, cut quickly to avoid menu bloat and margin drag.
Mobile App Personalization sits as a Question Mark: 2024 industry benchmarks show personalized push CTRs up ~35% and incremental revenue lifts of 10–20%, but Denny’s current share remains limited. Realizing ROI needs tight product, CRM, and ops coordination plus analytics to attribute lift. Finance should fund rapid A/B experiments, scale winners, and double down on repeatable lift to move this into a Star.
Catering & Group Occasions is a Question Mark for Denny’s: workplace breakfasts and events are rebounding but Denny’s penetration remains low versus competitors; Denny’s operates roughly 1,500 restaurants (2024) so scale is possible. Investment needed in packaging, delivery windows, and order-ahead technology to win share. If unit-level margins clear the company's hurdle rate, scale; if not, park the initiative.
Question Marks: international franchising (~1,600 systemwide, ~1,500 US in 2024; international <10% share) and virtual/delivery (US delivery $52.7B in 2023) show high growth potential but low share; plant-forward (~10% CAGR to 2030) and mobile personalization (CTR +35%, rev lift 10–20% 2024) need tight tests and KPIs; allocate measured investment, scale winners, cut laggards.
| Initiative | 2024 KPI | Action |
|---|---|---|
| Intl franchising | Intl share <10% | Selective markets, prove unit IRR |
| Delivery/virtual | $52.7B (2023) | Pilot contribution-margin hurdles |
| Plant-forward | ~10% CAGR to 2030 | Scale 2–3 hero items |
| App personalization | CTR +35%, rev +10–20% | Rapid A/B tests, scale winners |


