
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
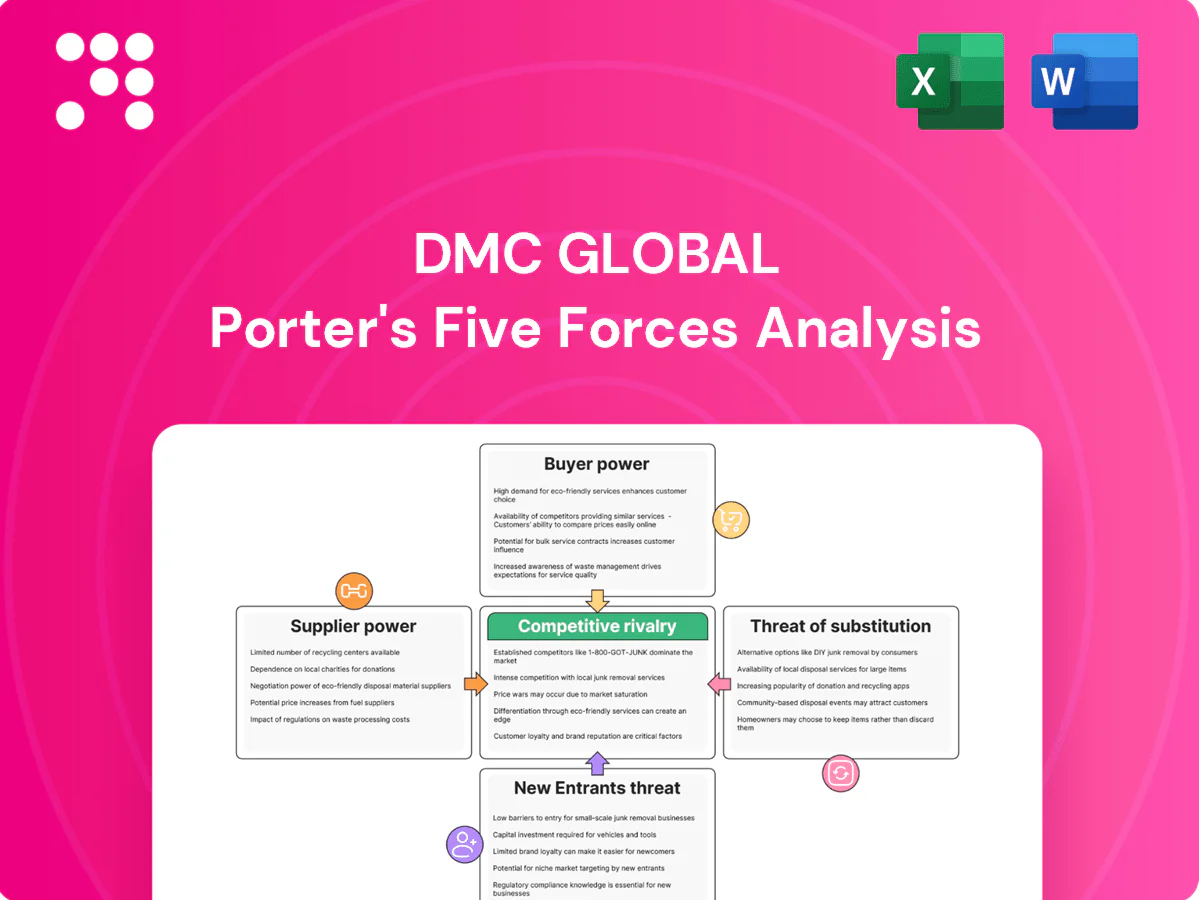
DMC Global’s Porter's Five Forces snapshot highlights competitive intensity, supplier and buyer power, threat of new entrants and substitutes, and strategic positioning across its niche industrial markets. This brief reveals key pressures but omits detailed ratings, visuals, and implications. Unlock the full Porter's Five Forces Analysis to access force-by-force scores, data-driven insights, and ready-to-use slides for investment or strategy decisions.
Many DMC products rely on specialty steels, alloys, explosives and engineered components with often fewer than five qualified suppliers, concentrating bargaining power upstream. Qualification cycles are lengthy, typically 9–18 months, which raises switching costs and operational risk. Long-term contracts and dual-sourcing reduce exposure but do not fully eliminate supplier leverage or lead-time vulnerability.
Energy and infrastructure end-markets require certified inputs and full traceability, allowing vendors meeting API, ISO and project-specific specs to command price premiums and tighter contractual terms. Supplier nonconformance creates downstream warranty, safety and liability exposures that can force costly recalls or rework, increasing buyer risk. During tight capacity cycles this certification-driven scarcity elevates supplier leverage over pricing and lead times.
Global supply chains for metals, chemicals and custom parts expose DMC to lead-time risk, and in 2024 prolonged ocean and air transit disruptions continue to tighten capacity. When freight or capacity tightens, suppliers have been able to pass through higher costs, forcing DMC to hold greater safety stock or pay expedite premiums that raise working capital. The harder it becomes to run just-in-time, the more supplier influence grows, pressuring margins and procurement flexibility.
Volatile steel, aluminum and energy inputs shifted supplier bargaining in 2024: US HRC averaged about $900/ton, LME aluminum near $2,300/ton and WTI crude roughly $78/bbl, prompting suppliers to adjust prices faster than many DMC customer contracts reset; hedging and indexing clauses partially offset risk but basis and timing mismatches persist, compressing margins during input upswings.
Proprietary tooling and co-developed parts tie DMC Global operations to specific vendors, making switches costly due to requalification, capital expenditure and downtime; suppliers exploit this embedded friction to secure stronger terms. Collaborative R&D partnerships reduce some risk, but persistent tooling lock-in sustains supplier bargaining power and price resilience into 2024.
Specialty steels, alloys and certified components have <5 qualified suppliers, 9–18 month quals and high switching costs, concentrating supplier power. 2024 inputs: US HRC ~900/ton, LME Al ~2,300/ton, WTI ~78/bbl, enabling rapid repricing and margin pressure. Tooling lock-in and certification premiums sustain leverage despite dual-sourcing and hedges.
| Metric | 2024 Value |
|---|---|
| US HRC | $900/ton |
| LME Aluminum | $2,300/ton |
| WTI Crude | $78/bbl |
 Detailed Word Document
Concise Porter's Five Forces analysis tailored to DMC Global, uncovering competitive rivalry, supplier and buyer power, threat of new entrants and substitutes, plus strategic implications for pricing and profitability; includes actionable insights on disruptive threats and barriers that protect DMC's market position.

 Customizable Excel Spreadsheet
One-sheet Porter's Five Forces for DMC Global that clarifies competitive pressures at a glance, with adjustable force levels and an interactive radar chart to translate analysis directly into pitch decks or strategic reports.
Energy operators, EPCs and large fabricators buy at scale—ExxonMobil and Shell set 2024 CAPEX plans above $20B each, concentrating purchasing power and driving competitive bid processes that pressure margins. Multi-year frame agreements commonly include volume discounts and strict SLAs, and aggregated contract volumes give buyers meaningful leverage over suppliers like DMC Global.
Customers prize uptime, safety, and precision, commonly demanding service levels of 99.9% availability and ISO-certified safety compliance, driving rigorous KPIs. This translates into performance-based negotiations with contractual penalties often tied to missed SLAs. Vendors must provide engineering support and rapid delivery windows to meet these KPIs. Buyers leverage these requirements to extract value-added services at minimal incremental cost.
For several DMC Global product lines multiple qualified providers exist, enabling buyers to run competitive tenders to extract better price and terms. Where DMC demonstrates clear technical differentiation and patented solutions, it can better defend margins. In more commoditized specifications, buyer power increases materially, compressing pricing and contract leverage. This dynamic makes product differentiation central to margin resilience.
Engineered solutions with integration and certification create high switching costs through technical lock-in, multi-year service contracts, and installed-base dependencies, while standard components and architectural products remain easily substitutable and price-sensitive. Buyers with low switching barriers use that leverage to negotiate better terms, though niche contracts and certified integrations temper customer power.
Demand cyclicality reduces buyer leverage in upcycles as urgency rises, while downturns in energy and construction shrink order visibility, prompting buyers to delay purchases and demand concessions; DMC’s 2024 backlog composition (instrumentation and engineered products vs. services) moderates these swings and alters negotiation dynamics.
Large energy buyers concentrate purchasing power—ExxonMobil and Shell set 2024 CAPEX above $20B each, driving competitive bids that compress supplier margins.
Buyers demand 99.9% uptime, ISO safety and performance penalties, using service requirements to extract value-added terms.
Where DMC shows patented differentiation switching costs are high; commoditized lines face intense price pressure.
| Metric | 2024 |
|---|---|
| Major buyer CAPEX | Exxon/Shell >$20B |
| Typical SLA | 99.9% availability |
This preview shows the exact Porter’s Five Forces analysis for DMC Global you'll receive immediately after purchase—no placeholders or samples. The document is fully formatted and professionally written. It is ready for instant download and immediate use the moment you buy. No mockups; this is the actual deliverable.
Each DMC segment competes with specialized peers and in 2024 faced intense niche rivalry focused on delivery, reliability, and application engineering. Niche leadership in specific product lines allows local pricing power and contract wins. Regional competitors, however, undercut bids in price-sensitive tenders, compressing margins on commoditized orders. Sustained differentiation remains key to margin resilience.
Performance gains in safety, precision and materials drive intense rivalry as rivals boosted R&D to roughly 5–8% of revenue in 2024 to chase specs and certifications. Firms pursue ISO/industry certifications and patents that create temporary moats, but engineering workarounds and licensing shorten protection windows. Time-to-market and 12–18 month field validation cycles remain decisive for winning contracts and pricing power.
Quick-turn manufacturing and field support can win orders as lead-time becomes the purchase driver; industry surveys in 2024 found more than 50% of buyers rank lead time as a top decision factor. Competitors now offer consignment, kitting, and digital diagnostic tools to cut downtime and accelerate reorders. Lead-time compression is a clear battleground, intensifying rivalry when capacity constraints push delivery times out and margins down.
Standardized parts in DMC Global’s end-markets face intense price-led rivalry, especially in global tenders; in 2024 bidders increasingly undercut on unit price while differentiation pivots to lifecycle value and reliability to protect margins. Currency swings and low-cost-region entrants amplify pressure, and discounting spikes during demand slowdowns.
In safety-critical markets brand trust drives contract awards and DMC Global (NASDAQ: BOOM) relies on its safety record; rivals leverage certifications and case histories to win business. Incidents or recalls can rapidly shift share—industry peers have seen contract losses worth millions after single events. Maintaining a clean track record is central to rivalry outcomes and bidding success.
Competitive rivalry in 2024 was intense: niche engineering and lead-time (50%+ buyers) drove wins, while price-led global tenders compressed margins; R&D rose to ~5–8% of revenue to chase specs. Certifications and safety records created short-lived moats; discounting spiked in slow demand.
| Metric | 2024 |
|---|---|
| Revenue (BOOM) | $492M |
| R&D | 5–8% rev |
| Buyers citing lead-time | >50% |
Advances in composites, specialty coatings and additive manufacturing — with the global composites market near $115B and the AM industry ~ $21B in 2024 — can substitute clad metals or machined parts by delivering 10–30% weight or lifecycle-cost savings. Process redesign and part consolidation can eliminate assemblies and reduce BOM spend. Successful pilot trials often displace incumbents in oil & gas and aerospace.
Operational substitutability in energy services means alternative completion strategies and workflow changes can reduce demand for specific DMC Global tools; industry-wide energy services spending recovered to roughly $140 billion in 2024, shifting procurement priorities. Digital monitoring and predictive maintenance now cut physical interventions, while operators adopting automated workflows reallocate budgets toward software and integrated services. This functional substitution risk pressures margins beyond direct product swaps as firms favor bundled, multifunctional solutions.
Large customers increasingly in-sourced critical components in 2024, allowing them to bypass suppliers for strategic items and substitute external spend with internal capability. This vertical integration reduces dependency on suppliers like DMC Global and raises customers’ bargaining leverage, pressuring margins. The shift accelerates when key buyers control design and production of specialized components.
Industry moves to standardized interfaces enable plug-and-play alternatives, and modularity lowers switching costs while speeding qualification of substitutes; industry reports in 2024 show modular designs can cut qualification time by up to 30%. Vendors must keep pace with open standards to avoid displacement as openness erodes incumbency advantage.
Outcome-based contracts and rentals increasingly replace capital purchases as customers prefer buying uptime and performance over ownership; in 2024 the Equipment-as-a-Service trend grew strongly, with the EaaS market estimated around $50 billion and adoption rising ~18% year-over-year. This reallocates spend to providers offering uptime guarantees and pushes buyers toward service bundles, making traditional product-only offerings vulnerable to substitution.
Substitutes from composites, additive manufacturing and specialty coatings (composites ~$115B, AM ~$21B in 2024) can cut part weight/cost 10–30% and displace machined/clad parts. Process redesign, modular open standards and EaaS growth (~$50B, +18% YoY) reduce switching costs and reallocate spend to performance-based providers, raising substitution risk and margin pressure for DMC Global.
| Factor | 2024 metric | Impact |
|---|---|---|
| Composites | $115B | 10–30% weight/cost savings |
| Additive Manufacturing | $21B | Part consolidation |
| EaaS | $50B, +18% YoY | Capex→Opex shifts |
| Modularity | ~30% faster qualification | Lower switching costs |
| Energy services spend | $140B | Procurement reprioritization |
New entrants must secure stringent industry certifications and demonstrate field-proven reliability, which often requires multi-year testing and audited quality systems. Failures expose firms to substantial legal liabilities and reputational damage, increasing insurance and compliance costs. These factors raise time-to-market and capital requirements, with barriers especially high in safety-critical niches like energy and mining.
Precision manufacturing, testing and specialized tooling commonly require initial capital outlays often exceeding $1 million per production line and testing cell, while achieving cost-competitiveness typically needs scale in the tens of millions of annual revenue; entrants also face steep learning curves and working-capital needs often spanning 60–120 days, deterring smaller players.
Winning approval from major operators and EPCs typically takes years and depends on documented reference projects and track records; without them new suppliers seldom pass qualification gates. Incumbent relationships and an installed base create strong inertia, making procurement teams reluctant to change. Switching to unproven suppliers rarely occurs except in price-only buys, limiting new-entrant traction.
Proprietary designs, process know-how and trade secrets create durable barriers to entry for DMC Global; patents give legal protection for about 20 years, but tacit operational knowledge often outlasts patents and preserves advantage. Reverse engineering rarely guarantees equivalent field performance, raising buyer risk and reducing credible entrants. This combination slows credible entry and raises required investment and time to compete.
New entrants timing entry during downturns face severe demand shocks; fixed costs and underutilized capacity quickly strain cash flows while incumbents can cut prices to test newcomers’ resolve, raising effective barriers to entry.
Volatility in end markets elevates entry risk and acts as a filter, leaving only well-capitalized firms able to sustain losses through cyclical troughs.
Entrants face multi-year certification and field trials, raising time-to-market and compliance costs. Typical capex exceeds $1m per production line and competitive scale often needs ~$30m annual revenue; working-capital cycles run 60–120 days. Patents offer ~20-year protection while tacit know‑how and incumbent contracts preserve barriers, especially in cyclical 2024 end markets.
| Barrier | 2024 Typical |
|---|---|
| Capex per line | >$1m |
| Competitive scale | ~$30m rev |
| Working capital | 60–120 days |
| Patent term | ~20 years |


