
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Donear Industries shows strong brand recognition and a diversified textile portfolio, but faces margin pressure from raw material volatility and concentrated domestic dependence. Opportunities in premiumization, branded retail expansion, and exports could fuel growth, while intense competition and supply-chain risks loom. Want the full story behind Donear’s strengths, risks, and growth drivers? Purchase the complete SWOT analysis for a professionally written, editable report and Excel matrix to plan and invest with confidence.
Donear Industries’ diversified fabric portfolio across suiting, shirting and denim reduces dependence on a single category, smoothing demand cyclicality and seasonality. A broader catalog facilitates cross-selling to retail and institutional buyers and improves mill utilization. Range across value to premium price points enables entry into adjacent segments, supporting resilient revenues across geographies.
Integrated manufacturing know-how—backed by 30+ years in suiting and multiple in-house plants—lets Donear control quality and cut costs across yarn-to-finish operations. End-to-end process integration shortens lead times for wholesalers and brands, enabling rapid sampling and customization aligned to fast fashion cycles. Consistent production standards strengthen credibility with distributors and trade partners.
An extensive distributor–retailer network widens Donear Industries reach across India’s fragmented apparel markets, ensuring broader market penetration. Channel partners supply real-time demand signals that speed replenishment and reduce stockouts. Established relationships cut selling costs and improve shelf presence, while the network enables faster, pan‑regional new product rollouts.
Serving both domestic and export markets diversifies Donear Industries exposure to local currency cycles and international macro shifts, while exports help secure higher-margin bulk and premium orders and act as a partial hedge during domestic slowdowns.
Cross-market feedback enhances product design and compliance, raising quality standards and boosting brand recognition among global buyers, widening distribution channels and repeat corporate contracts.
Supplying formalwear, casualwear and denim lets Donear address multiple consumer occasions, blend high-volume basics with higher-margin specialty finishes, and cut fashion and seasonality risk; India textile and apparel exports were about $44.4 billion in 2023–24 and the sector employs ~45 million, supporting multi-cycle demand stability.
Donear’s diversified suiting, shirting and denim mix, 30+ years manufacturing depth and integrated plants deliver cost control, faster lead times and quality consistency. Extensive distributor network and export access (India apparel exports $44.4bn in 2023–24) broaden reach, stabilize cash flows and capture higher-margin orders.
| Metric | Value |
|---|---|
| Manufacturing vintage | 30+ years |
| India apparel exports | $44.4 bn (2023–24) |
| Sector employment | ~45 million |
 Detailed Word Document
Delivers a strategic overview of Donear Industries’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats while highlighting competitive position, growth drivers, operational gaps, and market risks shaping its future.

 Customizable Excel Spreadsheet
Provides a concise SWOT matrix tailored to Donear Industries for fast strategic alignment and competitive textile market clarity; editable format enables quick updates to reflect shifts in demand, raw material costs, and distribution strategies for rapid stakeholder decision-making.
Yarn, cotton and dyes drive Donear Industries input costs, and sharp spikes—often driven by spot cotton volatility and dye chemical shortages—can materially compress margins when price hikes cannot be passed to buyers. Use of hedging and inventory buffers mitigates risk but raises treasury complexity and working capital intensity. Such input volatility frequently distorts quarterly EBITDA and revenue comparatives.
Textile operations force Donear to carry broad inventory across counts, colors and finishes, resulting in inventory days often exceeding 120, which raises carrying costs. Extended credit to distributors further ties up cash, with receivable cycles stretching industry-typical 60–90 days. Slow-moving SKUs increase obsolescence risk and markdowns, pressuring gross margins. High working capital intensity can limit capacity for capex or marketing during downcycles.
Reliance on distributors limits Donear Industries' ability to build direct consumer brand equity, leaving consumer perception shaped more by channel partners than the company. Weak end-customer pull constrains pricing power and forces margin erosion during promotions. High dependence on channel push increases promotional spend to clear inventory and reduces control over markdown timing. Limited D2C data restricts insight into rapidly shifting consumer tastes and personalization opportunities.
Exposure to fashion cycles forces Donear to refresh denim and shirting assortments rapidly, raising markdown risk when trends shift and mixing impacts gross margins.
Forecasting errors cause excess inventory or stock-outs, increasing working capital and obsolescence costs when agility is limited.
Faster cycles lift sampling and development expenses and can erode margin if product-development lead times and supply-chain flexibility are insufficient.
Textile processing is highly water-, energy- and chemical-intensive, and tightening environmental norms force Donear Industries to invest in effluent treatment and cleaner technologies; non-compliance can trigger regulatory fines and loss of export orders, while required transition capex and operating changes can compress near-term margins.
Input-cost volatility (cotton, dyes) compresses margins; hedging raises treasury and working-capital strain. Inventory days often exceed 120 and receivable cycles run 60–90 days, increasing carrying costs and obsolescence risk. Distributor-led sales limit D2C brand control, forcing promotions and margin erosion. Environmental compliance requires capex and higher OPEX, pressuring near-term margins.
| Metric | Value/Status |
|---|---|
| Inventory days | >120 |
| Receivable cycle | 60–90 days |
| Channel mix | Distributor-dependent |
| Regulatory capex | Required (water/effluent) |
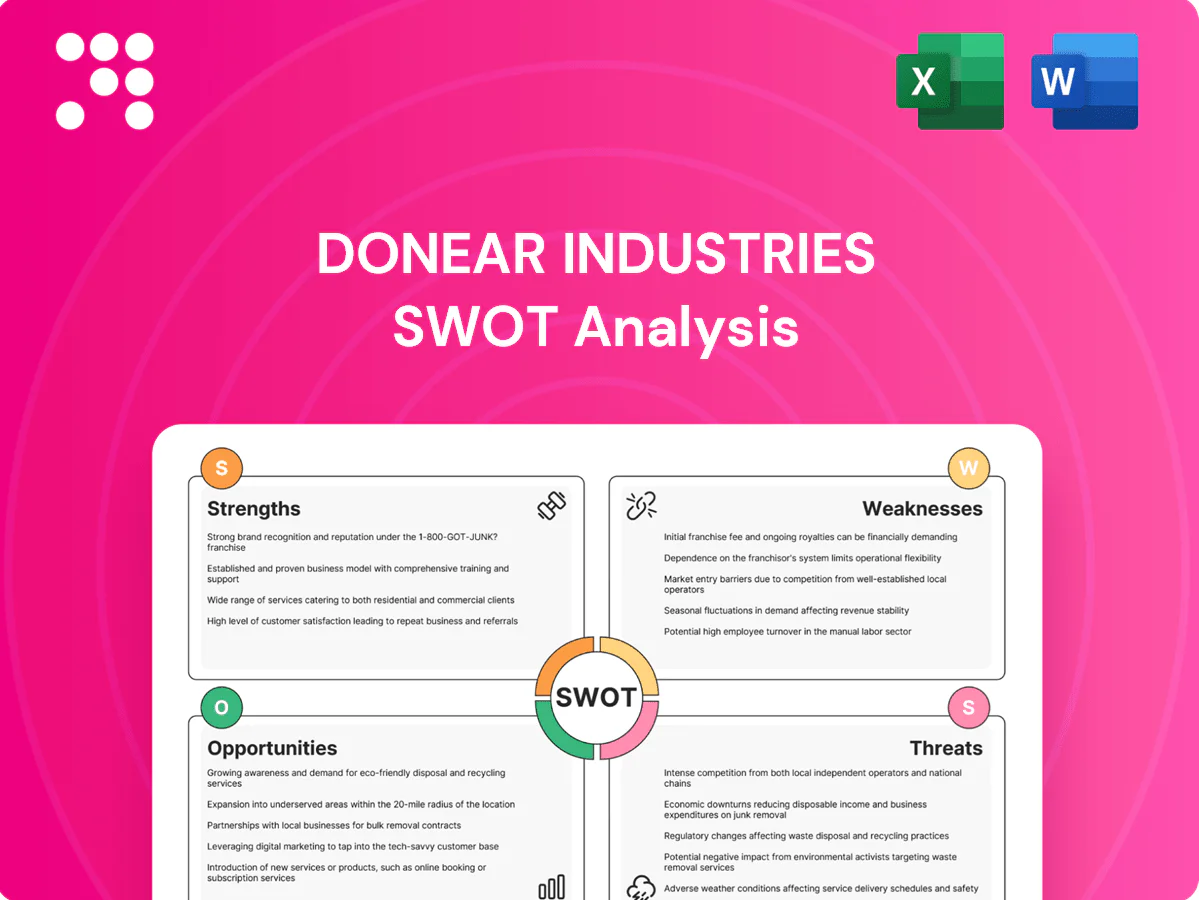
This is the actual Donear Industries SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report; buying unlocks the complete, editable version. You’re viewing a live excerpt of the real file, ready for download after checkout.
Premiumization through moisture-management, wrinkle-resist and stretch finishes can lift ASPs and gross margins—brands report ASP uplifts of 10–25% for performance-treated shirting; the global performance fabrics market was estimated at about USD 24–26 billion in 2024 with mid-single-digit CAGR. Differentiated finishes create defensible niches for brand buyers and certifications (Oeko‑Tex, GOTS) unlock premium retailers' listings. Upselling within existing channels boosts ROI by raising basket value and repeat purchase rates.
Rising demand for recycled fibers and sustainable blends is accelerating, and investing in eco-friendly processes can help Donear capture ESG-sensitive export orders as India’s textile exports reached $44.3 billion in FY2023-24 (Ministry of Commerce). Technical fabrics for uniforms and workwear provide stable, high-volume demand and diversify the business away from pure fashion volatility, improving revenue predictability and margin resilience.
E-commerce and B2B portals can streamline sampling and ordering for Donear, reducing lead times and costs while tapping into India's ~840 million internet users (2023). Limited D2C pilots will build consumer insight and brand recall without disrupting wholesale channels. Data-driven assortments can raise sell-through and cut returns; digital catalogs shorten time-to-market for seasonal drops, improving margin capture.
Expanding into underserved Tier-2/3 cities and select export corridors can scale Donear’s volumes while capturing regional preferences through localized assortments; India is the world’s second-largest textile exporter, and India-UAE CEPA (2022) plus other trade pacts ease market access. China+1 sourcing trends favor capable Indian mills, offering new revenue channels and diversification that spread currency and policy risks.
Automation in weaving, dyeing and finishing can cut defects by up to 30% and energy use by 15–20%, while lean practices typically reduce waste 20–50% and changeover times ~40%, improving throughput; better planning can lift on-time delivery KPIs by 10–25%, and 100–300 bps of cost savings can be reinvested into innovation and branding.
Premiumization (performance finishes) can lift ASPs 10–25%; global performance fabrics ~USD 25B (2024). Sustainability/recycled blends capture ESG export demand as India textile exports were USD 44.3B (FY2023-24). Digital/B2B and Tier‑2/3 expansion tap 840M internet users (2023) and China+1 tailwinds; automation can save 100–300bps margin.
| Opportunity | 2024/25 datapoint |
|---|---|
| Performance fabrics | ~USD 25B (2024) |
| India exports | USD 44.3B (FY2023-24) |
| Internet users | 840M (2023) |
| Automation margin gain | +100–300bps |
Global cotton cycles and crude-linked synthetics drive unpredictable raw-material costs—ICE Cotton averaged about 96 cents/lb in 2024 while Brent crude averaged near $88/bbl, feeding polyester and yarn price swings. Energy price spikes (power and gas) raise processing expenses and compress margins. Price volatility complicates forward pricing and contract negotiations with buyers. Prolonged spikes risk customer down-trading to cheaper fabrics.
Domestic mills and low-cost imports squeeze prices, with Bangladesh RMG exports topping about $40 billion in 2023, increasing competitive pressure on Indian players. Fast-fashion timelines (Zara ~2 weeks from design to store) favor ultra-agile suppliers over traditional players. Large firms such as Arvind and Raymond leverage scale to undercut smaller rivals. Margin erosion of roughly 100–300 bps was reported across commoditized SKUs in 2023.
Changes in export incentives, duties or tightening of environmental norms can compress margins for Donear, given India’s textile and apparel exports near USD 44 billion in FY24, exposing exporters to policy shifts. Non-tariff barriers and compliance audits have delayed shipments in 2024, raising working capital days. Currency volatility — INR swings of several percent vs USD in 2024 — directly affects export realizations and may force costly process changes.
Macroeconomic downturns reduce discretionary apparel demand, causing retailers to cut orders and delay season launches. Inventory gluts at retail chains trigger order cancellations and push brands into deeper markdowns; fashion misreads amplify return rates and margin erosion. Liquidity strains can tighten quickly as receivables stretch and inventories accumulate.
Supply chain disruptions—logistics bottlenecks and port congestion—have delayed exports, while input shortages have forced periodic production stoppages; global container freight rates swung from peaks over 10,000 USD/FEU in 2021 to roughly 2,000 USD/FEU by 2024, keeping costs volatile. Geopolitical events (trade restrictions, reroutes) raise freight costs and timelines, and repeated disruptions erode service levels and customer loyalty for Donear.
Raw-material and energy volatility (ICE cotton ~96¢/lb in 2024; Brent ~$88/bbl) raises input cost risk and margin squeeze. Low-cost imports and scale players (Bangladesh RMG ~$40bn in 2023; India textile exports ~$44bn FY24) intensify price competition and margin erosion. Logistics, policy shifts and currency swings (freight 10,000→2,000 USD/FEU) disrupt exports and cash flow.
| Risk | Key 2023–24/24 Data |
|---|---|
| Input & energy | ICE cotton 96¢/lb (2024); Brent $88/bbl |
| Competition | Bangladesh RMG ~$40bn (2023); India exports ~$44bn FY24 |
| Logistics | Freight 10,000→2,000 USD/FEU |


