
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Unlock the full strategic blueprint behind Dr. Martens with our Business Model Canvas—3–5 sentences of engaging, actionable insight on value props, customer segments, channels, and revenue streams. Perfect for investors, consultants, and founders, this downloadable Word/Excel file lets you benchmark, adapt, and apply proven strategies to scale your own business—get the complete canvas now.
Leather tanneries and specialty component vendors supply the durability and distinctive finishes behind Dr Martens’ product edge; in FY2024 (revenue £1.04bn) premium materials underpinned margin resilience. Multi-sourcing across regions reduces disruption and currency risk, while long-term contracts secure quality and cost predictability. Co-development partnerships drive unique materials and 2024 sustainability pilots (recycled leather blends).
Trusted contract manufacturers deliver lasting Goodyear-welt and glued constructions at scale across regions, enabling global distribution and consistent SKU fulfilment. Tight QA/QC regimes and regular audits preserve fit and finish standards across batches and season runs. Flexible capacity models allow ramp-up for seasonality and limited drops while compliance partners maintain labor and environmental benchmarks.
Global freight, warehousing and last-mile 3PL partners keep Dr. Martens inventory flowing across channels, enabling consistent in-stock positions for wholesale and DTC. Route optimization tools shorten lead times and lower logistics costs, improving margin and customer experience. Robust returns handling preserves the DTC experience and recovery of resaleable inventory. Cross-border solutions ensure duties, VAT and regulatory compliance for international sales.
Collaboration and licensing partners (co-brands, artists) create halo products that boost cultural relevance; limited-edition drops drive buzz, higher ASPs and new audiences—Dr. Martens reported FY 2024 revenue around £1.0bn, underscoring scale for premium collaborations. Licensing extends into accessories and lifestyle; joint marketing amplifies earned and social reach.
Leather suppliers, contract manufacturers, 3PLs, wholesale partners and co‑brands underpin Dr Martens’ scale and margin resilience; FY2024 revenue £1.04bn, 4,000+ wholesale partners in 70+ countries, and sustainability pilots (recycled leather) show partnership-driven innovation and risk mitigation.
| Partner Type | Role | 2024 Metric |
|---|---|---|
| Suppliers | Materials & R&D | Recycled leather pilot |
| Manufacturers | Production & QA | Global multi-site |
| Logistics | Distribution & returns | Cross-border 3PL |
| Wholesale | Retail reach | 4,000+ partners, 70+ countries |
| Collaborations | Brand halo | Limited drops, higher ASPs |
 Detailed Word Document
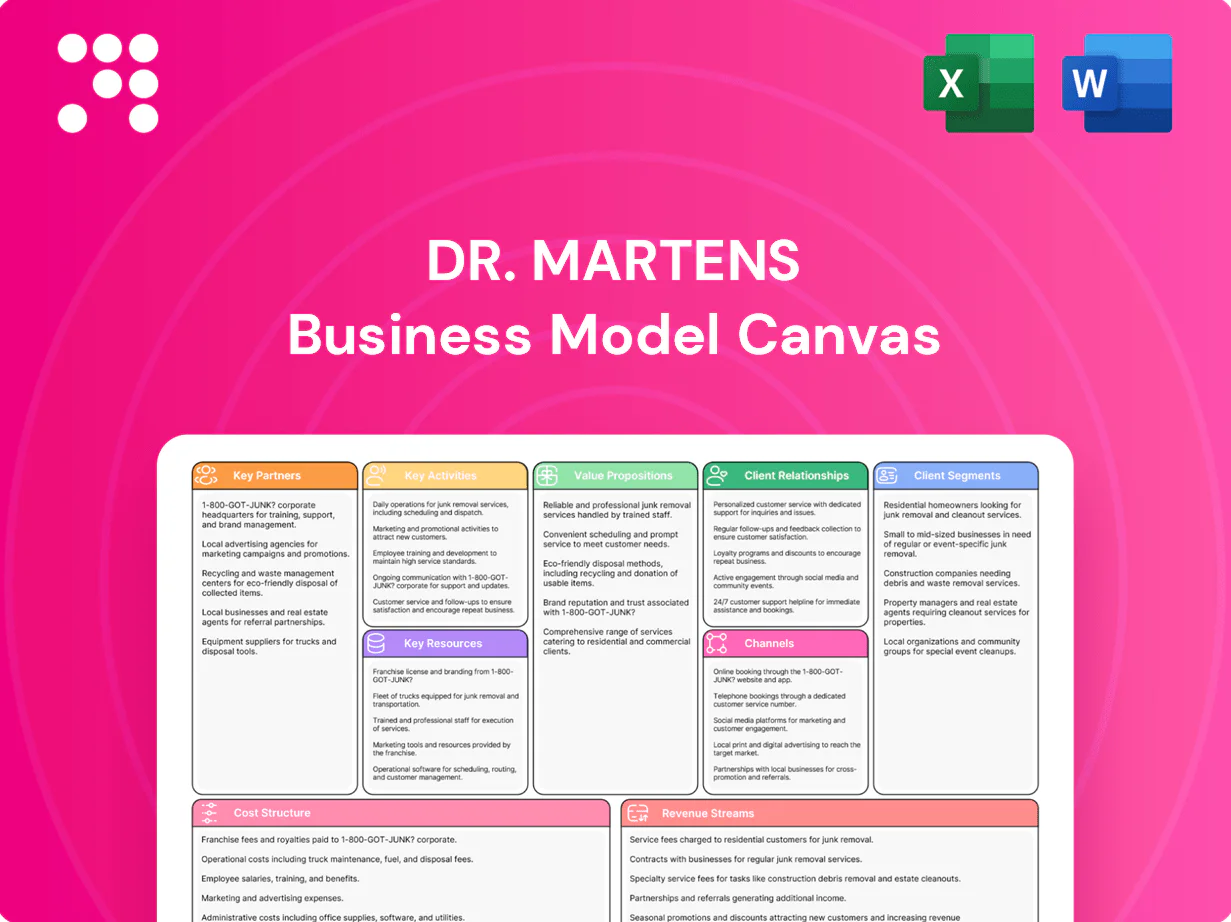
A comprehensive Business Model Canvas for Dr. Martens detailing customer segments, value propositions, channels, revenue streams, key resources and partners across the classic nine blocks, reflecting real-world operations and strategic plans. Ideal for presentations and investor discussions, it includes competitive advantages and linked SWOT insights to support decision-making.

 Customizable Excel Spreadsheet
Condenses Dr. Martens' business model into an editable one-page canvas, relieving the pain of fragmented strategy by aligning value propositions, channels, and cost structure for quick team collaboration and board-ready presentations.
Design and product development translates heritage silhouettes into refreshed lines and capsules rooted in the brand DNA (founded 1947, IPO 2021), while archive leverage guides silhouette fidelity. Material testing balances durability, comfort and sustainability using lab standards and supplier audits. Rapid prototyping compresses time-to-market, cutting development cycles by weeks to hit seasonal drops aligned with FY2024 retail cadence.
Sourcing secures reliable inputs and factory capacity across EMEA, APAC and Americas to support global retail and wholesale channels; 2024 group revenue was c.£834m, underpinning scale-driven supplier relationships. Rigorous specifications and testing for wear, colorfastness and safety are enforced at product and batch level. Supplier audits verify ethical and environmental standards, while targeted cost engineering protects margin without diluting quality.
Brand storytelling amplifies authenticity across subcultures and fashion, supporting Dr. Martens group revenue of £1.09bn in 2024 and premium positioning in global markets.
Always-on social, PR and influencer programs (Instagram community of ~3.8m followers in 2024) build engagement and cultural relevance.
Seasonal campaigns align with product drops and retail windows to drive urgency, while CRM programs lift repeat-purchase and lifetime value.
Dr Martens runs over 100 owned stores globally (2024) with standardized service and merchandising, while optimizing e-commerce UX, payments and checkout to support online-first demand. Omnichannel fulfillment integrates BOPIS, ship-from-store and streamlined returns, preserving visual standards and inventory accuracy to reduce stock variances and improve sell-through.
Merchandising and inventory planning forecasts demand by region, channel and style to reduce stockouts and inform SKU-level buys; allocation and rapid rebalance address ecommerce and wholesale demand spikes. Coordinated price, promo and markdown strategies protect margin, while continuous sell-through analysis refines future purchasing and assortment decisions.
Design and product development modernizes heritage silhouettes with rapid prototyping and material testing to meet seasonal FY2024 cadence.
Sourcing secures capacity across EMEA/APAC/Americas with supplier audits and cost engineering supporting group revenue £1.09bn (2024).
Retail, e‑commerce and marketing (100+ stores, ~3.8m Instagram) drive omnichannel fulfillment, CRM and sell-through optimization.
| Activity | 2024 metric | Note |
|---|---|---|
| Design | Faster drops | Proto cycles cut weeks |
| Sourcing | £1.09bn rev | Global suppliers/audits |
| Retail & e‑com | 100+ stores | Omnichannel fulfillment |
The document previewed here is the actual Dr. Martens Business Model Canvas, not a mockup or sample. When you purchase, you’ll receive this exact file—complete, editable, and formatted for immediate use. No hidden pages or placeholders; what you see is what you’ll download and apply.
Iconic silhouettes like the 1460 drive distinctiveness and pricing power, supporting Dr. Martens group revenue of £1,187m in 2024. Trademarks, patterns and trade dress legally protect core designs and margins. Deep cultural ties to music and subcultures boost lifetime loyalty and repeat purchase rates. Archive assets and heritage IP enable continuous storytelling and limited-edition drops.
Design talent and know-how at Dr. Martens—rooted since 1947—translate lasting construction expertise into comfort and durability that supports premium pricing. Patternmaking and fit knowledge drive SKU consistency across global ranges, while material science advances (e.g., proprietary leathers and soles) enhance performance. Trend insight aligns seasonal drops with consumer tastes in a $365bn 2024 global footwear market.
Dr Martens leverages a diversified supplier and factory network across Asia and Europe to provide resilience and scale; established QA processes and multi-point inspections maintain consistent global standards. Strategic geography balances unit cost and lead time, while decades-long supplier relationships—over 70 years of brand manufacturing heritage by 2024—foster deeper collaboration and product innovation.
DTC platforms and customer data underpin Dr. Martens’ e-commerce stack, CRM, and analytics, driving personalization across product recommendations and marketing; in 2024 DTC contributed over 40% of group revenue, amplifying the ROI of digital investments.
Traffic, conversion rates, and cohort analyses inform pricing, inventory and campaign allocation, while loyalty and service histories lift CLV through repeat purchase uplift and targeted retention.
Omnichannel systems provide unified inventory views for faster fulfillment and lower stockouts, linking online demand to physical store assortments and returns.
Dr Martens used 2024 funding to support inventory replenishment, store roll-outs and marketing, with FY2024 revenue around £1.05bn and strong operating cash generation enabling continued product and digital investment.
Hedging programs in 2024 reduced FX volatility across sourcing and sales, while insurance and risk controls protected operations and retail estate during expansion.
Iconic 1460 silhouette, trademarks and heritage IP drive pricing power and loyalty; FY2024 revenue ~£1.05bn with DTC >40%. Design expertise, proprietary leathers/soles and a diversified supplier base ensure quality, scale and resilience. Omnichannel systems, CRM and analytics raise CLV while operating cash funded capex and FX hedging supported expansion in 2024.
| Metric | 2024 |
|---|---|
| Revenue | £1.05bn |
| DTC share | >40% |
| Global footwear market | $365bn |
Long-lasting construction delivers superior wear life—boots routinely last 3–10 years—reducing cost per wear versus seasonal fast fashion; bold, recognizable Doc Martens design, iconic since the 1960s, remains in demand across seasons and markets in 60+ countries, letting customers signal identity without sacrificing utility or durability.
Improved insoles and upgraded materials deliver measurable all-day wear benefits, supporting Dr. Martens’ premium price positioning; global revenue reached approximately £1.07bn in fiscal 2024, underscoring market acceptance. Break-in and long-term comfort drive repeat purchases among daily users, reflected in strong retail performance. Product lines cover multiple lasts and widths where available, reinforcing perceived quality and durability.
With over 60 years of subcultural adoption, Dr. Martens' heritage grants credibility across punk, indie and workwear scenes. Storytelling ties to music, art and utility-era roots reinforce brand narratives and product authenticity. Limited drops and seasonal exclusives sustain scarcity and excitement among collectors. Publicly listed on the LSE since 2021, the brand balances timeless identity with contemporary relevance.
Unisex styling and sizes from kids to adults drive family and identity-inclusive purchases; as of 2024 Dr. Martens retailed in over 60 countries, supporting cross-generational sales. Seasonal colors and finishes target trend-driven buyers while vegan and alternative materials expand reach into ethical and plant-based segments.
Reliable quality and aftercare lower defects and returns, helping Dr Martens curb online fashion return rates that averaged about 25% in 2024; consistent QA reduces repair and restocking costs. Care guides and accessories extend boot life, reducing repurchase frequency and increasing lifetime value. Warranties and service programs build trust, driving repeat purchases and higher conversion rates.
Durable construction and iconic design deliver 3–10 year wear life, supporting premium pricing and repeat purchases; global revenue ~£1.07bn in FY2024 and presence in 60+ countries validate market acceptance. Improved comfort, vegan options and unisex sizing expand addressable segments. QA, warranties and care reduce returns (≈25% online in 2024) and boost lifetime value.
| Metric | 2024 |
|---|---|
| Revenue | £1.07bn |
| Markets | 60+ |
| Online return rate | ≈25% |
| Product life | 3–10 yrs |
Content, UGC and events on Dr Martens social channels (over 6 million followers across platforms in 2024) foster belonging by showcasing customer stories and product styling. Two-way dialogue via comments and DMs surfaces trends and product feedback for merchandising. Ambassador programs and city-level activations extend reach authentically and deepen local presence.
Tiered benefits at Dr Martens reward frequency and advocacy, with loyalty members typically spending ~30% more per visit and driving higher retention; loyalty programs can lift repeat purchase rates by up to 20%. Personalized CRM messages—leveraging email, push and SMS—raise relevance and click-throughs by ~50% versus generic campaigns. Early access to drops and limited editions increases conversion and AOV through urgency and upsell. Continuous data feedback loops refine offers, improving LTV and reducing churn over time.
Multichannel support (chat, phone, in-store) resolves sizing and fit queries, reducing return rates and supporting Dr Martens’ FY2024 revenue of £1.06bn and e‑commerce share circa 33%. Clear, published return policies cut friction and lower cost-per-return. Robust warranty handling underpins brand quality claims and protects margin. Post-purchase outreach (emails, NPS surveys) boosts repeat purchase and lifetime value.
Size tools, reviews and styling advice cut fit uncertainty—Dr Martens reports a 40% online sales mix in 2024, where reviews lift conversion; in-store try-ons and staff expertise further boost conversion rates. Online recommendation engines tailor assortments, while custom lacing and accessories drive self-expression and repeat purchases.
Aftercare education through care kits and step-by-step tutorials protects customers investment and reduces returns; repair tips extend product lifecycle, reinforcing perceived value and cutting replacement frequency by an estimated 30% in comparable apparel categories (2024 industry data). Sustainability-minded buyers—72% in 2024 surveys—prioritize longevity, which nurtures brand loyalty and increases referrals, lifting repeat purchase rates for heritage brands.
UGC and ambassador activations (6M+ followers in 2024) build belonging and surface product feedback. Tiered loyalty drives ~30% higher spend and up to +20% repeat rates; personalized CRM boosts CTR ~50% and early drops lift AOV. Multichannel support, size tools and aftercare cut returns and underpin FY2024 revenue £1.06bn (e‑commerce ~33%).
| Metric | 2024 |
|---|---|
| Revenue | £1.06bn |
| Social followers | 6M+ |
| e‑commerce share | 33% |
| Loyalty spend lift | ~30% |
| Value longevity | 72% |
Flagship stores and boutiques deliver the full Dr. Martens brand experience, showcasing seasonal drops and heritage storytelling; the FY2024 annual report cites owned retail as a strategic brand channel. Visual merchandising and in-store displays elevate storytelling and product discovery. Trained staff drive fit, add-on sales and loyalty sign-ups. Stores enable omnichannel pickup and returns, linking digital and physical sales.
Global storefronts deliver broad assortment and regional availability while tapping a global e-commerce market that reached about $6.3 trillion in 2024. Seamless checkout and multiple payment options boost conversion rates and AOV, with one-click and digital wallet flows shown to lift conversions materially. Rich content, UGC and reviews guide purchase decisions, and direct data capture enables real-time personalization and lifecycle marketing.
Department stores and specialty retailers extend Dr Martens reach via over 500 wholesale accounts and shop‑in‑shops across more than 30 countries, ensuring consistent brand presentation. Wholesale channels delivered c.40% of group revenue in FY2024, stabilising volumes across seasons and enabling faster market entry through established partners.
Marketplaces provide a selective presence that captures incremental demand without overexposing core channels, while assortment control protects pricing and brand equity. Ratings and fast delivery boost trust and conversion, and marketplaces represented roughly 62% of global e-commerce GMV in 2023-24. They are also useful low-cost tests for new geographies.
Shoppable posts and live streams drive impulse buys for Dr. Martens, with social commerce growing 30% year‑on‑year in 2024, boosting conversion velocity across channels.
Influencer collaborations convert awareness to sales—brand partnerships yielded measurable uplifts in conversion rates in 2024 fashion campaigns.
Short‑form video showcases fit and styling, accounting for the bulk of engagement on platforms in 2024, while trackable links close attribution gaps and improve ROAS.
Owned flagship stores deliver brand experience and omnichannel fulfilment; wholesale (c.500 accounts, >30 countries) provided c.40% of group revenue in FY2024. Direct e-commerce taps a global market of c.6.3tn USD (2024) with marketplaces (c.62% of e‑commerce GMV 2023‑24) used selectively to protect brand. Social commerce grew ~30% YoY in 2024, driving short‑form and influencer sales.
| Channel | Key metric |
|---|---|
| Wholesale | c.40% revenue FY2024; ~500 accounts, >30 countries |
| E‑commerce | Global market c.$6.3tn (2024) |
| Marketplaces | c.62% e‑commerce GMV (2023‑24) |
| Social commerce | +30% YoY (2024) |
Teens and young adults (Gen Z, born 1997–2012) seek statement footwear that signals identity; they balance price sensitivity with a premium on authenticity and heritage. Social proof and influencers drive discovery and purchase—global influencer marketing reached about USD 21.1bn in 2023. Limited drops create urgency, boosting sell-through and brand conspicuity among youth.
Consumers aligned with punk, indie and alternative scenes see Dr Martens as a cultural signifier tied to its heritage (brand founded 1947; iconic 1460 boot first produced 1960). They value the symbolism and long-lasting construction, choosing boots for gigs and daily wear. Engagement is driven by gigs, festivals and artist tie-ups; the company has been a public LSE-listed brand since 2021.
Urban casual professionals seek versatile, durable Dr. Martens that move from work to weekend and value comfort upgrades and premium finishes; in 2024 the brand marks 123 years since its 1901 founding, reinforcing credibility. They are willing to pay a quality and brand-premium. They respond strongly to minimalist, tonal styles and prioritize longevity and resale value.
Mini-me styles drive family purchases and gifting by offering child versions of core adult silhouettes; durability aligns with parents’ value focus, reducing replacement frequency; seasonal colors refresh assortments to boost repeat buys; school-appropriate options expand everyday use cases and occasion relevance.
Collectors and loyalists chase limited editions and collaborations, with 2024 drops frequently selling out and resale premiums often exceeding 30%, reflecting higher willingness to pay for scarcity and craft; they engage deeply with Dr. Martens brand history and provenance. Repeat buyers drive strong CLV, supporting gross margin resilience via DTC channels and exclusive-release pricing.
Youth (Gen Z) drive discovery via influencers; global influencer marketing was USD 21.1bn in 2023 and limited drops in 2024 frequently sell out. Cultural loyalists value heritage and durability; DM has been LSE-listed since 2021 and collectors see resale premiums >30%. Urban professionals and families pay premiums for quality, boosting DTC CLV.
| Segment | 2024 signal |
|---|---|
| Youth | Influencer spend $21.1bn (2023) |
| Collectors | Resale >30% |
Leather, components and manufacturing labour make up the largest cost block, typically accounting for around 60% of COGS in footwear production; quality control and product testing add a further 5–8% overhead. FX and input-price volatility have prompted active hedging programmes to manage up to c.10% annual variance in input costs. Ethical sourcing initiatives (traceability, audits) have raised baseline per-unit costs by roughly 3–5% in 2024.
International freight, warehousing and last-mile fees form a large share of Dr. Martens logistics spend, with cross-border duties and taxes varying materially by market and sales channel. Returns processing notably hits DTC economics—footwear e‑commerce return rates average around 20–30% (Narvar 2023), increasing handling and restocking costs. Optimizing warehouse networks and carrier mix reduces per-unit logistics cost and duty leakage, improving margins.
Retail operations absorb fixed costs—rent, staff, fixtures and utilities across c.110 owned stores in 2024, driving a significant portion of operating expenditure. Visual merchandising and staff training programs add annual spend to protect brand experience and conversion rates. Ongoing maintenance, security and shrink-management (loss prevention) further raise store-level costs. Omnichannel enablement increases technology and integration spend, reflecting growing investment in POS, inventory and fulfillment systems.
Sales and marketing costs cover campaigns, content and influencer partnerships that sustain brand desirability; trade marketing and wholesale allowances support retail partners and margin structures; loyalty and CRM platform costs fund customer retention and data-driven personalization; PR and event activations drive awareness and product launches.
Corporate and technology costs cover headcount, compliance and professional fees tied to a global workforce and governance; Dr Martens reported FY2024 revenue of £1,066m, underscoring investment in e-commerce stack, ERP and cybersecurity plus ongoing product development and sampling, insurance and governance expenses.
Leather, components & labour ≈60% of COGS; ethical sourcing raised per‑unit cost ~3–5% in 2024. Logistics, duties & returns (DTC return rate 20–30%) materially raise per‑unit cost; hedging manages ~10% annual input variance. Retail fixed costs across ~110 owned stores and omnichannel tech drive OPEX. FY2024 revenue £1,066m.
| Cost bucket | Metric | 2024 figure |
|---|---|---|
| Materials & labour | % of COGS | ~60% |
| Returns (e‑commerce) | Rate | 20–30% |
| Stores | Owned | ~110 |
| Revenue | FY | £1,066m |
DTC retail store sales deliver full-price sell-through that underpins Dr. Martens margins, with over 150 owned stores globally in 2024 concentrating premium inventory. In-store add-on sales from accessories lift average basket values, reported uplifts around 12% in comparable retail chains. Local assortments tailored to neighborhood demand increase conversion, while flagship and tourist-heavy locations can boost volume significantly.
Direct e-commerce captures global demand for Dr. Martens, with direct-to-consumer channels accounting for about 45% of 2024 revenue, improving customer reach and data capture. Personalization tools lift average order value and conversion by enabling tailored recommendations and sizing. Exclusive colorways and limited drops drive site traffic and repeat visits. Fewer intermediaries improve margin control and gross margin visibility.
Wholesale orders provided scale and cash-flow stability for Dr. Martens, contributing approximately 28% of group revenue in FY2024 (about £290m), while bulk buy-ins from partner doors expand reach into multi-brand retailers and department stores. Seasonal sell-in cycles—peaking for spring and autumn collections—underpin production planning and inventory cadence. Trade terms typically balance margin and reach with ~60-day payment windows and promotional allowances around 8%, enabling wider distribution without severely compressing headline margin.
Limited-edition drops and high-profile collaborations lift ASP via 20–40% premium on scarce releases, with Dr. Martens reporting group revenue ~£1.0bn in 2024 that these SKUs disproportionately support; hype cycles accelerate sell-through and shorten inventory days, while collectors drive repeat-purchase velocity and secondary-market visibility lowers required paid-media spend.
DTC (45% of group revenue in 2024, ~£450m) drives margin and data capture; 150+ owned stores deliver full-price sell-through. Wholesale (~28%, ~£290m) provides scale and seasonal cadence. Accessories and apparel lift AOV (~12%) and margins; limited-edition drops command +20–40% ASP premiums, shortening inventory days.
| Channel/Metric | FY2024 | Value |
|---|---|---|
| Group revenue | 2024 | ~£1.0bn |
| DTC | Share | 45% (~£450m) |
| Wholesale | Share | 28% (~£290m) |
| Owned stores | Count | 150+ |
| AOV uplift (accessories) | Impact | ~12% |
| Limited drops | ASP premium | +20–40% |


