
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
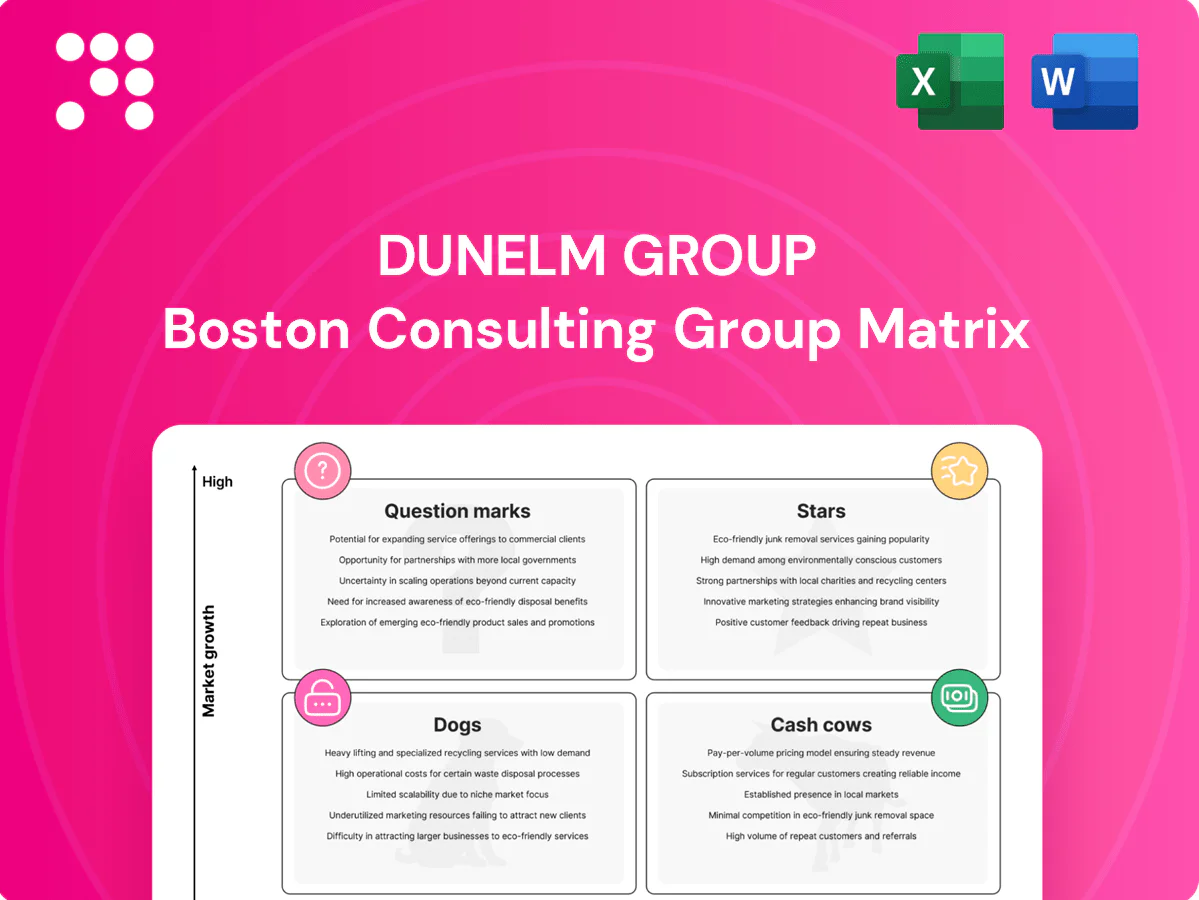
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick snapshot: the Dunelm Group BCG Matrix highlights where homeware lines are winning, which ranges milk the cash flow, and which SKUs could be quietly draining resources. This preview teases quadrant placements and a few directional insights, but the full BCG Matrix gives you a quadrant-by-quadrant breakdown, hard data, and actionable recommendations you can implement tomorrow. Purchase the full version for a ready-to-use Word report and Excel summary—strategic clarity without the hours of digging.
High offline share via 170+ UK stores plus a fast-growing online channel (online penetration c.30% in 2024) make Dunelm an omnichannel leader in a growing market. Store + e-com synergy boosts footfall and basket size, but sustaining leadership requires heavy investment in tech and UX. Continue to fund app, search, fulfillment and last-mile to protect growth. Hold share now; it can mature into a cash cow later.
UK homeware e‑commerce continues expanding, with online retail accounting for about 30% of UK retail sales in 2024, and Dunelm’s site/app leverages that curve at scale. The group has been investing heavily in platform speed, personalization and delivery promises, driving elevated capex to support digital growth. Small uplifts in conversion and average order value compound market share and lifetime value, turning today’s tech and logistics spend into tomorrow’s margin.
High adoption, fast turn and strong attachment rates make Dunelm's Click & Collect a Star: by FY24 Click & Collect accounted for c.35% of online fulfilment, delivering faster conversion and higher AOVs and driving NPS uplift; it owns mindshare at the decision moment, hard for competitors to replicate. Tight inventory accuracy and store ops investment remain critical to maintain service levels; if share is preserved it will mature into steady cash generation.
Design‑led, affordable private‑label ranges anchor Dunelm, driving repeat purchase in a still‑expanding UK homewares market; Dunelm operates around 170 stores plus online, giving scale to set the category price/value bar. These lines need ongoing marketing and visual merchandising to maintain velocity; sustained share and scale convert Stars into cash cows as growth normalises.
Big-ticket furniture online is a Star for Dunelm: in 2024 the category grew faster than core homewares and Dunelm is gaining share through omni-channel fulfilment and improved click-and-collect. Investment remains capital-hungry—professional photography, AR tools, more delivery slots and returns handling drive capex and Opex. Winning trust now (delivery reliability, guarantees) locks lifetime value; as growth normalises, margin leverage should improve.
Dunelm’s Stars: 170+ UK stores plus c.30% online penetration (2024) drive omnichannel leadership; Click & Collect = c.35% of online fulfilment (FY24), boosting conversion and AOV. Big-ticket furniture grew faster than core in 2024, requiring elevated tech, logistics and delivery investment to convert Stars into future cash cows.
| Metric | 2024 |
|---|---|
| Stores | 170+ |
| Online penetration | c.30% |
| Click & Collect | c.35% of online fulfilment |
| Big-ticket growth | Above core (2024) |
 Detailed Word Document
In-depth BCG Matrix review of Dunelm Group, identifying Stars, Cash Cows, Question Marks and Dogs with strategic actions.

 Customizable Excel Spreadsheet
One-page BCG map placing Dunelm units into quadrants to cut complexity and speed strategic focus.
Bedding core sits as a mature, high‑share category for Dunelm with consistent turns and reliable margins, driving steady store and online conversion across the over 170 stores in 2024. Promotional pressure is relatively low versus traffic captured, preserving margin. The line generates cash to fund digital investment and new bets, while tight quality control and incremental efficiency measures maintain profitability.
Curtains and ready‑made blinds sit as Dunelm cash cows: established UK leadership in a mature soft‑furnishings market, replenishment‑friendly with strong brand recall and dependable cash flow; Dunelm reported c.£1.4bn group revenue in FY2024. Limited category growth means focus on supply‑chain efficiency and SKU rationalization to widen margins, while investing just enough to defend shelf and online search presence.
Kitchenware staples are Dunelm's cash cows: predictable, high-volume basics sold across c.170 stores and online, driving steady gross margin and funding overheads plus new launches. Low marketing spend; availability and scale purchasing (category leverage) sustain yields. Focus on optimizing pack sizes and own‑brand mix preserves margin and cash conversion.
Dunelm’s private‑label margin engine delivers higher gross margins in stable homewares categories, with own brands accounting for c.70% of sales in 2024 and supporting group gross margin outperformance versus peers.
Share is entrenched in the UK market with modest unit growth; private‑label cash flow funds R&D and digital features, including a 2024 investment uplift in omnichannel platforms.
Maintaining design cadence and strict vendor terms preserves margin advantage and supply resilience, keeping private label as a Cash Cow in the BCG matrix.
Bedding, curtains/blinds and kitchenware are Dunelm cash cows: mature, high‑share categories generating steady cash (group revenue c.£1.4bn FY2024; c.170 stores), strong margins via c.70% own‑brand mix, low promo and maintenance capex, funding digital and R&D while supply‑chain efficiencies protect profitability.
| Metric | FY2024 |
|---|---|
| Group revenue | c.£1.4bn |
| Stores | c.170 |
| Own‑brand | c.70% |
| Role | Cash generation / low capex |
The Dunelm Group BCG Matrix you’re previewing on this page is the exact file you’ll receive after purchase. No watermarks, no demo placeholders—just a fully formatted, analysis-ready report tailored for strategic decisions. After buying, the full document is immediately downloadable and editable for presentations or planning. It's the same polished deliverable, ready to use.
Over‑assorted tail SKUs in Dunelm tie up working capital in slow markets, diluting focus away from core lines while group revenue was about £1.4bn in FY2024.
These long‑tail items represent a tiny share of sales with negligible growth, yet consume disproportionate inventory space and management hours.
Turnaround efforts burn time and cash; the best path is aggressive pruning of low‑velocity SKUs and redeploying space to higher‑margin, faster‑turning ranges.
Legacy print/leaflet spend for Dunelm is a classic cash trap: low incremental traffic, a shrinking audience and rising unit costs with market growth flat to down; 2024 industry trends show digital ad spend up ~8% while traditional print budgets continue to decline, making turnaround hard to justify. Divert budget to digital where attribution and ROI measurement are clearer.
Underperforming low‑traffic micro‑locations in weak catchments show low market share and flat demand; Dunelm operates over 170 stores (2024) so marginal sites drag group ROI. Fixes are costly and largely cosmetic, with refurbishments rarely improving unit economics and often only restoring break‑even. Break‑even at best means trapped capital; consider exiting or repurposing as dark pickup points where last‑mile density makes logistics viable.
Obsolete décor sublines sit in Dogs: trend‑miss products in saturated niches crawl with minimal sell‑through and contribute to Dunelm Group's slowing category performance; FY2024 revenue was £1.37bn and these lines dilute SKU productivity. The market shows no growth and brand share in these micro‑niches is tiny, while frequent markdown cycles erode margin and cash conversion. Clear out and simplify the range to stop margin leakage.
Aging third‑party partner labels in Dunelm’s aisles deliver low growth and low share, dragging shelf productivity; 2024 trading updates highlighted stagnant sales for these ranges despite category investment. Promotional support has shown minimal incremental uplift, indicating limited elasticity and cannibalisation of core ranges. Strategy: retire underperformers or replace with stronger exclusive lines that drive margin and loyalty.
Dogs in Dunelm: slow‑moving long‑tail SKUs, obsolete décor sublines and ageing third‑party labels tie up inventory and margin despite group revenue of £1.37bn in FY2024; low share, flat demand and heavy markdowns erode cash conversion. Recommend aggressive SKU pruning, site exits/repurposing and shifting spend to digital and exclusive ranges to restore ROI.
| Metric | 2024 |
|---|---|
| Group revenue | £1.37bn |
| Stores | 170+ |
| SKU tail impact | High inventory & low sell‑through |
Adding third‑party sellers can grow the pie fast, but Dunelm’s marketplace is nascent versus core retail; FY2024 group revenue was about £1.23bn, underlining scale but limited marketplace contribution. It needs investment in tech, curated onboarding and strict service SLAs — cash hungry early. If adoption lifts assortment, choice and conversion it can flip to a Star; if not, cut quickly.
Home services (installation, measuring, assembly) ride the experience trend but start with low share for Dunelm; FY2024 group revenue was £1,279m, so services would initially represent a small single-digit percentage of sales. Operational complexity and partner quality make unit costs high at rollout, raising CAC and margin pressure. Win trust and attachment and it scales; if uptake stalls, narrow scope or divest.
Trade/B2B targets an attractive growth pool of bulk orders from landlords and SMEs, with SMEs still representing 99.9% of UK businesses in 2024, but Dunelm's brand presence in B2B remains small. It will require dedicated account management, tiered pricing and firm service SLAs, and early returns can be thin until scale. Double down if repeat rates prove out.
International shipping is a Question Mark for Dunelm: online cross‑border demand is growing but the retailer’s international revenue share remains negligible versus its UK core, despite group online sales rising c.20% in 2023.
Logistics, duties and returns typically add 15–30% to cost per order, soaking cash early; Dunelm should test limited ranges and markets and scale only when unit economics become positive.
Subscription/loyalty plus with tiers, perks and replenishment can lift LTV in a retention play despite current low share; needs data science for targeting, offer funding and tight CX to scale. If it raises frequency and margin mix it can move from Question Mark to Star; if engagement lags, sunset quickly. FY2024 revenue ~£1.3bn underscores upside but execution risk remains.
Dunelm’s Question Marks (marketplace, home services, B2B, international, subscription) require upfront tech/partner investment against FY2024 group revenue ~£1,279m; logistics/duties can add 15–30% to cost per order. Test limited ranges, track unit economics and LTV/CAC; scale only when unit economics >0 or sunset quickly.
| Initiative | FY2024 base | Key metric | Action |
|---|---|---|---|
| Marketplace | £1,279m | GMV growth, take rate | Limit SKUs, SLAs |
| Home services | small % sales | Unit economics | Pilot regions |


